Moneyfarm Review: Is 0.70% a Year Worth Paying to Have Your ISA Managed?
Moneyfarm reviewed: who runs it and how your investments are protected, Active vs Fixed Allocation vs Smart Yield, what a managed portfolio costs from £1,000 to £100,000, the Wealth tiers, DIY share dealing fees, withdrawals and transfers, the fee discount behind code MF650641, what users complain about and who should skip it.
Last updated 12 October 2026
Best for
UK investors with a few thousand pounds or more who want a ready-made ISA, pension, Junior ISA or general account that someone else picks and rebalances, who would use human support as their balance grows, and who are happy paying for that.
Moneyfarm is a managed service, and the fees are the price of the management. On an actively managed £20,000 portfolio Moneyfarm's own fees come to £140 a year (0.70%), or up to £182 (0.91%) once fund costs and spread are added. Small balances pay more, because the platform fee has a £1.25-a-month minimum: £1,000 costs about 2% a year. Fixed Allocation is cheaper at 0.15% plus the 0.25% platform fee, and the management fee drops above £50,000, which is also where the human support (consultants from £10,000, a dedicated wealth manager from £100,000) starts to earn its keep. The referral discount behind code MF650641 is small: Moneyfarm's invite screen says it's 20% off your fees for six months once you start investing, which on an actively managed £20,000 saves about £9 if it comes off the management fee alone, or £14 if the platform fee is discounted too. Choose Moneyfarm for the service, not the code.
Pros
- Ready-made portfolios matched to a suitability questionnaire, then rebalanced for you
- Managed Stocks and Shares ISA (flexible), Junior ISA, SIPP and general account, plus DIY share dealing and a Cash ISA in the same app
- Active management fees fall as you invest more: 0.20% from £50,000, 0.10% from £100,000 and nothing above £1.5 million
- Cheaper styles if you don't want active management: Fixed Allocation at 0.15% and Smart Yield at 0.05%, plus the platform fee
- Human help grows with your balance: investment consultants from £10,000, a dedicated wealth manager from £100,000
- No entry, exit, withdrawal or top-up fees; investments held in a nominee under FCA client-asset rules, with FSCS cover up to £85,000 if Moneyfarm fails
Watch-outs
- About 0.70% a year in Moneyfarm fees on a typical actively managed balance, up to 0.91% with fund costs and spread
- The £1.25-a-month platform minimum makes small balances expensive: about 2% a year on £1,000
- £500 minimum to start, and portfolios under £5,000 may hold more cash than planned
- Withdrawals can take 7 to 10 working days to reach your bank
- Slow transfers and hard-to-reach support are the most common complaints
- No Lifetime ISA, and the referral discount is small: 20% off for six months is worth about £9 to £14 on £20,000
Current related offer
Moneyfarm offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Moneyfarm
Rather leave the stock-picking to someone else? Moneyfarm runs managed portfolios for ISAs, pensions and general accounts. Join through our link or with code MF650641 and, according to Moneyfarm's in-app invite screen, your Moneyfarm fees are cut by 20% for 6 months once you start investing. It's a discount rather than cash, and it never touches fund costs or Share Investing charges. You'll need £500 to open a managed account. Investing involves risk; not investment advice.
Requirement: £500 minimum to open a managed account; top-ups from £100
Medium10-15 minutesPayout Fee discount, not cash: 20% off your Moneyfarm fees for 6 months once you start investing
Verified 12 October 2026
Full claim instructions are on the Moneyfarm offer page.
What Moneyfarm is and how your money is protected
Moneyfarm is the trading name of MFM Investment Ltd, a London company incorporated in June 2014 (Companies House number 09088155, registered at 90-92 Pentonville Road). It says it is authorised and regulated by the Financial Conduct Authority with firm reference number 629539, for investment advice, discretionary management, custody and dealing. The FCA's own register data, as at 11 October 2026, lists firm 629539 as MFM Investment Ltd, authorised since July 2015; you can check it on the FCA register before you send money.
Your investments are held under the FCA's client-asset (CASS) rules, registered to a nominee and kept separate from Moneyfarm's own investments. Moneyfarm says this minimises the chance of loss if it became insolvent. If it did fail and you lost money as a result, the Financial Services Compensation Scheme (FSCS) can cover eligible investments up to £85,000. Nothing covers a fall in the markets: the value of your portfolio can go down as well as up.
The pension works a little differently. Quai Investment Services Limited provides and runs the Moneyfarm SIPP, Quai Trustees Limited holds its assets as trustee, and Moneyfarm manages the investments and runs the app you use.
Accounts, and what's missing
The managed side, which Moneyfarm calls Wealth, covers a Stocks and Shares ISA, a Junior ISA, a SIPP and a general investment account (GIA). Moneyfarm's management and platform fees are the same for all four. The Stocks and Shares ISA is flexible: you can take money out and put it back in the same tax year without using up more of your £20,000 allowance for 2026/27. You need to be UK-resident to open one.
Alongside that, Share Investing lets you pick your own shares, ETFs, funds and bonds (Moneyfarm says more than 1,000) in an ISA or GIA, and there is a Cash ISA with no direct charge; Moneyfarm is paid by the money market funds the Cash ISA uses. For pensions, its Find, Check & Transfer service traces old pensions and, before moving them, flags any exit fees, or benefits you would give up by moving, worth more than £50 (it says it can't promise to find them all), at no extra charge once they arrive.
What's missing: there is no Lifetime ISA, and the managed portfolios are Moneyfarm's models, not funds you choose. If you want to pick investments yourself, that's Share Investing, which has its own price list.
Active, Fixed Allocation or Smart Yield?
Sign-up starts with a suitability questionnaire about your goals, finances and attitude to risk. Moneyfarm then recommends a model portfolio for each account, built and maintained by its investment team, and manages your money in line with it. It rebalances without asking you and reviews whether the portfolio still suits you at least once a year.
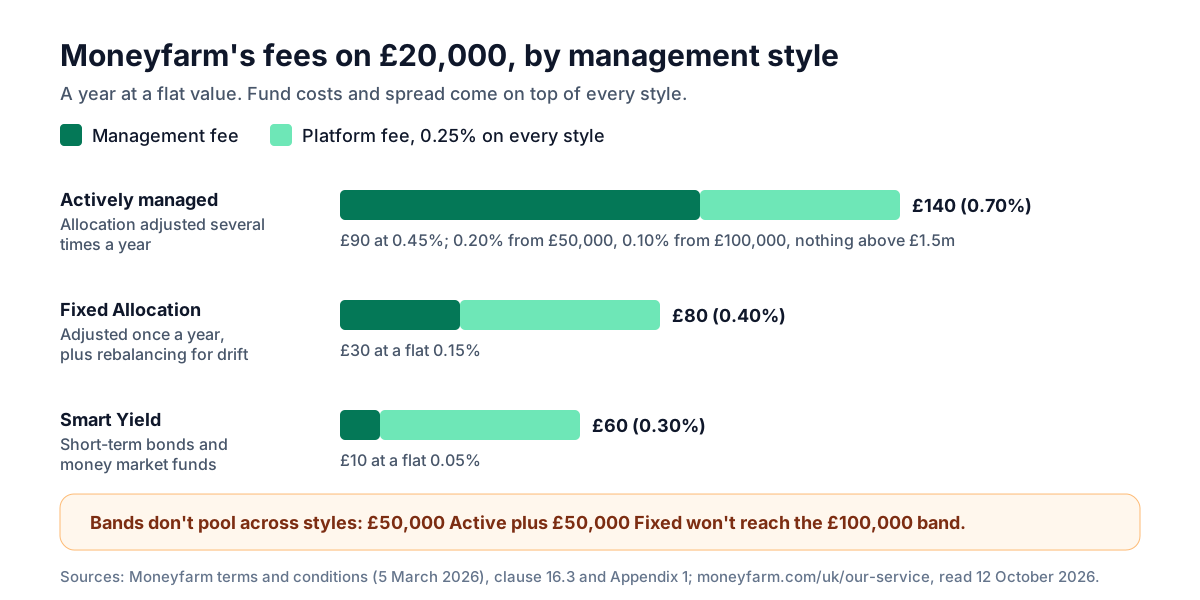
You then choose a management style. Actively managed portfolios have their mix adjusted several times a year, for 0.45% on the first £50,000, falling in bands above that. Fixed Allocation is adjusted once a year, plus any rebalancing needed when the mix drifts, for a flat 0.15%. Smart Yield holds short-term, lower-risk debt such as government bonds, commercial paper and certificates of deposit, or money market funds plus higher-yielding ETFs, for a flat 0.05%. Every style also pays the 0.25% platform fee.
You also choose a focus: Classic, a globally diversified mix that isn't screened for ESG, or ESG, screened using MSCI data and Moneyfarm's own method, both at the same management fee. Thematic investments can be added to an ISA or GIA once the main portfolio holds £10,000, but only if your risk profile is Balanced or higher (Balanced, Curious, Adventurous or Fearless), and themes are capped at around 20% of the riskiest portfolios.
One catch: the Active fee bands count Active money only. £50,000 in Active plus £50,000 in Fixed Allocation won't reach the 0.10% band that starts at £100,000.
What a managed portfolio really costs
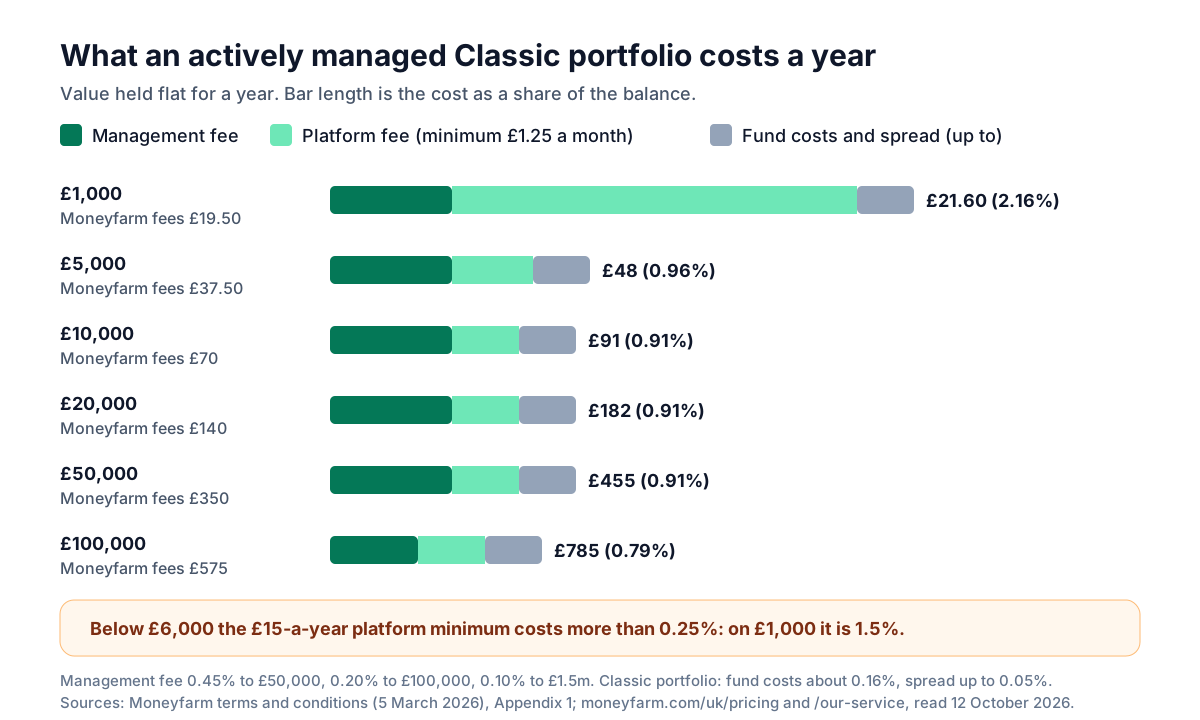
You pay Moneyfarm two fees, both worked out daily and taken monthly: the management fee for your style and the platform fee of 0.25% a year, with a minimum of £1.25 a month. On top come the costs inside the funds, which Moneyfarm puts at around 0.16% a year for a Classic portfolio, and market spread of up to 0.05%; for ESG portfolios its figures are 0.17% and 0.07%. Those don't arrive as a bill; they come out of the fund prices.
Moneyfarm's own example is £20,000 in an actively managed Classic portfolio: 0.70% in its fees (£11.67 a month), and up to 0.91% (£15.17 a month) with fund costs and spread. The same rates give £70 a year on £10,000 and £350 on £50,000. Above £50,000 the bands bring the rate down: £100,000 pays £575 (0.575%), or up to £785 all-in, and Moneyfarm's terms show £120,000 paying £345 in management fees.
Small balances are where it gets expensive. Below £6,000 the £1.25-a-month minimum (£15 a year) is more than 0.25%: £1,000 pays £19.50 a year in Moneyfarm fees, or 1.95%, and £5,000 pays £37.50 (0.75%).
For comparison, InvestEngine charges nothing for DIY ETF portfolios and 0.25% a year for managed ones, plus the ETFs' own costs in both cases. The gap is what you pay for Moneyfarm's active management and its human support, so ask whether you'll use them. Moneyfarm can change its fees with 15 days' written notice.
Wealth tiers: who you can talk to
Your tier depends on the value of your managed portfolios. Core, under £10,000, gets the client service team. Premium, from £10,000 to under £100,000, adds access to Moneyfarm's investment consultants during business hours, though not one assigned to you. Private, from £100,000, adds a dedicated qualified wealth manager, priority access to in-person events and one Guidance+ session a year.
Guidance+ is a one-to-one session with scenario and cash-flow analysis, a personalised report and a virtual consultation, and can cover investments you hold elsewhere. Moneyfarm says it isn't regulated financial advice. Outside Private it costs £200 plus VAT, or you can unlock the Private tier's benefits for £12.99 a month with a three-month minimum.
Moving up happens within five business days of crossing a threshold. Moving down waits 30 days (Premium to Core) or 90 days (Private to a lower tier).
Share Investing: the DIY side
Share Investing has no platform fee. Instead, each trade in shares, ETFs or funds costs £3.95, and each bond trade £5.95, whatever the size. Anything priced in another currency adds a 0.70% conversion fee on every buy and sell. In a Share Investing ISA there is also a custody fee of 0.35% a year, capped at £45.
UK share purchases pay 0.5% stamp duty, and the PTM levy applies to trades over £10,000. Moneyfarm's fee discounts, including the referral one, don't reduce any of these Share Investing charges.
Paying in, getting money out and transfers
You need £500 to start and at least £100 for each top-up. Pay by Direct Debit or bank transfer from a UK account in your own name. Direct Debits typically take three business days to reach Moneyfarm, and up to seven. Between £500 and £5,000 Moneyfarm may not be able to build a fully balanced portfolio, so expect more cash than usual until you add more.
Moneyfarm processes withdrawals within one business day of your request, but warns it can take 7 to 10 working days from asking to seeing the money in your bank. It only pays to the UK bank account registered to your account, and charges no withdrawal fee. Don't keep money here that you might need at short notice.
ISA transfers out are normally handled within HMRC's 30-day maximum, although Moneyfarm depends on the receiving provider. If you transfer an ISA, Lifetime ISA or Junior ISA in, you can cancel that transfer within 30 days of Moneyfarm receiving it.
Code MF650641: what the 20% discount is worth
Sign up through our link or enter code at registration, and check it shows as applied before you finish. Moneyfarm's in-app Invite a friend screen describes the reward: you and the person who invited you both get a 20% discount for six months when you start investing. It's a discount on your fees, not cash, and Moneyfarm's live terms set the exact conditions.
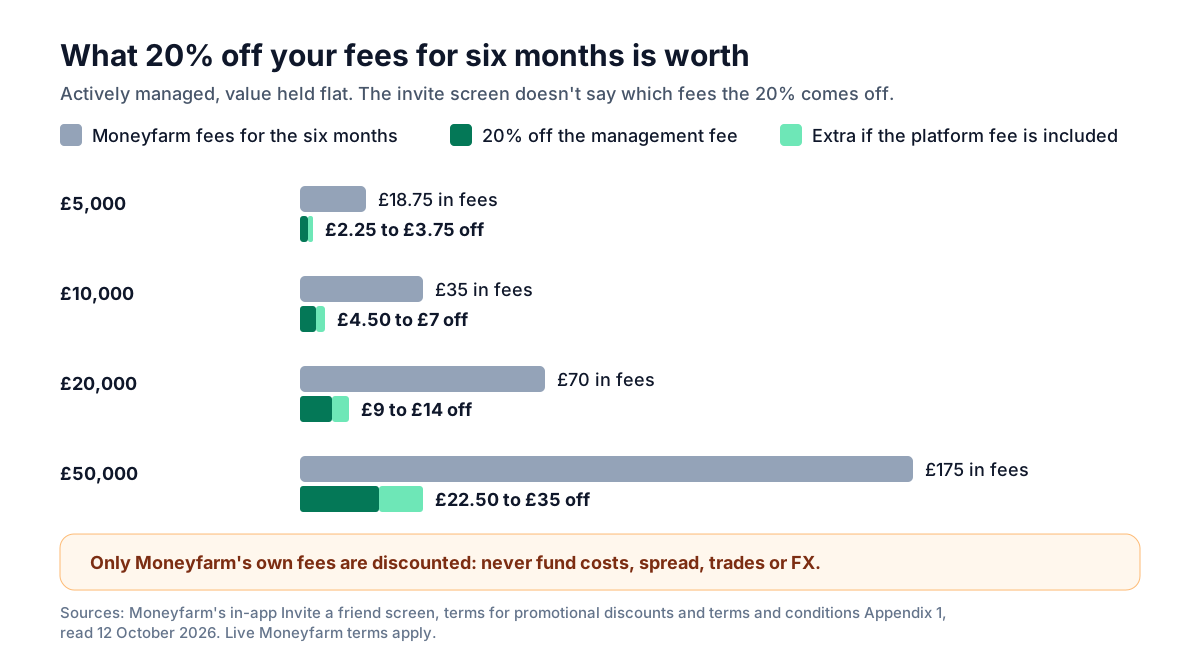
The screen doesn't say which fees the 20% comes off. Moneyfarm's general terms for discounts say they reduce only its management and platform fees, never fund costs, trading or currency fees; they have no cash value, and any part bigger than the fee due in a month is lost. A Cash ISA has no management or platform fee, so a fee discount has nothing to come off, and Share Investing's charges aren't covered either. You still need the £500 minimum to open an account.
In money terms it is small. On an actively managed £20,000 portfolio, Moneyfarm's fees for six months come to £70: £45 of management fee and £25 of platform fee. 20% off the management fee saves £9, and £14 if the platform fee is discounted too. On £50,000 it's £22.50 or £35. On Fixed Allocation, at 0.15%, 20% off the management fee is worth £3 on £20,000 over the six months.
Moneyfarm can change or withdraw the offer at any time and can decline to open an account. Its 2024 Refer a Friend terms said personal referral links shouldn't be published publicly and let Moneyfarm refuse the discount if it suspected they had been. If the discount hasn't been applied after your first monthly fee, ask Moneyfarm.
Disclosure: MF650641 is GetQuids' own Moneyfarm code. Moneyfarm's invite screen says you both get the discount, so we get the same 20% off our fees for six months.
What users complain about
On 12 October 2026 the Moneyfarm app was rated 4.6 from 1,920 ratings on the App Store (version 7.44, released on 5 October) and 4.4 from 7,679 on Google Play. On Trustpilot Moneyfarm scored 4.2 from 6,947 reviews, 58% of them five-star and 7% one-star, and it replies to about 90% of negative reviews.
The recent low-rated reviews repeat the same themes: slow transfers out and slow ISA transfers, including one Cash ISA transfer reported to have taken three months; support that is hard to reach, with bounced emails and missed call-backs or appointments; deposits and transferred-in money left uninvested for days; withdrawals taking days or longer; and recent app updates, with the October 2026 version removing landscape view on iPad and reviewers calling the app cluttered. Others question returns after fees compared with investing themselves, and one mentions a recent fee rise. Older reviews mention trouble disinvesting or closing an account, no way to delete bank details or the account in the app, and heavy marketing notifications.
You can phone Moneyfarm on 0800 433 4574 or email hello@moneyfarm.com. Complaints are acknowledged within three working days and get a final response within eight weeks; after that you can go to the Financial Ombudsman Service, free, within six months.
Opening, cancelling and closing
You need to be 18 or over with a UK bank account, and to pass identity and source-of-funds checks; Moneyfarm may ask for proof that money came from your own UK account and that your wealth comes from a legitimate source. If it can't finish opening your account within 28 days, it can refuse. Moving abroad or changing your tax residency lets Moneyfarm end the agreement.
The steps: sign up through our link or with code MF650641, complete the questionnaire, choose an account, style and focus, and pay in at least £500.
You can cancel the whole agreement within 30 days of opening it, or any single product within 30 days of opening that product. After that, give 30 days' notice; there is no penalty, but fees due up to that point are deducted. Unless you give transfer instructions, your portfolio is sold and the proceeds go to your registered bank account, at whatever the investments are worth by then.
Who should use it, and who should skip it
Consider it if you want someone else to choose and rebalance your ISA, pension or Junior ISA, if you'll have £10,000 or more and would use the investment consultants, or £100,000 or more and want a dedicated wealth manager, or if Fixed Allocation's lower fee suits a hands-off investor.
Skip it if you'll invest less than about £6,000, where the platform minimum bites; if you're happy choosing a global tracker yourself on a cheaper platform; if you might need the money within days; if you want a Lifetime ISA; or if you may move abroad. And don't choose it for the referral discount alone: on £20,000 it is worth about £9 to £14, and the value of your investments can fall.
FAQ
- Is Moneyfarm safe?
- Your investments are held in a nominee under the FCA's client-asset rules, separate from Moneyfarm's own. If Moneyfarm failed and you lost money as a result, the FSCS can cover eligible investments up to £85,000. Nothing protects you from the markets falling.
- How much does Moneyfarm cost?
- For an actively managed portfolio, 0.45% a year on the first £50,000 plus a 0.25% platform fee (minimum £1.25 a month), so 0.70% on most balances, plus fund costs and spread of up to 0.21% on a Classic portfolio. Fixed Allocation is 0.15% and Smart Yield 0.05%, each plus the platform fee.
- What's the minimum investment?
- £500 to start and £100 for each top-up. Thematic investments need £10,000 in the main portfolio, and below £5,000 your portfolio may hold more cash than usual.
- What does code MF650641 get me?
- Moneyfarm's invite screen says a 20% discount on your fees for six months once you start investing, not cash; the live terms set the exact conditions. On an actively managed £20,000 that is worth about £9 off the management fee, or £14 if the platform fee is discounted too. It doesn't apply to Share Investing.
- Is the Moneyfarm ISA flexible?
- Yes. You can withdraw from the Stocks and Shares ISA and put the money back in the same tax year without it counting again towards your £20,000 allowance.
- How long do withdrawals take?
- Moneyfarm processes requests within one business day but says money can take 7 to 10 working days to reach your bank. There is no withdrawal fee.
- Can I talk to a person?
- Everyone can phone or email the client service team. From £10,000 you also get access to investment consultants, and from £100,000 a dedicated wealth manager. Smaller accounts can pay £12.99 a month for the Private tier's benefits.
- Does Moneyfarm offer a Lifetime ISA?
- No. It offers a Stocks and Shares ISA, Junior ISA, Cash ISA, SIPP and general investment account, plus DIY Share Investing in an ISA or general account.