J.P. Morgan Personal Investing Review: Is the Former Nutmeg Worth 0.63% to 1.18% a Year?
J.P. Morgan Personal Investing, formerly Nutmeg, reviewed: who runs it and how your money is protected, the accounts and six investment styles, what each style really costs a year, the six-month fee waiver by invite and its conditions, withdrawals and transfers, what users complain about and who should skip it.
Last updated 12 October 2026
Best for
UK residents who want a ready-made ETF portfolio run for them in a Stocks & Shares ISA, Lifetime ISA, Junior ISA, pension or general account, and would rather pay for that than choose their own funds.
This is Nutmeg under a new name: the same managed ETF portfolios, now branded J.P. Morgan. It does the job if you want your investing done for you, but you pay for it. On the first £100,000, the cheapest style, Fixed Allocation, costs about 0.63% a year all-in and the dearest, Income, about 1.18%; £10,000 in the original Fully Managed style costs about £97 a year. The six-month management fee waiver you get through our invite saves about £18.75 on £5,000, so treat it as a small discount, not a reason to join. You can't buy individual shares or pick your own funds, the ISA isn't flexible and there's no Cash ISA. If you're happy choosing a global tracker yourself, compare a DIY platform's costs first.
Pros
- Hands-off: J.P. Morgan's in-house team builds and runs a diversified ETF portfolio for you, in one of six styles at the risk level you pick
- Stocks & Shares ISA, Lifetime ISA, Junior ISA, Personal Pension and general account in one app, with separate pots for different goals
- Low minimums: £100 for a Lifetime or Junior ISA, £500 for the ISA, pension and general account
- Fixed Allocation costs about 0.63% a year all-in, and the management fee drops above £100,000
- No fee to join, withdraw or hold a cash-only pot, and no minimum investment period
- Cash held as client money at an approved bank, investments held by a custodian (State Street), and FSCS cover up to £85,000 if the firm fails
Watch-outs
- The five managed styles cost about 0.97% to 1.18% a year all-in on the first £100,000
- No individual shares, no choosing your own funds and no Cash ISA; the DIY platform J.P. Morgan promised for 2026 isn't on its site yet
- The ISA isn't flexible: money you take out still counts towards that tax year's allowance
- Uninvested cash earns the Bank of England rate minus 0.75%, and cash-only pots earn nothing
- The fee waiver needs £500 of new money within 30 days of your first investment, even in a Lifetime or Junior ISA; transfers in don't count, and the normal fee applies until the waiver starts
- Android users rate the app 3.2, and recent complaints centre on held-up withdrawals, slow support and slow transfers
Current related offer
J.P. Morgan Personal Investing offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
J.P. Morgan Personal Investing
Nutmeg under its J.P. Morgan name now does referrals. Request a private invite from this page, open your account with the same email, and invest at least £500 of new money within 30 days of your first investment (yes, £500 even for a Lifetime or Junior ISA, and transfers in don't count). You then pay no management fee for 6 months, a fee that's normally 0.75% a year on the first £100,000, or 0.45% in Fixed Allocation. Just to be straight: it's a fee holiday, not cash in hand. Fund costs and the spread still apply, the 0% can take up to 45 days to kick in, and on £5,000 the whole thing is worth about £18.75. You get a managed ETF portfolio in the style and risk level you choose, not your own pick of shares or funds, so only fund it if that suits you beyond the free period. Investing involves risk; not investment advice.
Requirement: £500 of new money within 30 days of your first investment, even in a Lifetime or Junior ISA
Medium15-20 minutesPayout 0% management fee applied within 45 days of your first investment, then lasts 6 months
Verified 12 October 2026
Full claim instructions are on the J.P. Morgan Personal Investing offer page.
What it is: Nutmeg with a J.P. Morgan name
J.P. Morgan Personal Investing is the robo-adviser most people still know as Nutmeg. Nutmeg was founded in 2012 and bought by JPMorganChase in 2021. The new name was announced on 1 October 2025, and apps and dashboards switched over on Monday 3 November 2025. The company is the same one: J.P. Morgan Personal Investing Limited (Companies House number 07503666) was called Nutmeg Saving and Investment Limited from May 2012 until October 2025, and its terms say any reference to Nutmeg means J.P. Morgan Personal Investing. Nutmeg.com now redirects to the new site.
Existing Nutmeg clients didn't have to do anything. J.P. Morgan kept all the Nutmeg products and services, and the fee schedule in force today dates from June 2025, before the new name. It added a wealth planner to the app, said clients with more than £250,000 invested would get a relationship manager from November 2025, and promised "a full DIY investment platform in 2026" for buying your own shares, bonds and funds. On 12 October 2026 its website listed no DIY or share-dealing service, so for now you can only invest through its managed portfolios.
It is a discretionary manager. You choose an investment style and a risk level, and its investment team decides which ETFs to hold and when to trade. You don't pick individual investments.
How your money is protected
J.P. Morgan Personal Investing Limited says it is authorised and regulated by the Financial Conduct Authority, Financial Services Register number 552016, with its office at 25 Bank Street, Canary Wharf. Look it up on the FCA register before you send money.
Your cash is held as client money in a pooled account at an approved bank, separate from the firm's own money. Your investments are held in custody through a nominee company or sub-custodian, and J.P. Morgan names State Street as its custodian bank. Its terms also say that neither it nor its custodians will lend your investments to anyone or use them to raise money.
If the firm failed and couldn't return what it owes you, the Financial Services Compensation Scheme (FSCS) can pay up to £85,000 per person, per firm, for investments. The FSCS never pays for poor investment performance. And the J.P. Morgan name isn't a safety net: the site's own small print says JPMorgan Chase Bank, N.A. does not stand behind the investments. Like any investment, your portfolio can fall and you may get back less than you put in.
Accounts, minimums and who can open one
There are five products: a Stocks & Shares ISA, a Lifetime ISA, a Junior ISA, a Personal Pension and a General Investment Account (GIA). The minimum is £500 for the ISA, the pension and the GIA, and £100 for a Lifetime or Junior ISA. Income Investing pots need £10,000. Card payments must be at least £75, and you can split your money into separate pots for different goals.
The Stocks & Shares ISA isn't flexible: if you take money out, that part of your allowance stays used, so paying it back in later in the same tax year counts again. There's no Cash ISA, although you can transfer an existing cash or stocks and shares ISA in.
You must open the Lifetime ISA before you turn 40, and you can't pay into it from 50. Take money out for anything other than a first home costing up to £450,000, retirement from 60 or terminal illness, and the government charges 25%. The Personal Pension is provided by Embark Services Limited, and you can't normally take money out until 55 (57 from April 2028). A Junior ISA belongs to the child, who can only withdraw from 18.
To open an account you must be 18 or over and normally live in the UK. J.P. Morgan Personal Investing doesn't take US persons.
The six investment styles, and what you can't do
Every style invests in exchange-traded funds (ETFs), runs at the risk level you choose and is managed by J.P. Morgan's in-house team. Fully Managed is the original Nutmeg style: passive ETFs, with the team adjusting the mix as markets change. Smart Alpha holds mainly active ETFs and is managed using research from J.P. Morgan Asset Management. Socially Responsible Investing uses passive ETFs leaning towards companies with higher environmental, social and governance standards. Thematic Investing tilts passive ETFs towards a theme such as AI or healthcare, and isn't available in the pension.
Income Investing buys ETFs likely to pay dividends and pays you a monthly income from an ISA or GIA, from £10,000; the income isn't fixed and can fall. Fixed Allocation holds a long-term mix set by the team, rebalanced automatically when it drifts too far and reviewed once a year. It is also the cheapest style, as the next section shows. The pension offers Fully Managed, Socially Responsible Investing, Smart Alpha and Fixed Allocation.
What you can't do: buy individual shares or investment trusts, or choose your own funds. If that matters, this isn't the service for you until the promised DIY platform appears.
One niche advantage: because the portfolios are discretionary, J.P. Morgan says they are generally exempt from employers' personal account dealing rules, which often restrict staff in finance, law, accounting and government. It can send a letter to your compliance team to confirm it, but check with your employer's rules first.
Fees: what you really pay
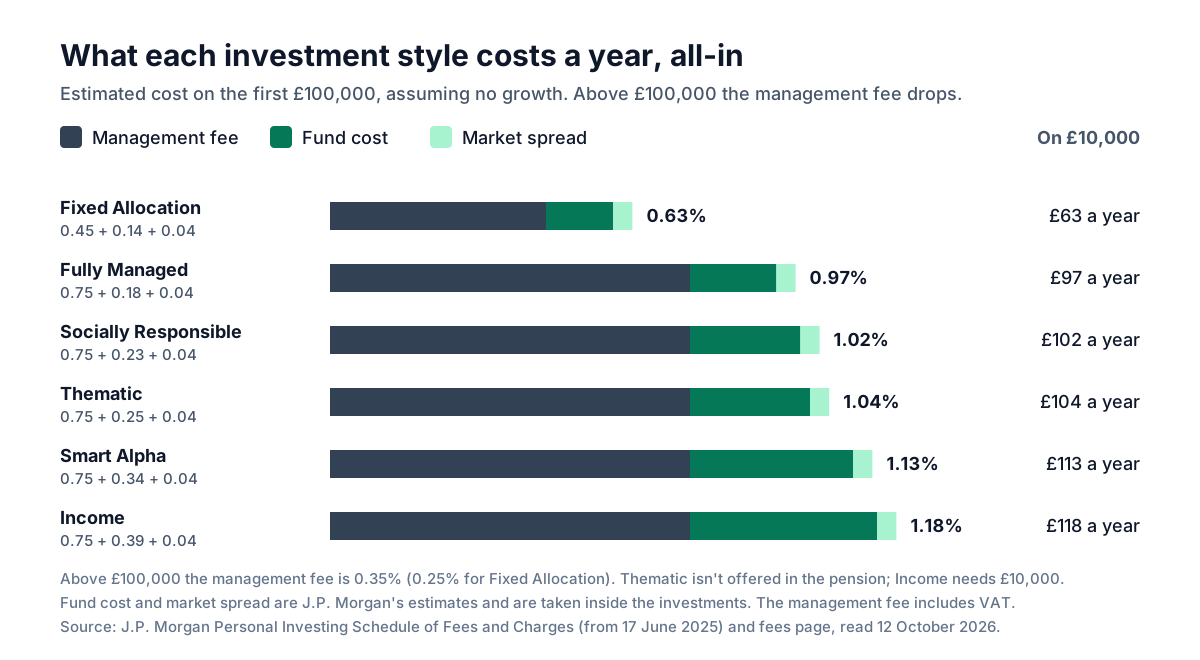
You pay three things. The management fee is 0.75% a year including VAT on the first £100,000 across the five managed styles, and 0.35% on anything above that; money in different managed styles is added together for the £100,000. Fixed Allocation is priced separately at 0.45%, then 0.25% above £100,000. On top come the ETFs' own fund costs, 0.14% to 0.39% a year depending on the style, and a market spread J.P. Morgan estimates at 0.04%. Those two are taken inside the investments, so you won't see them as a separate charge.
The management fee is worked out daily on your portfolio's value and taken on the first working day of each month. Joining, withdrawing and holding a cash-only pot are free.
All-in, on the first £100,000: Fixed Allocation about 0.63% a year, Fully Managed 0.97%, Socially Responsible 1.02%, Thematic 1.04%, Smart Alpha 1.13% and Income 1.18%. On £10,000 that is about £63 a year in Fixed Allocation and £97 in Fully Managed. On £150,000 in managed styles, the management fee alone is £925 a year: 0.75% on £100,000 plus 0.35% on £50,000.
Other charges: moving your holdings to another provider as investments rather than cash (an in-specie transfer) costs £20 per line of stock, and the paid financial advice service costs £900 (Core), £1,350 (Enhanced) or £450 (Advice Review).
Cash: cash held inside an investment pot (ISA, Lifetime ISA, Junior ISA, GIA or pension) earns the Bank of England rate minus 0.75%, so 3.00% if the Bank rate were 3.75%, and nothing if the Bank rate is 0.75% or lower. Cash-only pots have earned nothing since 22 June 2026, and unallocated cash and cash waiting to be withdrawn or transferred earn nothing either. It isn't a place to keep savings.
The six-month fee waiver by invite
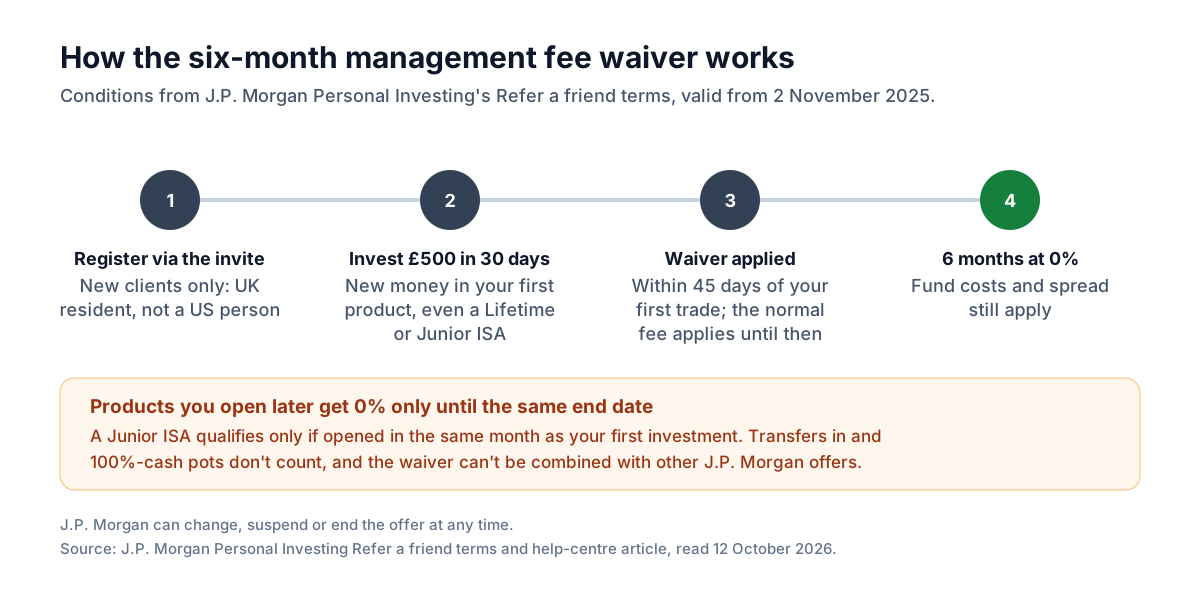
Request a private invite through the offer box on this page and register through the link it contains. The offer is six months without J.P. Morgan's management fee; it isn't cash. These are the conditions in J.P. Morgan Personal Investing's Refer a friend terms (valid from 2 November 2025) and its help-centre article on referrals.
You must be new to J.P. Morgan Personal Investing (or Nutmeg) and never have applied to join, be UK resident and not a US person, and meet the normal account rules. Open your account with the same email address you registered the invite with. Then invest at least £500 of new money in total within 30 days of your first investment. That £500 applies to your first product even if it's a Lifetime or Junior ISA, whose normal minimum is £100. Money transferred in from another ISA or pension provider doesn't count, and money in a 100%-cash pot doesn't qualify.
J.P. Morgan emails you when the 0% rate is applied, which can take up to 45 days from your first investment; until then you pay the normal management fee. The 0% rate lasts six months and also covers any ISA, Lifetime ISA, pension or GIA you open in that time, but it ends on the same day for all of them, so later products get only what's left. A Junior ISA qualifies only if you open it in the same month as your first investment. Fund costs and the market spread still apply throughout. It can't be combined with any other J.P. Morgan Personal Investing offer, and J.P. Morgan can change, suspend or end it at any time.
Disclosure: the invite comes from GetQuids' own account, so when you qualify J.P. Morgan sends us an Amazon.co.uk gift card, worth £100 if your first product is a Stocks & Shares ISA, GIA or pension, or £50 if it's a Lifetime or Junior ISA. If the 0% rate hasn't appeared within 45 days of your first investment, contact support on 020 3598 1515 or at support@personalinvesting.jpmorgan.com.
What the waiver is worth
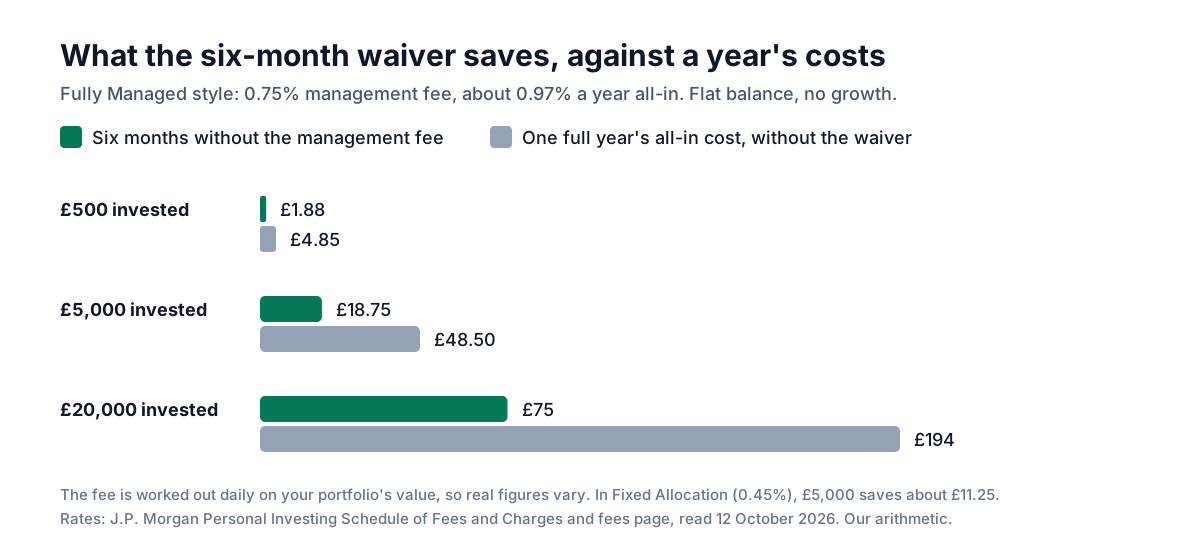
Not much. At 0.75%, six months without the management fee saves about £1.88 on £500, £18.75 on £5,000 and £75 on £20,000. In Fixed Allocation, at 0.45%, £5,000 saves about £11.25. These figures assume your balance stays flat; the fee is worked out daily on your portfolio's value, so the real saving moves with the market.
Set that against a full year's all-in cost in Fully Managed: about £4.85 on £500, £48.50 on £5,000 and £194 on £20,000. The waiver covers a little under two-fifths of your first year's costs and nothing after that. You still pay the fund costs and spread throughout, about £5.50 on £5,000 over the six months. Treat it as a small discount, and open an account only if you'd be happy paying the normal fees once the six months end.
Performance: what the track record tells you
J.P. Morgan publishes performance for each style and risk level after fees, updates it every quarter and compares it with competitors. It says the figures are simulated: real transactions across all customer portfolios, combined into one portfolio for each risk level. Your own result will depend on when you invested and what you paid in or took out.
Look at the figures for the style and risk level you would choose, over the longest period shown, rather than a headline number. Past performance doesn't tell you what will happen next, and any portfolio can be well down over a year or two, which is why J.P. Morgan suggests investing for at least three years.
Withdrawals, transfers and closing
You can take money out of the ISA, GIA or Lifetime ISA at any time, with no withdrawal fee. J.P. Morgan processes a withdrawal at its next trading cycle, using cash first and then selling investments, and pays your UK bank account once it has the money. Pension withdrawals take 3 to 7 business days to arrive. The Lifetime ISA charge, the Junior ISA's age rule and the pension age still apply.
If a withdrawal takes an ISA or GIA below £500, J.P. Morgan may sell its remaining investments and hold the money as cash until you top it up; any product that falls below £75 can be moved to cash too.
You can transfer an ISA or pension to another provider. The fee schedule lists no charge for moving it as cash; moving the holdings themselves (in specie) costs £20 per line of stock. If you're transferring a pension in, check first that you won't lose benefits or pay exit charges at your old provider.
You can cancel within 30 days of the agreement starting, or of a product being confirmed as open, with no cancellation fee, by secure message or email. You get back the market value on the day of the refund, less charges up to then, which can be less than you paid in. After that you can close a product or the whole account by giving 30 days' notice by secure message.
What users complain about
On 12 October 2026 the J.P. Morgan Personal Investing app was rated 4.7 from 19,923 ratings on the UK App Store (version 4.21.0, released 30 September 2026) and 3.2 from about 3,350 reviews on Google Play (last updated 26 September 2026). The Trustpilot profile, still at its nutmeg.com address, scored 4.0 from 2,719 reviews, 315 of them from the last 12 months, with 70% five-star and 15% one-star.
The low-rated reviews repeat a few themes: withdrawals held up by extra account or bank checks, slow chat and email support with chats closing after long waits, ISA and pension transfers taking longer than expected, login and two-step verification loops and bugs after updates in August 2026, identity checks failing at sign-up, delays handing over a Junior ISA at 18, fees that feel high next to DIY platforms, and long-standing customers who feel the service has slipped since J.P. Morgan took over.
Who should get it, and who should skip it
Consider it if you want your investing done for you in a ready-made ETF portfolio, if you'd like an ISA, Lifetime ISA, Junior ISA and pension in one app, if your employer's dealing rules make choosing your own shares awkward, or if you'll hold enough for the lower rate above £100,000 to matter. Fixed Allocation is the cheapest way in.
Skip it if you want to pick your own shares or funds, need a Cash ISA or a flexible ISA, want interest on cash you leave uninvested, or are comfortable buying a global tracker yourself; in that case compare the costs in our InvestEngine and Trading 212 reviews first. And don't open an account for the fee waiver alone: on £5,000 it is worth about £18.75.
FAQ
- Is J.P. Morgan Personal Investing the same as Nutmeg?
- Yes. Nutmeg was bought by JPMorganChase in 2021 and rebranded as J.P. Morgan Personal Investing on 3 November 2025. It is the same company, with the same products and managed portfolios; existing clients didn't need to do anything.
- Is it safe, or a scam?
- It isn't a scam: it is a long-running company that says it is FCA-authorised (register number 552016). Cash is held as client money at an approved bank and investments through a custodian, and the FSCS can pay up to £85,000 if the firm fails. None of that protects you from market falls, and JPMorgan Chase Bank doesn't stand behind the investments.
- Is Nutmeg shutting down?
- No. Only the name changed. The Nutmeg app and dashboard became J.P. Morgan Personal Investing on 3 November 2025, and nutmeg.com now redirects to the new site.
- How much does it cost?
- On the first £100,000, a management fee of 0.75% a year (0.45% for Fixed Allocation), plus fund costs of 0.14% to 0.39% and a spread of about 0.04%. All-in that is about 0.63% to 1.18% a year, or £63 to £118 on £10,000. Above £100,000 the management fee drops to 0.35% (0.25% for Fixed Allocation).
- Can I buy individual shares?
- No. You choose a style and risk level and the team picks the ETFs. J.P. Morgan promised a DIY platform for 2026, but on 12 October 2026 its website listed none.
- How do I withdraw my money, and how long does it take?
- Tell J.P. Morgan how much you want and, if you hold more than one product, which one to take it from. ISA, GIA and Lifetime ISA withdrawals are processed at the next trading cycle and paid once the money arrives; pension withdrawals take 3 to 7 business days. There is no withdrawal fee, but Lifetime ISA, Junior ISA and pension rules still apply, and the ISA isn't flexible.
- How do I get six months without management fees?
- Request a private invite through the offer box on this page, register through it and open your account with the same email address as a new client, then invest at least £500 of new money within 30 days of your first investment. The 0% rate is applied within 45 days of your first trade and lasts six months; fund costs and spread still apply.
- Does it pay interest on cash?
- Cash held inside an investment pot (ISA, Lifetime ISA, Junior ISA, GIA or pension) earns the Bank of England rate minus 0.75%. Cash-only pots (since 22 June 2026), unallocated cash and cash in transit earn nothing.