AJ Bell Review UK: What It Really Costs, and Is the £100 Voucher Worth It?
AJ Bell's SIPP, Stocks and shares ISA, Lifetime ISA and Dealing account reviewed: the charges at different pot sizes, interest on cash, how your money is protected, the £100 Amazon voucher for £10,000, the catches and who should skip it.
Last updated 12 October 2026
Best for
Buy-and-hold investors putting in £10,000 or more, mostly in shares, ETFs or investment trusts where AJ Bell caps its charge, who want an ISA and a SIPP in one place and won't need the money for at least a year.
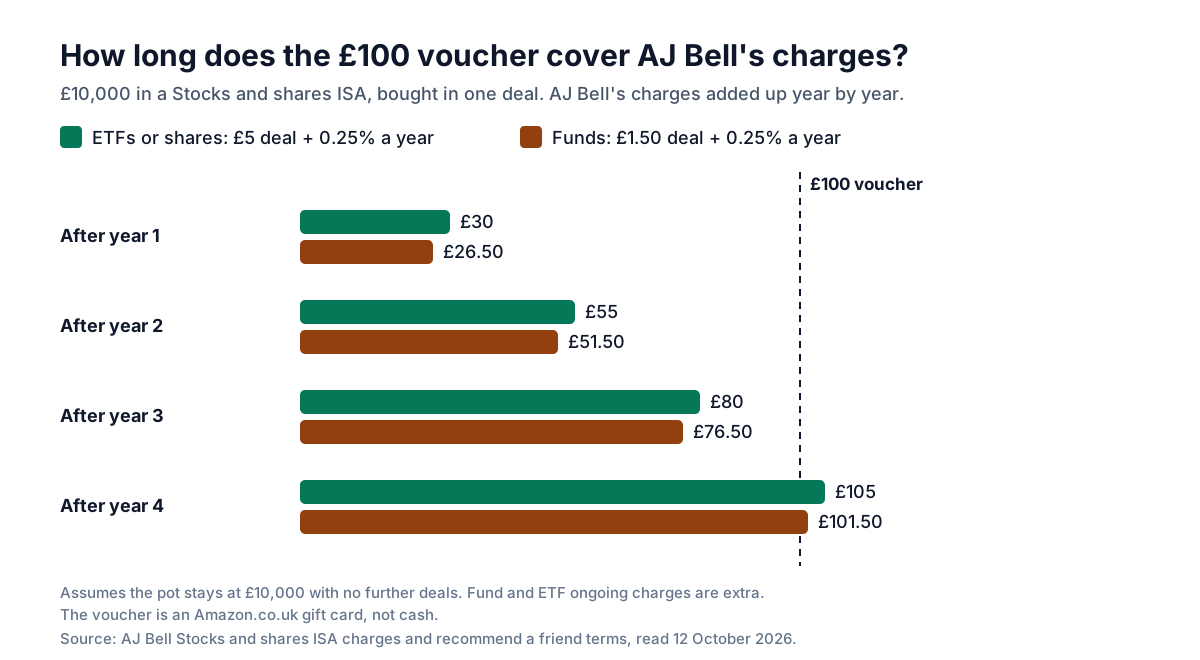
AJ Bell is good value for share-based pots and less so for big fund portfolios. Its 0.25% account charge is capped at £42 a year for shares, ETFs and investment trusts in an ISA (reached at £16,800) and £120 in a SIPP (reached at £48,000), but funds pay 0.25% with no cap until £250,000, so £100,000 in funds costs £250 a year. The £100 Amazon voucher is a fair bonus if you were going to invest £10,000 anyway: on £10,000 of ETFs in an ISA it covers more than three years of AJ Bell's own charges. It isn't a reason to move money on its own. It's a gift card rather than cash, the £10,000 has to arrive within 120 days and still be there when the voucher is issued, and AJ Bell can reclaim it if you withdraw or transfer out more than 75% within 12 months.
Pros
- Shares, ETFs and investment trusts cost at most £3.50 a month to hold in an ISA, Lifetime ISA or Dealing account, and £10 a month in a SIPP
- Free regular investing from £25 a month, and £1.50 one-off fund deals
- SIPP, Stocks and shares ISA, Lifetime ISA and Dealing account under one login, with UK and international shares, funds, ETFs, investment trusts, gilts and bonds
- Interest on uninvested cash: 2.05% AER in a SIPP (up to £100,000) and 1.75% in an ISA or Lifetime ISA
- No charge to transfer in, withdraw or leave, and up to £500 towards your old provider's exit fees on transfers of £20,000 or more
- Rated 4.7 from 23,314 ratings on the App Store and 4.9 from 17,377 reviews on Trustpilot
Watch-outs
- Funds are charged 0.25% with no cap below £250,000: £250 a year on £100,000
- £5 per online share deal (£3.50 after a month with 10 or more), £25 by phone, and 0.75% FX on the first £10,000 of a foreign deal
- The voucher needs £10,000 within 120 days, still there when it's issued, and AJ Bell can reclaim it within 12 months if you take out or transfer away more than 75%
- The reward is an Amazon.co.uk gift card with no cash alternative, and SIPP tax relief and the Lifetime ISA bonus don't count towards the £10,000
- Dealing account cash earns 0.75% on the first £2,000 and nothing above that
- App reviewers report a dated interface and login problems; Trustpilot complaints include slow transfers and missed callbacks
Current related offer
AJ Bell offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
AJ Bell
Request an invite through this page. If you have never been an AJ Bell customer and get £10,000 in total into eligible accounts within 120 days of your first account application, you get a £100 Amazon.co.uk gift card by email 30 days after funding, as long as at least £10,000 is still held. AJ Bell can reclaim it within 12 months if withdrawals or transfers cut your account value by more than 75%.
Requirement: £10,000 total eligible funding within 120 days of the first account application; £10,000 still held when the voucher is issued
Medium120 days to fund from your first applicationPayout Gift card by email 30 days after qualifying funding, if £10,000 is still held
Verified 12 October 2026
Full claim instructions are on the AJ Bell offer page.
What AJ Bell is and how your money is protected
AJ Bell is a UK investment platform based at Salford Quays in Manchester. AJ Bell Securities Limited (FCA number 155593), a member of the London Stock Exchange, handles dealing and custody and is the manager of the ISA and Lifetime ISA; AJ Bell Management Limited (FCA number 211468) administers the SIPP. AJ Bell says it is listed on the FTSE 250 and looks after £121.5bn for 762,000 customers. Those FCA numbers come from AJ Bell's own regulatory page and terms, so check them on the FCA register before you send money.
Cash in an ISA or Dealing account sits in trust accounts at UK-regulated banks, and investments are held by AJ Bell's nominee company or an authorised custodian, ring-fenced from AJ Bell's own money and reconciled daily. Pension money and investments are held under the pension scheme's trust. If AJ Bell failed, the Financial Services Compensation Scheme (FSCS) covers up to £85,000 per person for investments; for cash deposits, the FSCS limit is £120,000 per person, per bank. It doesn't protect you from your investments falling in value.
AJ Bell doesn't give advice, and it warns that scammers pose as senior AJ Bell staff on WhatsApp offering advice. It says it never contacts customers that way.
The accounts, and which ones count for the voucher
Four accounts count towards the referral: the SIPP (a self-invested personal pension), the Stocks and shares ISA, the Lifetime ISA and the Dealing account (a general investment account with no tax wrapper). You can open more than one and split the £10,000 between them, for example £6,000 in a SIPP and £4,000 in an ISA.
The Stocks and shares ISA uses your £20,000 ISA allowance for 2026/27. A Lifetime ISA has to be opened before you turn 40 and takes up to £4,000 a year, with a 25% government bonus of up to £1,000; withdrawals the rules don't allow carry a 25% government charge. On its own, a Lifetime ISA can't reach £10,000 in one tax year unless you transfer in an existing Lifetime ISA, and the bonus doesn't count towards the £10,000.
ISAs, Lifetime ISAs and Dealing accounts aren't open to US or Canadian citizens or tax residents, and the SIPP isn't open to Canadian citizens or tax residents. Tax relief that AJ Bell claims and adds to a SIPP doesn't count towards the £10,000, so you need £10,000 of your own payments or transfers. A SIPP is a pension: the money stays there until pension rules let you take it.
Not eligible for the voucher: the Ready-made pension (a managed pension with an all-in charge of 0.35% a year), the Cash savings hub, Junior ISAs and Junior SIPPs.
AJ Bell also runs Dodl, a separate app charging 0.15% a year per account with a £1 monthly minimum. Dodl accounts aren't on the eligible list, and money transferred from Dodl or AJ Bell Investcentre doesn't count. The terms exclude anyone who is or has been an AJ Bell customer, but they don't say whether a Dodl or Investcentre account makes you one, so ask AJ Bell first if you hold either.
What you can invest in, and what's missing
AJ Bell splits investments into two groups, and the split decides what you pay. 'Shares' covers UK and international shares, ETFs, investment trusts, gilts and bonds, and gets the capped account charge. 'Funds' covers unit trusts, OEICs and structured products, and is charged 0.25% without a cap until £250,000. If you're choosing between a tracker fund and an ETF following the same index, the ETF is cheaper to hold here once the pot passes £16,800 in an ISA.
Every fund and ETF also has its own ongoing charge (OCF), which the fund manager takes inside the price. It isn't part of AJ Bell's charge, so check it on each investment's page before you buy.
Regular investing puts £25 or more a month into selected investments with no dealing charge. App reviewers say you can't buy fractional shares or set stop-losses in the app, that some markets don't show live prices, and that some trades and funds have to be placed on the website or by phone.
Account charges at different pot sizes
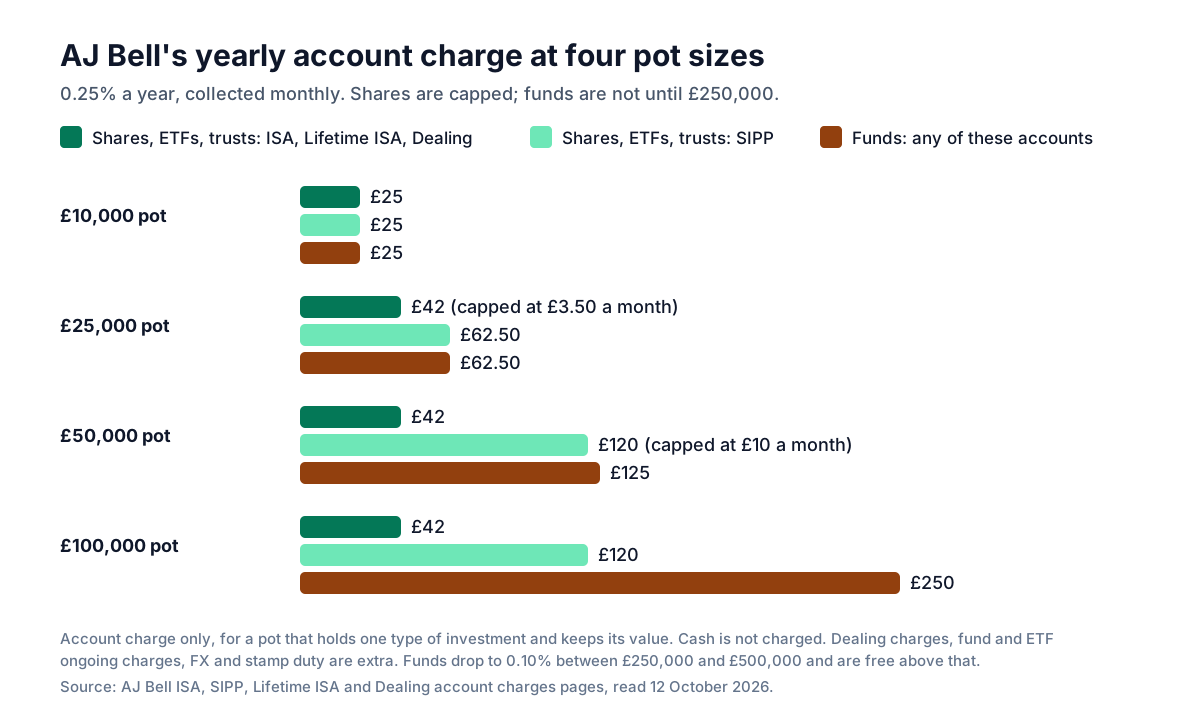
AJ Bell's account charge is 0.25% a year, worked out on your holdings' value at the end of each month and collected monthly. Cash isn't charged.
For shares, ETFs, investment trusts, gilts and bonds the charge is capped at £3.50 a month (£42 a year) in an ISA, Lifetime ISA or Dealing account, which you reach at £16,800, and at £10 a month (£120 a year) in a SIPP, which you reach at £48,000. Funds have no cap: 0.25% on the first £250,000, 0.10% on the next £250,000 and nothing above £500,000. In a Lifetime ISA, funds are charged 0.25%.
So what you hold matters as much as how much. £100,000 of ETFs in a SIPP costs £120 a year; the same amount in funds costs £250. AJ Bell's own example: an ISA worth £30,200, with £12,000 in shares, £18,000 in funds and £200 in cash, pays £6.25 a month.
Dealing, foreign exchange and interest on cash
Online share deals cost £5, or £3.50 in any month after you placed 10 or more share deals in the previous month, counted across your accounts. Fund deals are £1.50, regular investing is free, deals by phone are £25 and dividend reinvestment is £1.50 a time. Buying UK shares adds 0.5% stamp duty, and UK share deals over £10,000 carry a £1.50 PTM levy.
International shares and foreign-currency funds carry an FX charge on each deal: 0.75% on the first £10,000, 0.50% on the next £10,000 and 0.25% above £20,000, and some markets add their own taxes or levies. Converting dividends costs 0.5%. A £1,000 purchase of US shares therefore costs £5 to deal plus £7.50 in FX.
Interest on cash, as AER, since 1 February 2026: SIPP 2.05% up to £100,000 and 2.40% above (2.65% and 3.15% once you're in drawdown); ISA and Lifetime ISA 1.75% on all cash; Dealing account 0.75% on the first £2,000 and nothing above that. It's paid quarterly. £500 left uninvested in an ISA earns about £8.75 a year. AJ Bell says it keeps part of the interest banks pay on customer cash and uses it to keep its charges down.
The £100 Amazon voucher: how the referral works
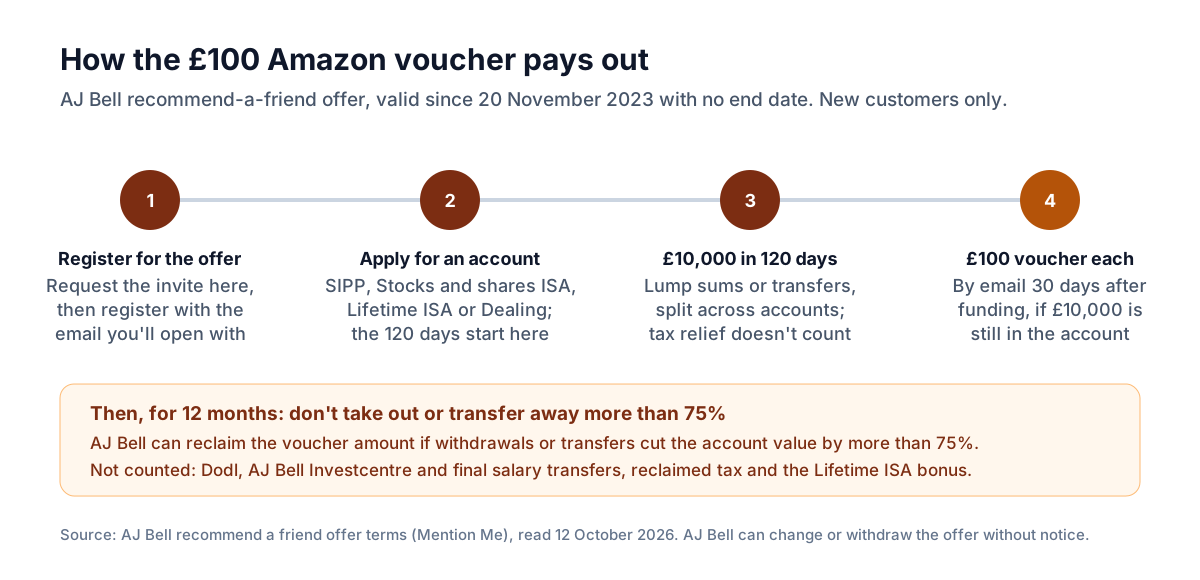
Request an invite through the offer box on this page, then register for the offer with the email address you'll open your AJ Bell account with; it has to be different from the referrer's. Open a SIPP, Stocks and shares ISA, Lifetime ISA or Dealing account, and make sure AJ Bell receives £10,000 or more in total within 120 days of your application for the first new account. Lump sums and transfers both count, split across accounts however you like.
You and the person who referred you then each get a £100 Amazon.co.uk voucher by email, 30 days after the £10,000 arrives, as long as the funding hasn't been withdrawn or cancelled and the account still holds at least £10,000 when the voucher is issued.
You must be 18 or over, UK resident when the voucher is redeemed, and never have been an AJ Bell customer. Transfers from final salary (defined benefit) pensions, AJ Bell Investcentre and Dodl don't count, and neither does tax AJ Bell reclaims for you or the Lifetime ISA bonus. If more than one person refers you, only the first referral counts. The scheme runs on Mention Me, whose terms say referrers should only invite people they know personally. AJ Bell employees and their families can't take part.
For 12 months, AJ Bell can reclaim the voucher amount if withdrawals or transfers reduce your account value by more than 75%. On a £10,000 account, that means taking out or moving away more than £7,500. The wording covers withdrawals and transfers, not market falls. There's no cash alternative, and Amazon's gift card terms apply.
The referral can be used alongside other AJ Bell offers only where their terms allow it, through separate transactions and not with the same money. Claiming it also rules you out of AJ Bell's Great Run Adidas gift card promotion, whose terms exclude anyone who claims the Amazon offer. AJ Bell can change, suspend or withdraw the referral offer without notice, even retrospectively, and can exclude anyone it believes is abusing it. The current terms have applied since 20 November 2023 and give no end date.
What the voucher is worth
An Amazon.co.uk gift card is worth its face value only if you'd spend that much at Amazon anyway; it isn't cash. A more useful question is how much of AJ Bell's charges it covers. Put £10,000 into ETFs in a Stocks and shares ISA in one deal and, if the value stays at £10,000, you pay £25 a year plus the £5 deal: £30 in year one and £25 a year after that. The voucher covers those charges for more than three years. The same £10,000 in funds costs £26.50 in year one (£25 plus a £1.50 deal), with a similar result, before each fund's own ongoing charge.
The voucher is paid once; the charges repeat. In a SIPP, shares stop costing more at £48,000 (£120 a year), while a £100,000 fund pot costs £250 a year, every year.
So the voucher is a reason to pick AJ Bell over a similar platform, not a reason to move £10,000 out of a cheaper one. Exit fees and higher ongoing charges can outweigh £100 within a few years.
Transfers in and out
AJ Bell doesn't charge to transfer in. If your old provider charges an exit fee on a SIPP, ISA or Dealing account worth £20,000 or more, AJ Bell pays up to £35 per investment moved and up to £100 of general exit fees, with a maximum of £500 per person. You claim by sending your old provider's fee evidence to transferoffer@ajbell.co.uk, and AJ Bell pays within 28 days of a valid claim once the transfer is complete.
The referral terms say the same money can't qualify for more than one offer. They don't say whether that stops one transfer counting towards the £10,000 and the exit-fee refund, so ask AJ Bell before you rely on both.
Leaving is free too: AJ Bell charges no exit or withdrawal fee, and outside a SIPP it makes withdrawals and transfers out within 20 business days of your instruction.
Slow transfers are a recurring complaint on Trustpilot, with reports of ISA and SIPP transfers taking weeks or months. If you're working to the 120-day deadline, start early: it runs from your first application, not from when the transfer arrives.
What users complain about
On 12 October 2026 the AJ Bell app was rated 4.7 from 23,314 ratings on the UK App Store (version 5.1.0, released 5 September 2026) and 4.6 from about 3,520 reviews on Google Play. AJ Bell scored 4.9 from 17,377 reviews on Trustpilot, with 88% five-star and 3% one-star; AJ Bell invites its customers to leave Trustpilot reviews.
The low-rated app reviews from the past year repeat a few themes: a dated, clunky interface (some saw the September 2026 rebrand as cosmetic), login, Face ID and two-factor problems, trades or funds that can only be placed on the website or by phone, weak performance views, and fees that feel high. Single reviews also mention no fractional shares and no stop-losses.
On Trustpilot, the one- and two-star reviews mention slow ISA and SIPP transfers, missed callbacks and unanswered messages, and payments and pension contributions taking a while to show; one reviewer objected to the uncapped charge on funds. We saw no complaints about referral vouchers not arriving.
If AJ Bell doesn't resolve a complaint, you may be able to take it to the Financial Ombudsman Service, or to the Pensions Ombudsman for a SIPP.
Opening, cancelling and closing
You need to be 18 or over and UK resident for tax when you apply, and you must tell AJ Bell if that changes; it can ask you to close an account you're no longer eligible for. AJ Bell checks your identity through credit reference agencies; its terms say the check may show on your credit history but won't affect your credit score. Opening is free. Your first payment must be at least £250 into an ISA or Dealing account and £500 into a SIPP, or you can start with a Direct Debit from £25 a month.
You can cancel within 30 days of AJ Bell confirming your account is open, or that a transfer has arrived. If you do, you pay any dealing charges and investments may be sold for less than you paid. In a SIPP, placing a buy order within those 30 days ends your right to cancel. Cancelled funding also loses the voucher.
To close an account, transfer it out or withdraw everything. Keep the 12-month reclaim in mind: emptying the account within a year of the voucher can cost you its value.
Who should use it, and who should skip it
Consider it if you're putting £10,000 or more into an ISA, a SIPP or both, mostly in ETFs, investment trusts or shares where the charge is capped, if you want a pension and an ISA in one place with interest on cash, and if you'll leave the money there for at least a year. Larger share-based SIPPs are where the £120 cap does the most work.
Skip it, or think twice, if most of a large pot is in funds, where the uncapped 0.25% adds up; if you trade small amounts often, as £5 on a £200 purchase is 2.5%; if you may need the money back within a year; if you have been an AJ Bell customer before; or if you want fractional shares and a slicker app.
FAQ
- Is AJ Bell safe?
- AJ Bell Securities Limited and AJ Bell Management Limited are authorised by the FCA, cash sits in trust accounts at UK banks and investments are ring-fenced in a nominee company. If AJ Bell failed, the FSCS covers up to £85,000 per person for investments. Your investments can still fall in value.
- How much does AJ Bell charge?
- 0.25% a year on what you hold, collected monthly. Shares, ETFs and investment trusts are capped at £3.50 a month in an ISA or Dealing account and £10 a month in a SIPP; funds have no cap until £250,000. Deals cost £5 for shares and £1.50 for funds, and regular investing is free.
- How do I get the £100 Amazon voucher?
- Request an invite through the offer box on this page, register with the email you'll open the account with, open an eligible account and get £10,000 in within 120 days of your first application. The voucher arrives by email 30 days after funding if £10,000 is still in the account.
- Does SIPP tax relief count towards the £10,000?
- No. Tax AJ Bell reclaims for you and the Lifetime ISA government bonus don't count, so the £10,000 has to be your own payments or transfers.
- Can I take the money out after I get the voucher?
- You can, but AJ Bell can reclaim the voucher amount within 12 months if withdrawals or transfers cut your account value by more than 75%. On £10,000, that means more than £7,500.
- I have a Dodl account. Can I still get the voucher?
- The terms exclude existing and former AJ Bell customers and money transferred from Dodl, but don't say whether a Dodl account makes you an AJ Bell customer. Ask AJ Bell before you apply.
- Can I get the voucher and the transfer exit-fee refund?
- The referral can be combined with other AJ Bell offers only through separate transactions using different money. Whether one transfer can count for both isn't spelled out, so check with AJ Bell first.
- Does opening an account affect my credit score?
- AJ Bell's terms say its identity check may appear on your credit history but won't affect your credit score.