Zopa Biscuit Review: Is the 2.75% Boost or the 3% Cashback Worth More?
Zopa's Biscuit current account reviewed: the 1% base rate, whether the 2.75% interest boost or 3% cashback pays more, the free Caffè Nero drink, the £20 referral, fees abroad, what it doesn't do, what customers complain about and how to open or close it.
Last updated 12 October 2026
Best for
People who want a no-fee second account that pays something back: on the balance if they keep more than about £3,100 in it, or as cashback on £150 a month of bills or eating out if they keep less.
A good free second account, not yet a bank to move everything to. Everyone gets 1% on the whole balance and a free Caffè Nero drink a month; then pick the 2.75% boost if you'd keep more than about £3,100 there on average, or 3% cashback (up to £54 a year) if you'd keep less and fill the £150 a month. On £5,000 the boost is worth about £137.50 a year against £104 from 1% interest plus full cashback. Opening it through our invite link adds a one-off £20, if you've never had a Zopa product. Against it: the Regular Saver has closed, you can't switch in with CASS yet, there are no cash deposits or overdraft, and recent app reviews complain about the August redesign and frozen accounts.
Pros
- 1% AER variable on the whole balance with no cap, or 2.75% AER if you choose the interest boost
- Or 3% cashback on up to £150 a month of Direct Debits or eating out: up to £54 a year, paid automatically
- A free barista-made Caffè Nero drink every month, whichever benefit you choose
- No monthly fee, and no Zopa fee on card spending abroad at Visa's exchange rate
- A UK bank account with FSCS protection up to £120,000, opened with a soft credit check
- £20 each for opening a Biscuit account through our invite link, with no deposit asked for
Watch-outs
- One benefit at a time, and a change only takes effect the following month
- No CASS switch into Biscuit yet: Direct Debits, standing orders and salary move by hand
- No cash, cheque or CHAPS payments in, no joint account and no arranged overdraft
- The Regular Saver closed to new pots on 22 September 2026
- 2% on cash withdrawn abroad above £200 in a rolling 30 days, and a £400 daily cash limit
- Recent app reviews complain about the August 2026 redesign and accounts frozen without explanation
Current related offer
Zopa Biscuit offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Zopa Biscuit
Open a Biscuit bank account through GetQuids' Zopa invite link and you get £20, provided you've never used the Zopa app or held a Zopa product. Enter your mobile number on the invite page first and finish within 30 days; the live invite terms control.
Requirement: None on this invite: open a Biscuit account through the link within 30 days of entering your mobile number
Easy5-10 minutes; opening can take up to 2 working daysPayout Within 30 days of qualifying
Verified 12 October 2026
Full claim instructions are on the Zopa Biscuit offer page.
Related comparisons
Chase UK vs Zopa Biscuit Referral Offers
Chase UK vs Zopa Biscuit compared by reward, what you must do, app-bank setup and payout timing.
Read comparison →
Monzo vs Zopa Biscuit Referral Offers
Monzo vs Zopa Biscuit compared by app setup, referral requirement, reward certainty and deposit friction.
Read comparison →
What Biscuit is, and who runs it
Biscuit is the current account from Zopa Bank Limited, launched on 24 June 2025. Zopa says it is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority (firm reference 800542). You get a sort code, an account number and a Visa debit card, and you run the account from the Zopa app.
Money in Biscuit is protected by the Financial Services Compensation Scheme (FSCS) up to £120,000, but that limit is shared with everything else you hold at Zopa, including its savings accounts. If you already keep a large sum in Zopa savings, opening Biscuit doesn't add any protection.
There's no monthly fee and no application fee, and Zopa says it would give at least 60 days' notice before adding a new fee.
1% on everything, plus one benefit
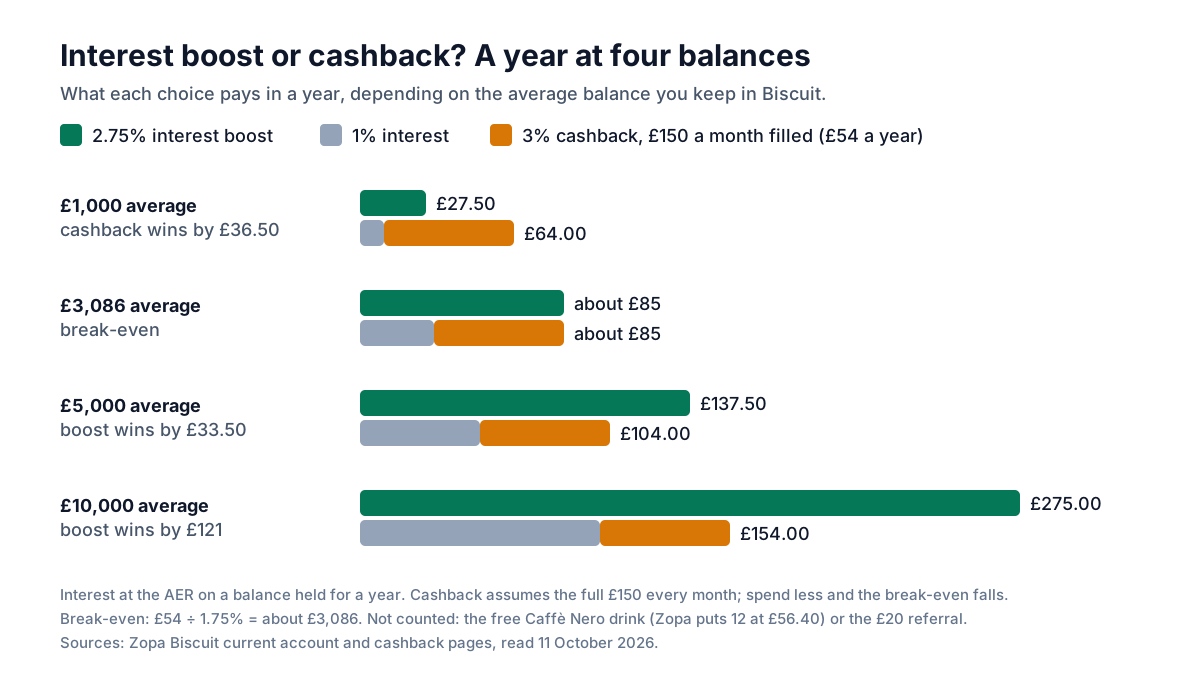
Every balance earns 1% AER variable, worked out daily and paid monthly, with no cap. On top, you choose one benefit in the app: an interest boost to 2.75% AER (2.72% gross) variable, which includes the 1% rather than adding to it; 3% cashback on up to £150 of Direct Debits a month; or 3% cashback on up to £150 a month at restaurants, takeaways and bakeries. Either cashback option is worth £4.50 a month, or £54 a year, at most.
You can change the benefit whenever you like, but there's a 24-hour lock after each change and the new benefit only starts the following month, so you can't flick between them to collect both. Interest you've already earned is kept when you switch.
Bills cashback counts Direct Debits paid from Biscuit; Zopa's examples are household bills, subscriptions and eligible credit card repayments. Cashback is paid into the account automatically once a month, with nothing to claim. Some older write-ups, and one Zopa help article, still mention 2% cashback; Zopa's product page and fee information say 3%.
Whichever benefit you pick, you also get one free barista-made hot or cold drink from Caffè Nero each month. You claim it in the Zopa app (Spend, then Benefits), and it arrives as a voucher in the Caffè Nero app, which you need to download and set up first. The voucher expires after 30 days, so claim it when you're about to order.
Interest boost or cashback: what it's worth
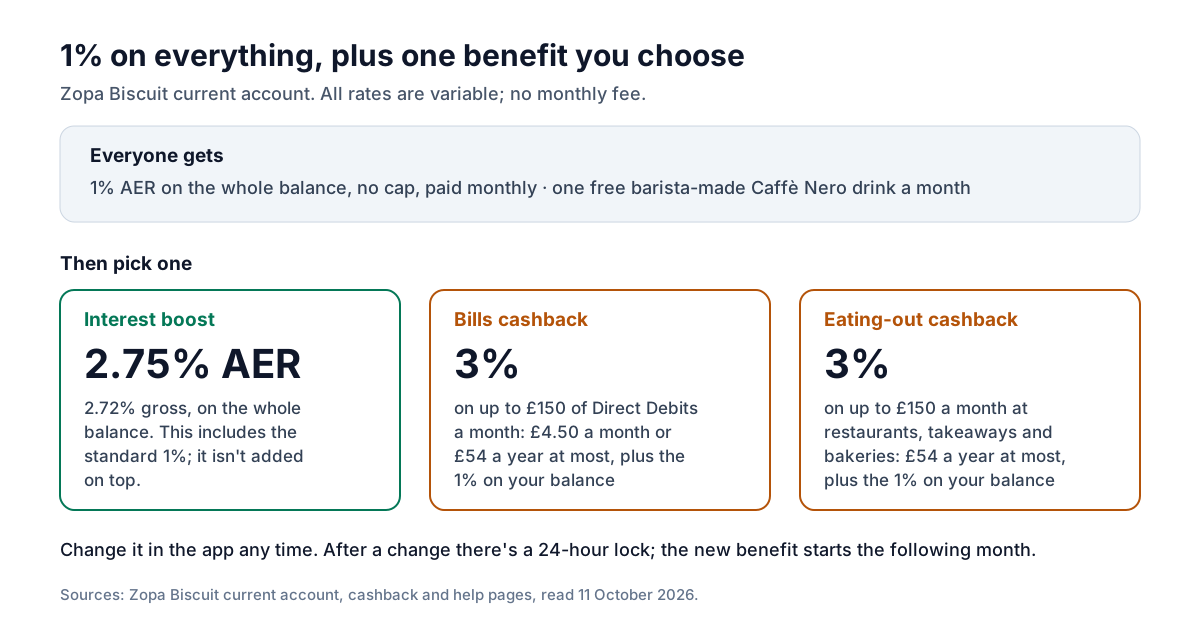
The boost adds 1.75 percentage points to the 1% you get anyway; cashback adds at most £54 a year. They're worth the same at an average balance of about £3,100 (£54 ÷ 1.75%). Below that, cashback pays more, as long as you'd really put £150 a month of Direct Debits or eating out through Biscuit. Above it, the boost wins, and the gap grows with the balance.
On £5,000 kept there all year, the boost earns about £137.50, against £104 from 1% interest plus full cashback. Zopa's own example says Biscuit is worth up to £154.20 a year: £54 of cashback, £43.80 of interest on a £4,380 average balance at 1%, and £56.40 for twelve Nero drinks at an average £4.70. On that same balance the boost would earn about £120 of interest instead of £97.80 from interest plus cashback, so run your own numbers before you pick.
The free drink is only worth something if you'd buy a coffee anyway, and the £20 for opening through our invite is a one-off. Interest is paid without tax taken off, so if your total savings interest goes over your Personal Savings Allowance (£1,000 for basic-rate taxpayers, £500 for higher-rate and nothing for additional-rate), you owe tax on the rest.
The £20 referral
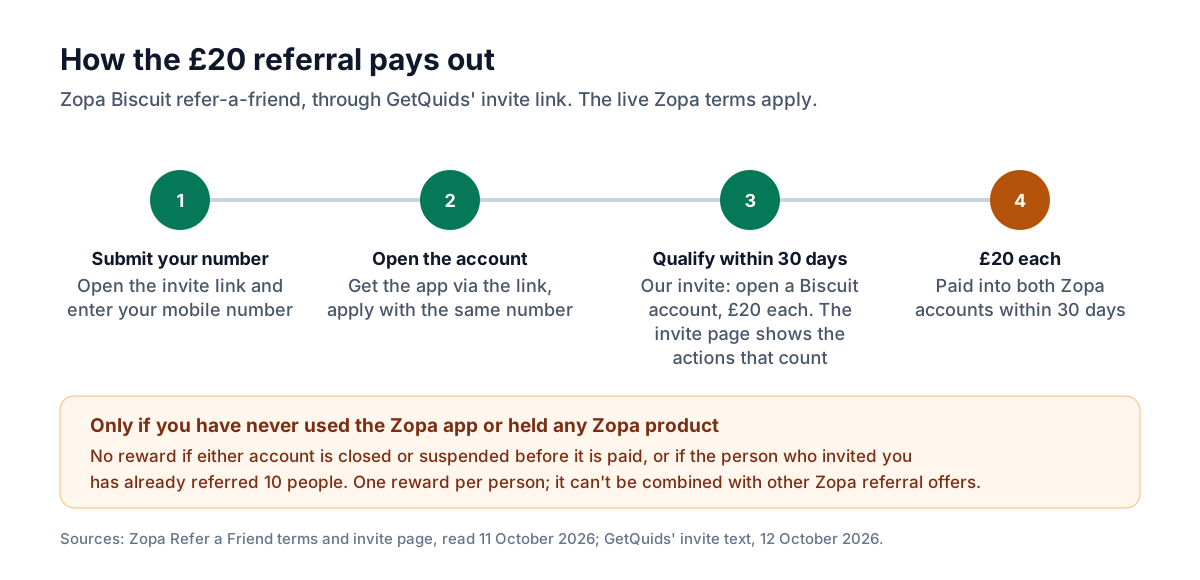
Our invite reads: "Use my referral link to open a Biscuit bank account and we'll both earn £20. T&Cs apply." So when you open a Biscuit account through the invite link on this page, you get £20, and so do we, paid into both Zopa accounts within 30 days of qualifying. The live invite terms control. The order matters: open the link, enter the mobile number you'll open the account with, then download the Zopa app through the same link and apply using that number. You have 30 days from submitting the number to finish.
Zopa's terms allow other versions of the invite, such as opening the account and making 1, 3 or 7 card payments, and say the actions shown on the invite page when you use the link are the ones that count. So read the invite page when you open our link, and take a screenshot.
You won't qualify if you have ever used the Zopa app or held any Zopa product, or if the person who invited you has already referred 10 people. You get one reward only, it can't be combined with other Zopa refer-a-friend offers such as Smart Saver's, and you lose it if your account is closed or suspended before it's paid. Zopa can withhold it for suspicious behaviour, replace it with a different reward, or change or end the scheme at any time; no end date is published. Turn on notifications in the app, which is how Zopa says it keeps you posted on the reward.
Disclosure: the invite link on this page is GetQuids' own, so we get £20 too when you qualify.
The Regular Saver has closed
Biscuit launched with a Regular Saver pot that took up to £300 a month for six months, and older reviews still lead with it. Zopa stopped opening new Regular Saver pots on 22 September 2026.
If you already have one, it runs to the end of its six months. If you close your Biscuit account before then, it converts to an Access pot and can't be reopened. Don't open Biscuit for the saver.
Spending and cash abroad
Card payments abroad are converted at Visa's exchange rate with nothing added by Zopa, and you don't need to tell Zopa before you travel. When a card machine offers to charge you in pounds, choose the local currency, so Visa sets the rate rather than the merchant.
Cash machines outside the UK are free up to £200 in a rolling 30 days. After that Zopa charges 2% on the amount over £200, not on the whole withdrawal. Zopa's own example: £220, then £50, then £50 over three days costs £0.40, £1 and £1, so £2.40 on £320. The ATM's owner may add its own charge, and you can take out at most £400 in cash in any 24 hours. Zopa calls this 2% the only fee that can apply to the account.
What Biscuit doesn't do
No CASS switch in, yet. Zopa has joined the Current Account Switch Service, but for now it only works for leaving Zopa. To move to Biscuit you update each Direct Debit, standing order and your salary details yourself through the Zopa app (Zopa's switching page has a checklist), and Zopa suggests keeping your old account open and in credit for a month or two. A Zopa article updated on 1 October 2026 says switching in through CASS is coming later in 2026.
No cash, cheque or CHAPS payments in, no joint account and no arranged overdraft. If the balance dips below zero, for example after an offline card payment, Zopa doesn't charge for it, but you must pay it back as soon as possible (Zopa can ask for the full amount at any time), and going overdrawn may hurt your credit score.
Fixed limits. Zopa says these can't be changed: £10,000 of spending in a rolling 24 hours and £30,000 in 7 days (Direct Debits excluded), £400 of cash a day, £500 a day on gambling, and £250,000 a day between Biscuit and your linked accounts. Payments Zopa identifies as crypto, including bank transfers and card payments to exchanges, are declined.
What customers complain about
On 11 October 2026 the Zopa app was rated 4.85 out of 5 from 73,043 ratings on the App Store and 4.6 from about 32,100 reviews on Google Play, with over a million downloads. Zopa's Trustpilot profile scored 4.6 from 38,463 reviews, 6% of them one star, but it covers Zopa's loans, cards and savings as well as Biscuit, and Trustpilot notes that Zopa hasn't invited reviews recently. Zopa replies to 98% of negative reviews.
App Store reviews from April to October 2026, and Trustpilot, repeat a few themes: the app redesign in August 2026 (harder navigation, Face ID asked twice, freezes and error messages, linked-account details and payments harder to find, pot boosts gone); accounts restricted or frozen without explanation, often after money comes in or goes out; slow or scripted support, chat history that isn't saved and promised callbacks that don't come; the Regular Saver's withdrawal and cashback that didn't match what people expected; no Cash ISA transfers in; and login outages.
The terms allow for the frozen accounts: Zopa normally gives at least 90 days' notice before closing an account, but can act straight away, sometimes without giving a reason, if it suspects fraud, crime or legal risk. Keep another account running until you're happy to rely on Biscuit.
Opening, cancelling and closing
You need to be 18 or over, live in the UK, be tax resident only in the UK (the Channel Islands and the Isle of Man don't count) and not be a US citizen. There's no minimum income. Zopa runs a soft credit check to confirm your identity; it says this doesn't affect your credit score, and your score doesn't decide whether you're approved.
You'll need a UK mobile number and an email address. In the Zopa app you create a Zopa login, apply for Biscuit and verify your identity with photo ID and a selfie, and Zopa also asks for proof of address, such as a utility bill or bank statement from the last three months or a UK, EU, EEA or Swiss driving licence, showing the address on your application. Zopa accepts a passport (not an emergency, temporary or diplomatic one), a driving licence (provisional included), or an internationally recognised national ID card or residence permit. It doesn't say the passport has to be British, which helps if you've just moved here, but you still need to meet the residency and tax rules above. You have seven days to upload the documents. Opening usually takes minutes but can take up to two working days.
You can cancel within 14 days of opening without penalty. To close the account later, bring the balance to £0 yourself (Zopa can't move the money for you), cancel recurring payments, make sure nothing is due in over the next three working days, then ask through live chat in the app. Or switch away through CASS: your new bank moves your payees, Direct Debits, standing orders and balance, and you need to allow at least seven working days. Closing Biscuit doesn't close your other Zopa products.
Who should get it, and who should skip it
Get it if you want a free second account that pays you on the balance: 1% on everything with no cap, the boost if you'd keep more than about £3,100 there, or cashback if you'd put £150 a month of bills or eating out through it. It also suits travellers who want card spending abroad without a Zopa fee, and coffee drinkers who pass a Caffè Nero.
Skip it if you've ever had a Zopa product and want the referral, if you need to pay in cash or cheques, want a joint account or an arranged overdraft, came for the Regular Saver, or want a one-step CASS switch today. And if you'd keep a large sum there, compare the boost with easy-access savings accounts, and remember the £120,000 FSCS limit covers all your Zopa deposits together.
FAQ
- Is Biscuit a proper bank account?
- Yes. It's a current account from Zopa Bank Limited with a sort code, account number and Visa debit card. Deposits are protected by the FSCS up to £120,000 in total across everything you hold at Zopa.
- Should I pick the 2.75% boost or cashback?
- The boost pays more if your average balance is above about £3,100; below that, cashback does, as long as you'd fill the £150 a month. On £5,000 the boost is worth about £137.50 a year against £104 from 1% interest plus full cashback.
- Can I still open the Regular Saver?
- No. Zopa stopped opening Regular Saver pots on 22 September 2026. Existing pots run to the end of their six months.
- How do I get the £20 referral?
- Open our invite link, enter your mobile number, download the Zopa app through the link and apply with the same number. Our invite pays £20 each for opening a Biscuit account: finish within 30 days of submitting the number, and check the invite page, as its live terms control. The £20 arrives within 30 days of qualifying.
- I already have a Zopa loan or savings account. Can I get the £20?
- No. The referral terms require that you have never used the Zopa app or held any Zopa product.
- Can I switch my old account to Biscuit with CASS?
- Not yet. CASS currently only works for leaving Zopa, and Zopa says switching in is coming later in 2026. For now you move Direct Debits, standing orders and your salary yourself.
- Is Biscuit free to use abroad?
- Card payments abroad use Visa's exchange rate with no Zopa fee. Cash machines outside the UK are free up to £200 in a rolling 30 days, then 2% on the amount over £200, and the machine's owner may charge too.
- Does applying affect my credit score?
- Zopa says it runs a soft credit check to confirm your identity, which doesn't affect your credit score.