
Zilch Review UK: Up to 5% Back, but What Does Paying Later Cost?
Zilch reviewed: how the Pay now and pay-later card works, the Up, Classic and X credit tiers, every fee including Auto Snooze, what the Rewards and the £5 referral are really worth, what users complain about and who should skip it.
Last updated 12 October 2026
Best for
UK shoppers who already buy from stores listed in the Zilch app, mostly pay in full with Pay now, and only split a purchase when it's fee-free and they can repay on time.
Zilch is two products in one app. Pay now is a free way to earn Rewards: up to 5% at stores listed in the app and 0.5% everywhere else, as long as you spend them at those listed stores within 12 months. Pay later is credit, and its cost depends on where you shop: fee-free at some partner stores, but £3 to £4.75 a purchase through Zilch Anywhere, and up to 1.8% of the price a month on Pay monthly, which adds £129.60 to a £600 purchase over a year. Take the £5 referral and use Pay now at shops you'd use anyway; treat the credit side as occasional, and keep money in your linked account on the due dates.
Pros
- Pay now has no fees and earns up to 5% in Rewards at stores listed in the app
- No interest and no late fees, even on a missed payment
- Pay over 6 weeks can be fee-free at stores in the app that offer it, and Zilch says it's covered by Section 75
- A soft credit check to apply, and on-time repayments are reported every month, which can help build a credit file
- Manual Snooze moves an instalment by 4 or 8 days for 75p or £1.50
- A virtual card that works anywhere Visa is accepted, online or by Tap and Pay, with no physical card needed
Watch-outs
- Through Zilch Anywhere, Pay over 6 weeks costs £3 to £4.75 a purchase and Pay monthly 1.8% of the full price every month
- Auto Snooze is on by default and charges £1 or £2 per instalment when a collection fails
- On the free plan, Rewards only work at stores listed in the app, and they expire after 12 months
- Pay now purchases have no Section 75 protection
- A missed payment can block the account, harm your credit file and, after about two months, go to a debt recovery agency
- Available credit only comes back once a whole purchase is repaid, and slow dispute handling is a common complaint
Current related offer
Zilch offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Zilch
Get approved and your card issued within 30 days of signing up through this link, add one small Tap and Pay purchase on Pay now to be safe, and Zilch adds £5 in Rewards within 10 working days. The value is in Pay now at stores you already use; the pay-later side is credit (representative APR 14.9% to 31.9% by tier), and Auto Snooze charges £1 or £2 per failed instalment.
Requirement: Verify your ID, get approved and receive your card within 30 days; the referral page also asks for a first Tap and Pay purchase
Easy5 minutes to sign up; approval and card issue within 30 daysPayout £5 in Rewards within 10 working days of completing the referral tasks
Verified 12 October 2026
Full claim instructions are on the Zilch offer page.
What Zilch is and how it works
Zilch is an app with a virtual Visa card you can pay with in two ways. Pay now takes the full amount from the UK debit card you link, straight away, with no fee, and earns Rewards; Zilch's terms call it a debit account. Pay later is credit: Pay over 6 weeks splits a purchase into four payments, and Pay monthly spreads it over 3, 6 or 12 months. You can find a store in the app and enable your card before paying, or use the card at shops that aren't in the app, online or in store with Tap and Pay, which Zilch calls Zilch Anywhere.
It isn't a bank account. You can't get paid into it, set up regular bill payments or send transfers, and there's no balance to top up: every payment and instalment is collected from your linked debit card.
Zilch Technology Limited (company 11488502, London) says it is authorised and regulated by the Financial Conduct Authority (firm reference 843421) and is also an authorised payment institution (1033706). You can check both numbers on the FCA register at register.fca.org.uk. Since 15 July 2026 the FCA has also regulated buy now, pay later lending more widely, which it calls Deferred Payment Credit, with rules on lending affordably and helping people who fall behind.
Protection depends on how you pay. Zilch says Pay over 6 weeks purchases are covered by Section 75 of the Consumer Credit Act, which makes the lender jointly liable with the shop, but only for single items priced over £100 and up to £30,000. Pay now counts as a debit transaction, so it isn't covered. Zilch blocks gambling and lottery merchants, and can block other merchants where it sees a lot of fraud.
Up, Classic or X: the three credit tiers
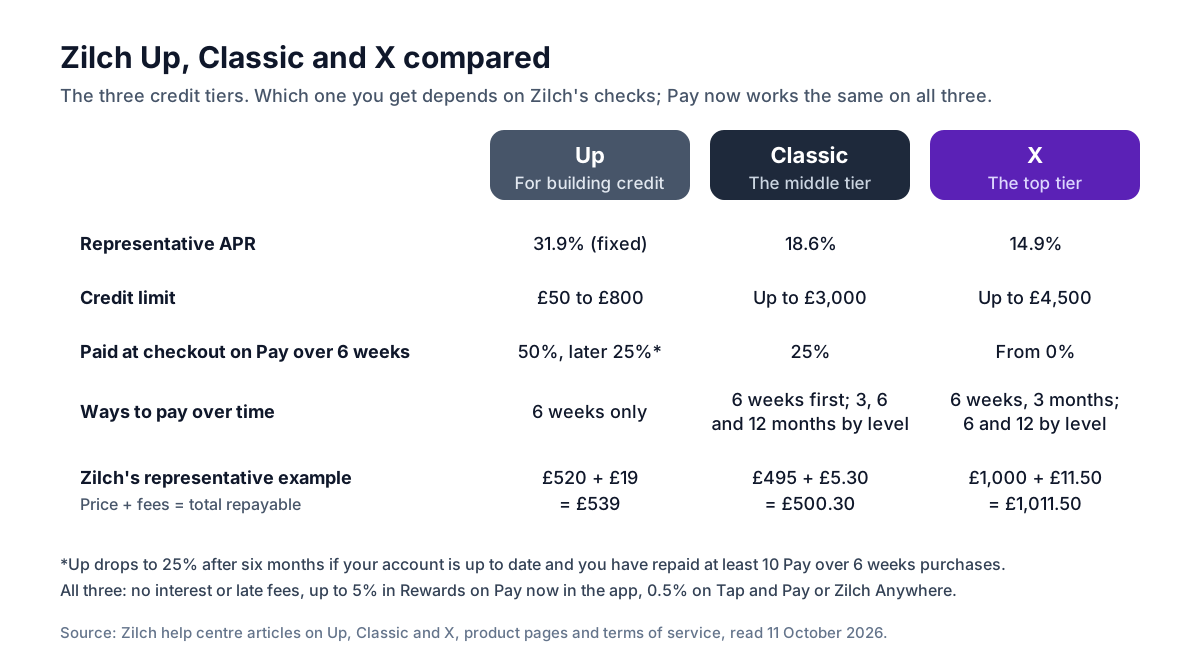
Which tier you get depends on Zilch's checks. Up is aimed at building or rebuilding credit: a limit of £50 to £800, a fixed 31.9% representative APR, and half of each Pay over 6 weeks purchase paid at checkout. That drops to 25% after six months, once you've repaid at least 10 Pay over 6 weeks purchases and your account is up to date. Classic gives up to £3,000 at 18.6% representative APR, with 25% upfront. X gives up to £4,500 at 14.9%, from 0% upfront.
Longer plans unlock in levels. On Classic you start with Pay over 6 weeks, then get Pay over 3 months, then 3, 6 and 12 months. On X you start with 6 weeks and 3 months, then add 6 and 12 months. Zilch's Up page lists only Pay over 6 weeks.
Your available credit only comes back when a whole purchase is paid off. Spend £100 and nothing returns after each instalment; the full £100 returns after the last one, so paying early frees it sooner. Zilch may raise your limit automatically if you pay on time or early (ask in the app if you'd rather it didn't), tasks in the app's Limit builder can raise it, and a missed payment can lower it. Boost lets you go over your available credit by paying the difference with the first instalment: £230 against £200 of available credit means an extra £30 at checkout.
How paying over 6 weeks or monthly works
Pay over 6 weeks splits a purchase of £10 or more into four payments: the first at checkout, then one every two weeks. On a £300 purchase with 25% upfront, that's £75 today and £75 at two, four and six weeks. With 50% upfront, it's £150 today and three payments of £50. Any fee is added to the first payment.
Pay monthly (3, 6 or 12 months) needs a purchase of at least £75 and Zilch's approval. You pay 0%, 25% or 50% at checkout depending on your plan and account history, then the rest in monthly payments on the same date each month, with the fee built in.
How you start the purchase matters. If you search for the store in the app and enable your card first, Zilch applies that store's fee and Rewards rate. If you just tap your phone or type in the card details, the higher Anywhere fees apply and the purchase follows your smart settings, which decide whether it goes through as Pay now or in instalments. Check them before you tap.
You can repay early at any time in the app, which frees up credit but doesn't reduce the fee. Instalments over £22 can also be paid straight from your bank with Pay by Bank instead of the linked debit card.
What paying later costs
Pay now has no fee. Paying later can cost nothing or quite a lot, depending on where and how you shop.
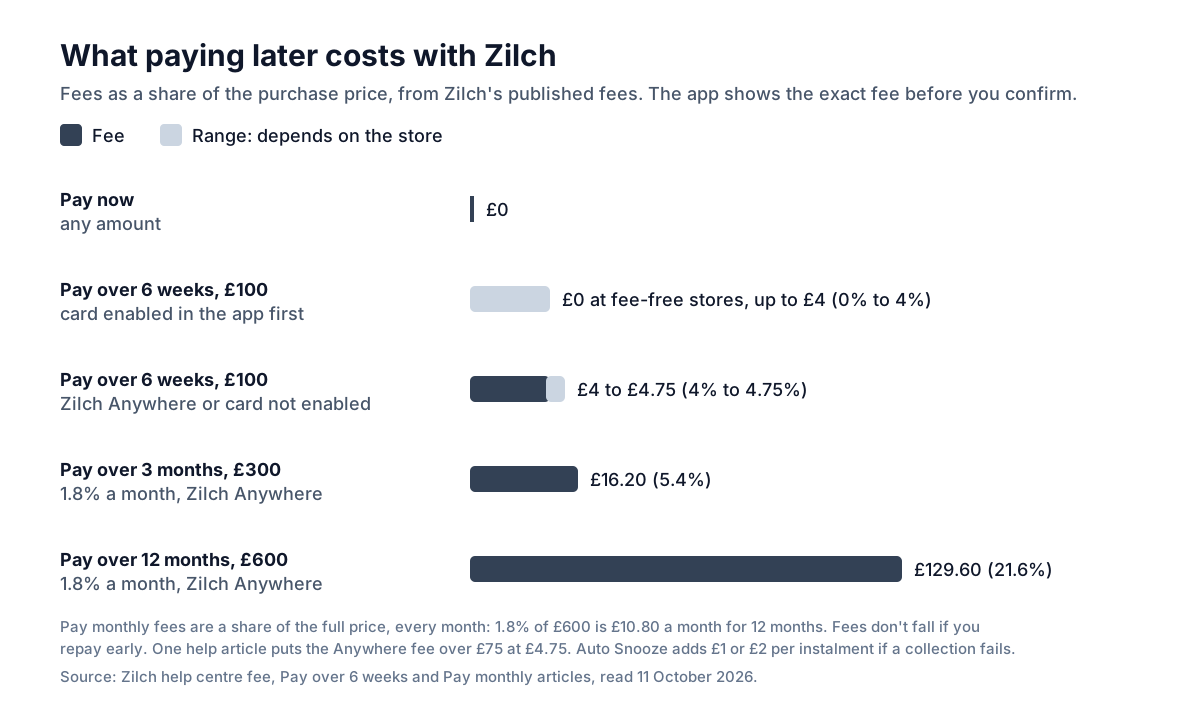
Pay over 6 weeks, card enabled in the app: £0 to £3, plus £1 on purchases over £75. Zilch says thousands of stores in the app are fee-free. Zilch Anywhere, or a purchase without enabling the card: £3 to £3.50 up to £75 and £4 to £4.50 above, according to Zilch's fee article updated on 2 September 2026. Zilch's own pages don't agree: its Pay over 6 weeks article says £3.75, or £4.75 over £75. The app shows the exact fee before you confirm, so go by that.
Pay monthly: 0% to 1.6% a month with the card enabled at a participating store, 1.8% a month otherwise. The fee is a share of the full purchase price, charged every month, not of the shrinking balance: Zilch's own example is 1.6% of £300, or £4.80 added to each monthly payment. At 1.8%, £300 over 3 months costs £16.20 in fees, and £600 over 12 months costs £129.60, more than a fifth of the price.
Fees don't fall if you repay early, and they're usually non-refundable, although Zilch says it may refund them if the shop cancels or can't complete the order. Other costs: a physical card is £4.99 unless you're on Plus, and Advance (below) has a £3 fee. Pay now in a foreign currency is converted at the card scheme's rate, shown in the app before you pay, and Zilch says it adds no other costs.
Missed payments, Snooze and Auto Snooze
Zilch doesn't charge late fees or interest on missed payments. The costs come in other ways.
Snooze: up to a day before a due date you can delay an instalment by 4 days for 75p (Pay over 6 weeks only) or by 8 days for £1.50, and some instalments can be snoozed free. Each instalment can be snoozed once, and never the first, which is paid at checkout.
Auto Snooze is switched on when you open the account. If an instalment isn't collected by the day after it's due, Zilch tries again; if that fails, it tries to collect £1 (a 4-day delay, Pay over 6 weeks only) or £2 (8 days) per instalment and moves the due date. By default, 6-week instalments move by 4 days and 3-month ones by 8. Zilch's Pay over 6 weeks article says it retries a failed payment 'but will never charge you extra', which isn't the case with Auto Snooze on. You can switch it off in the app; then there's no fee, but the instalment simply stays overdue. Manual Snooze does the same job for less if you act a day ahead.
If an instalment stays unpaid, Zilch may block your account until you've caught up, cut your limit, and the missed payment can harm your credit file. You can still pay it in the app for up to 60 days; after that Zilch may pass the debt to a debt recovery agency (CRS or Zinc), and you then pay through them. One help article says 60 days and another 70, so think of it as about two months. While you're behind you can't spend Rewards, and if you're more than 30 days overdue Zilch can use them against what you owe.
If you can see a payment coming that you can't make, contact Zilch before the due date. Citizens Advice and StepChange also give free help.
Rewards and the paid plans
Rewards are Zilch's points, and 1 Reward is worth 1p off a future purchase. On the free Standard plan, Pay now earns up to 5% when you find the store in the app and enable the card first, and 0.5% when you Tap and Pay or use Zilch Anywhere. Zilch only commits to the rate shown for two hours after you start a purchase. Pay now Rewards are added at checkout and taken back if the purchase is refunded.
Spending them has catches. On Standard you can only use Rewards at stores listed in the app. When you switch them on, your whole balance is applied, not part of it, and if that takes a purchase below £10 (or £75 on Pay monthly) the payment type changes or the purchase may be declined. Rewards can't be cashed out or transferred, and they expire 12 months after they're added.
Extra (£2.99 a month) lets you spend Rewards anywhere Visa is accepted, and adds Open Banking income checks, priority support and Advance. Zilch says it's rolling out gradually, so you may not be offered it. Plus (£4.99 a month) adds up to 6% on Pay now in the app (up to 1.5% elsewhere), Rewards on paying later of up to 1% (0.25% outside the app, paid only if every instalment is on time and you're still a member at the last payment), a tastecard membership that Zilch values at £79.99 a year, a free physical card, priority support and Advance.
Advance lends up to £100, or 20% of your income if that's less, up to seven days before payday, for a £3 fee taken with the repayment on payday. You can cancel a membership at any time, but fees aren't refunded, even for part of a month, and only selected customers get a free trial. If you took Plus's free physical card and cancel within 90 days, Zilch charges the £4.99 card fee. Zilch says availability varies by customer, so check what the app actually offers you.
What it's worth
For most people the value is in Pay now Rewards, so here are Zilch's advertised rates on the free Standard plan. The live rate for each store is in the app.
Spend £100 at a store in the app that pays 5% and you get 500 Rewards, or £5 off a later purchase at a listed store. The same £100 by Tap and Pay earns 50p. The £5 referral is another 500 Rewards on the same terms.
Paying later eats into that quickly. A single £100 purchase through Zilch Anywhere on Pay over 6 weeks costs £4 to £4.75, as much as the 5% Rewards on £80 to £95 of Pay now spending.
Plus adds one percentage point on Pay now (up to 6% instead of 5% in the app, 1.5% instead of 0.5% elsewhere), so at the top rates covering its £4.99 a month takes about £499 a month of Pay now spending before you count the tastecard. If you'd use a tastecard anyway, that may close the gap; the £79.99 is Zilch's own valuation.
In short: the referral and Pay now Rewards at shops you already use are the value. The credit side is where Zilch makes its money.
The referral bonus
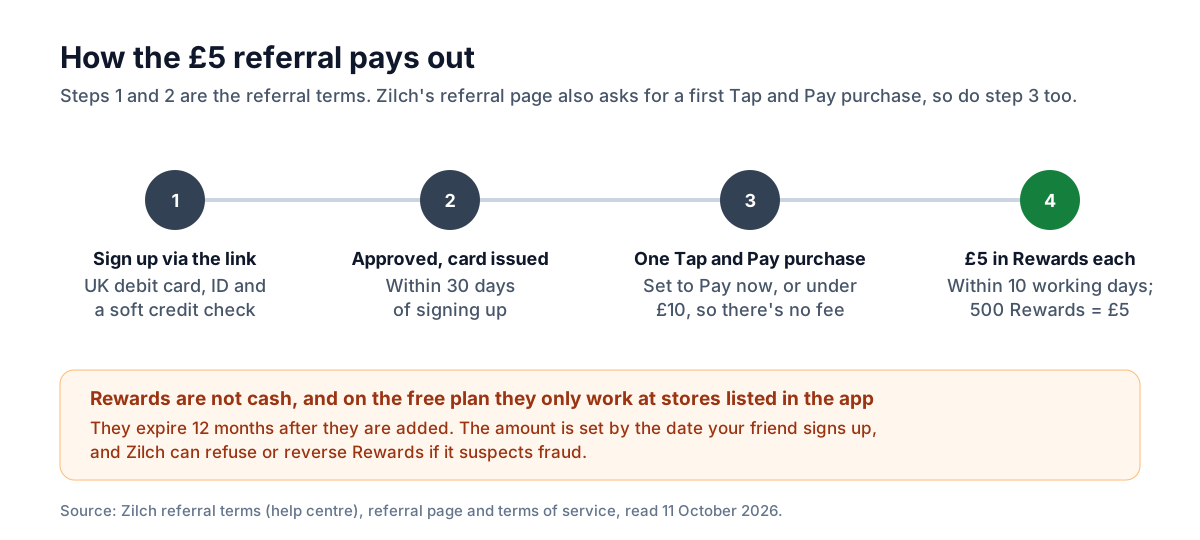
Sign up through the referral link on this page, and within 30 calendar days verify your identity, get approved and receive your Zilch card. Zilch's referral terms say it then adds £5 in Rewards to both your account and your friend's within 10 working days. Zilch's referral page adds a condition the terms don't mention, a first Tap and Pay purchase, and its Rewards page says the £5 comes when the new card is issued.
To cover all three versions, finish sign-up within the 30 days and make one small Tap and Pay purchase: add the card to Apple Pay, Google Pay or Samsung Pay, and set your smart settings to Pay now first, or keep the purchase under £10, which Zilch always processes as Pay now. Otherwise a tap could go through as Pay over 6 weeks and cost a fee of £3 or more, most of the bonus.
The amount is set by the date your friend signs up and can differ during promotions; Zilch's own example is £15 in one month and £5 in the next. You can refer as many people as you like. Zilch doesn't approve everyone who applies through a link, and it can refuse or reverse the Rewards if it suspects fraud or a breach of the terms. The £5 is 500 Rewards, not cash, with the Standard plan limits above: listed stores only, and gone after 12 months.
Disclosure: the referral link on this page is GetQuids' own, so we receive Rewards too when you qualify.
What users complain about
On 11 October 2026 the Zilch app was rated 4.9 from 33,067 ratings on the UK App Store and 4.8 from about 29,900 reviews on Google Play, where it has more than a million downloads. Zilch's Trustpilot profile scored 4.4 from about 85,000 reviews, 83% of them five stars and 8% one star, and Zilch had replied to 99% of the negative ones. Among the 250 most recent App Store reviews, 49 gave one star.
The low-rated reviews repeat a few themes: fees at shops outside the app that were higher than expected; slow support, and disputes, refunds and chargebacks left unresolved; declined payments and limits people couldn't see; credit that only comes back once a purchase is fully repaid; glitches after an app redesign and trouble logging in on a new phone; applications declined; smart settings choosing Pay now or instalments without the user noticing; the £4.99 card charge after a Plus trial; and accounts blocked after a missed payment.
Applying, your credit file and closing
You need to be 18 or over and live in the UK (not the Isle of Man or the Channel Islands), with a UK debit card (not a credit, corporate or proxy card), a UK postal address, a mobile number and an email address. You can only hold one account. To issue your card Zilch also asks for proof of ID and proof of address.
Applying runs a soft credit check, which doesn't affect your score. Once your account is open, Zilch reports your limit, how much of it you use and your repayments to the credit reference agencies every month, for the previous month. Paying on time can help build your file and missed payments harm it; because reporting runs a month behind, a payment you've since cleared can still show as missed for a while.
To complain, contact Zilch first; it has 15 business days to send a final response, or 35 in exceptional cases. After that you have six months to take it to the Financial Ombudsman Service. Support is by live chat in the app from 9am to 6pm and by phone on 020 3405 9775 from 9am to 5pm, seven days a week.
To close the account, open the app, tap the account icon, then Settings and Deactivate account. You can't close it while anything is owed, so repay any instalments first; the card stops working immediately. Rewards can't be cashed out, so spend them before you go, and cancel any Extra or Plus membership in the app before its next billing date.
Who should get it, and who should skip it
Consider it if you already shop at stores listed in the app and will mostly Pay now, if you want to split the odd purchase at a fee-free partner store and can repay on time, or if you're rebuilding a credit file and want a small limit with no interest. The £5 referral is a reasonable reason to try it, as long as you'll spend the Rewards within a year.
Skip it if you'd mainly pay later through Zilch Anywhere or Pay monthly, where the fees add up; if you've missed credit payments recently or are already paying off other buy now, pay later plans; if you want cashback as cash; or if you can't be sure your linked debit card account has money in it on each due date. Skip Plus unless you'd Pay now about £500 a month or more, or would use the tastecard anyway.
FAQ
- Is Zilch a credit card?
- Partly. It's a virtual Visa card from an app. Pay now works like debit, taking the money from your linked UK debit card; Pay over 6 weeks and Pay monthly are credit, with representative APRs from 14.9% to 31.9% depending on your tier.
- Does Zilch charge late fees?
- No late fees or interest. But Auto Snooze, which is on by default, charges £1 or £2 per instalment when a collection fails, and a missed payment can block your account, harm your credit file and, after about two months, be passed to a debt recovery agency.
- Does applying affect my credit score?
- Zilch runs a soft credit check, which doesn't affect your score. Once you have an account, it reports your limit, usage and repayments to the credit reference agencies every month.
- How much does Pay over 6 weeks cost?
- Nothing at fee-free stores in the app. Otherwise, with the card enabled in the app, £0 to £3 plus £1 over £75; through Zilch Anywhere, about £3 to £4.75 depending on the amount. The app shows the exact fee before you confirm, and it doesn't fall if you repay early.
- How do I get the £5 referral bonus?
- Sign up through our link, then verify your ID, get approved and receive your card within 30 days. Make one small Tap and Pay purchase with Pay now to meet the referral page's condition too. The £5 in Rewards arrives within 10 working days.
- Can I spend Zilch Rewards anywhere?
- Not on the free Standard plan: there, Rewards only work at stores listed in the Zilch app. Extra and Plus members can spend them anywhere Visa is accepted. Rewards aren't cash and expire 12 months after they're added.
- Is Zilch Plus worth £4.99 a month?
- On Rewards alone, only if you Pay now about £500 a month or more, because it adds one percentage point. The tastecard and free physical card may tip it if you'd use them anyway.
- How do I close my Zilch account?
- In the app: account icon, Settings, Deactivate account. You need to repay everything you owe first. Spend your Rewards before you close, and cancel any paid membership before its next billing date.