Sprive Review: How Much Can Shopping Rewards Take Off Your Mortgage?
Sprive reviewed: how the mortgage overpayment app works, who regulates it and how your money is protected, what shopping rewards and auto-save could take off a real mortgage, the catches on withdrawals and expiry, what users complain about and who should skip it.
Last updated 12 October 2026
Best for
Homeowners with a repayment mortgage at one of Sprive's 16 supported lenders who already want to overpay, have an emergency fund in place, and do a regular shop at brands Sprive lists, such as Tesco, Sainsbury's, Asda or M&S.
Sprive is a mortgage overpayment app first, and its shopping rewards are a top-up rather than a windfall. In our worked example, a £200,000 mortgage at 4.5% over 25 years, rewards of about £12 a month (3% on a £400 monthly shop) would save about £2,976 in interest and end the mortgage five months sooner, if the rate never changed. Regular overpayments do the heavy lifting: £100 a month saves about £21,142 and three and a half years, and you can pay that to your lender without any app. What Sprive adds is the habit, the tracking and the shopping top-up. What it costs you is an extra step at every till, rewards that can never be withdrawn and expire after 12 months of inactivity, and no FSCS cover. Our invite says you get Sprive Plus free and a chance in Sprive's mortgage-payment prize draw; Sprive's public pages don't define Sprive Plus, so check what the app shows after joining.
Pros
- Free to use: Sprive says it charges no fees, and earns from shopping rewards and remortgage commission instead
- Rewards at supermarkets and high-street brands including Tesco, Sainsbury's, Asda and M&S, with the exact reward shown before you pay
- Overpayments go straight to your lender from the app, tracked against the overpayment limit you set
- Optional auto-save by direct debit, and auto-saved money can be withdrawn, generally within one business day
- Works with 16 lenders, including Nationwide, Halifax, Barclays, Santander, NatWest and HSBC
- No advice fee on standard remortgages and product transfers arranged through Sprive while your account is open
Watch-outs
- Shopping rewards can never be withdrawn as cash: they only go to your lender, and only once you reach an in-app minimum
- Rewards expire after 12 months with nothing earned or applied, and lapse if you close your account
- Reward credits aren't safeguarded, and auto-saved money has no FSCS cover
- Shopping cards can't be refunded, and late or missing codes at the till are a recurring complaint
- No credit cards, and paying by Apple Pay or Google Pay earns a slightly lower reward
- Only useful if your mortgage is with one of the 16 supported lenders
Current related offer
Sprive offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Sprive
Sprive turns overpaying your mortgage into a habit: it collects small amounts by direct debit, adds rewards from shopping cards you buy in the app, and pays both to your lender. It only works with 16 lenders and rewards are never cash. Our invite adds Sprive Plus free (check in the app what it includes), and your first shop before 3 January 2027 enters a weekly draw to have your next mortgage payment covered, so join if you already want to overpay.
Requirement: None: no minimum shop; a first shop in the app before 3 January 2027 enters the prize draw
Easy5-10 minutesPayout Sprive Plus per our invite once you join (check the app); shop rewards arrive as Reward Credits within 24 hours under the terms
Verified 12 October 2026
Full claim instructions are on the Sprive offer page.
What Sprive is and who regulates it
Sprive is a free app for overpaying your mortgage. It does three things: it sets money aside for you by direct debit, it pays rewards on shopping you buy through the app, and it sends both to your mortgage lender as overpayments. It also compares your mortgage with the market and puts you in touch with an adviser when it's time to remortgage.
Sprive Limited is a London company (number 12102682, incorporated in July 2019). For mortgage advice it is an appointed representative of Connect IFA Ltd (FRN 441505) and New Leaf Distribution Ltd (FRN 460421), both authorised by the FCA, and its own register number is 919863. The money you auto-save is e-money issued by PrePay Technologies Limited (FRN 900010), for which Sprive is a registered agent. We couldn't load the FCA register to check these numbers independently, so they are Sprive's own statement; you can look them up on the FCA register.
It works only through the iOS and Android app, and only for mortgages with 16 lenders: Nationwide, First Direct, HSBC, Lloyds, Barclays, Santander, RBS, Virgin Money, Halifax, NatWest, Yorkshire Building Society, Coventry Building Society, Accord Mortgages, TSB, the Co-operative Bank and Leeds Building Society. The current account you link doesn't have to be the one your mortgage is paid from, but it must be with a bank the app supports.
Where your money sits, and how it's protected
Sprive holds two different kinds of money, and they are protected differently.
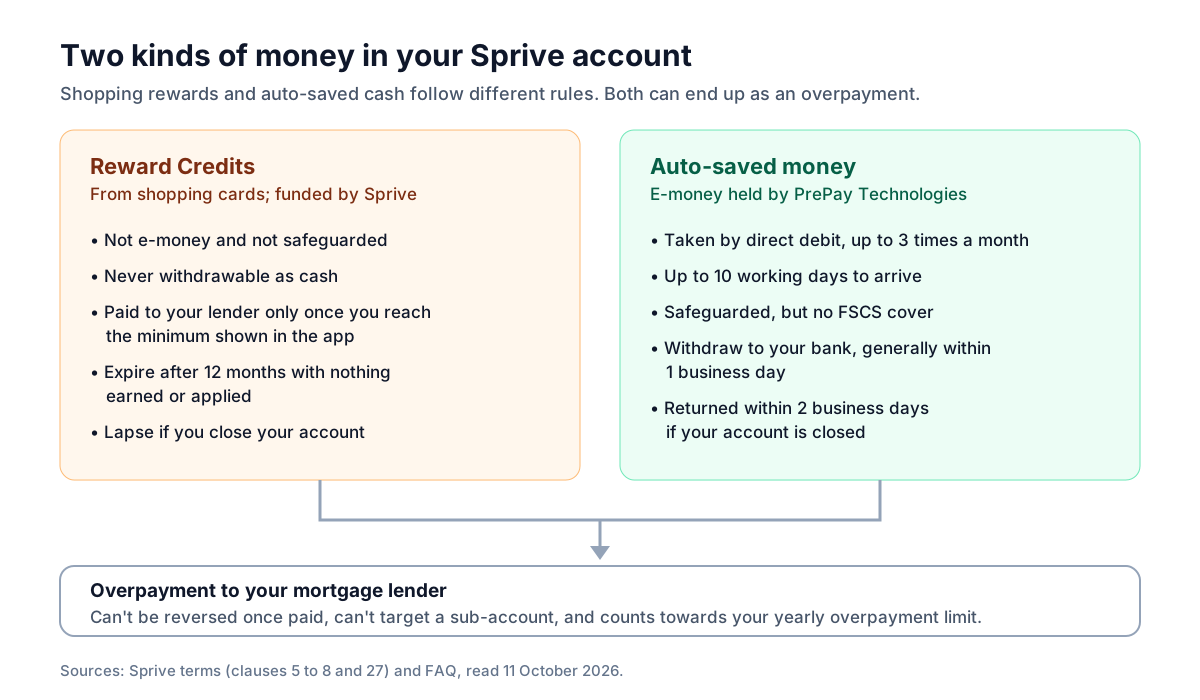
Shopping rewards are Reward Credits. Sprive funds them itself, and its terms say they are not e-money, are not safeguarded and have no cash value until you tell Sprive to pay them to your lender. You can't withdraw them, transfer them or swap them for cash. You can only send them as an overpayment, and only once your balance reaches a minimum transfer threshold shown in the app; Sprive doesn't publish the amount and can change it. If you neither earn nor apply any Reward Credits for 12 months in a row, they expire and Sprive keeps them. They also lapse if you close your account.
Money you auto-save is different. It sits in an e-money wallet in your name at PrePay Technologies, which safeguards it by keeping it separate from its own funds. That isn't FSCS protection, which doesn't apply here: if PrePay Technologies failed, getting your money back could take longer and an administrator's costs could be deducted. The balance on a shopping card you've bought isn't FSCS-protected either; if the card's issuer went bust, unused funds might be lost.
Once an overpayment reaches your lender it can't be reversed. In practice: don't let Reward Credits sit idle, and don't park money in Sprive that you might need back in a hurry.
How shopping with Sprive works
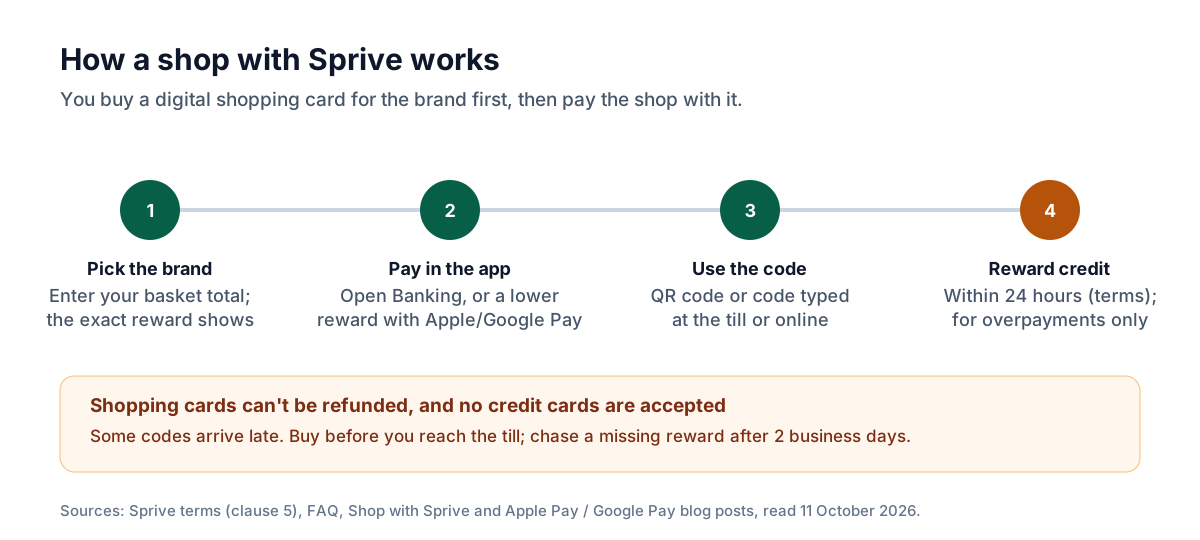
You don't link a card. Before you pay at a listed brand, you open the app, pick the brand and enter the amount you are about to spend, and the app shows the exact reward. You buy a digital shopping card for that amount, paying by Open Banking from your bank account, then show its QR code or have the code typed in at the till, or enter it at an online checkout.
Credit cards aren't accepted. Apple Pay and Google Pay are, but Sprive says the reward is slightly lower because of transaction fees. The terms say the reward should arrive within 24 hours (the App Store listing says within 15 minutes); if it hasn't arrived after two business days, email hello@sprive.com.
Two rules matter at the till. A shopping card can't be refunded once bought, and some brands' codes can be delayed, which Sprive's terms say it isn't liable for. So buy the card before you join the queue, for the amount you will actually spend, and keep another way to pay to hand.
Some users can also earn rewards by shopping online with tracked retailers through the app. Sprive's terms say this isn't available to everyone and may be invite-only or phased, that it depends on cookies and the retailer confirming the sale, and that these rewards can take a long time or not be paid at all.
Brands, reward rates and the 'supercharged' percentage
Sprive's homepage says you can shop at over 1,000 brands. Its FAQ names about 70, including Tesco, Sainsbury's, Asda, Morrisons, M&S, Waitrose, Iceland, IKEA, Argos, John Lewis, Boots, Costa and Deliveroo. Aldi and Lidl aren't on it. The FAQ still lists Amazon, but App Store reviewers said in August 2026 that Amazon rewards had gone, so check in the app before you count on a brand.
Reward rates are only shown in the app. The App Store listing says up to 15%, and the calculator on Sprive's website assumes an average of 4%. Scrimpr, an independent review site, puts typical supermarket gift-card rates at 2 to 3%, so we use 3% in our worked example.
The headline figure in the app can look higher than that. Sprive's "supercharged reward percentage" adds the reward to an estimate of the interest you would save over the rest of your mortgage by overpaying it sooner. Sprive's terms say it is for illustration only and is not a cash amount paid to your lender. You can switch the app back to the baseline reward; that is the figure to compare with what a cashback app would pay you in cash.
Auto-save, overpayments and your lender's limits
Auto-save is optional. Sprive's algorithm works out how much to set aside from your spending and the limits you choose, and collects it by direct debit, up to three times a month under its terms. The amount varies, so keep a buffer in your account: Sprive isn't liable for overdraft charges these debits cause. A collection can take up to ten working days to reach your Sprive wallet, and nobody can touch it while it's in transit. After that you can withdraw auto-saved money to your bank, generally within one business day. Sprive asks you to set up the direct debit before you can make any payment through the app.
Overpayments go to your mortgage as a whole. Sprive can't target one sub-account, and says most lenders spread an overpayment across sub-accounts equally.
Check your overpayment limit. Sprive's FAQ says fixed-rate deals usually let you overpay up to 10% of the outstanding balance a year, while tracker and variable limits vary, and lenders count the year differently (calendar year or mortgage anniversary). Go over it and your lender may charge an early repayment charge, which Sprive's terms say it isn't liable for. You can set your limit in the app and it warns you as you get close. On a £200,000 balance, 10% is £20,000 a year, far above anything shopping rewards will reach, but it matters if you also make lump-sum overpayments.
What it's worth: a worked example
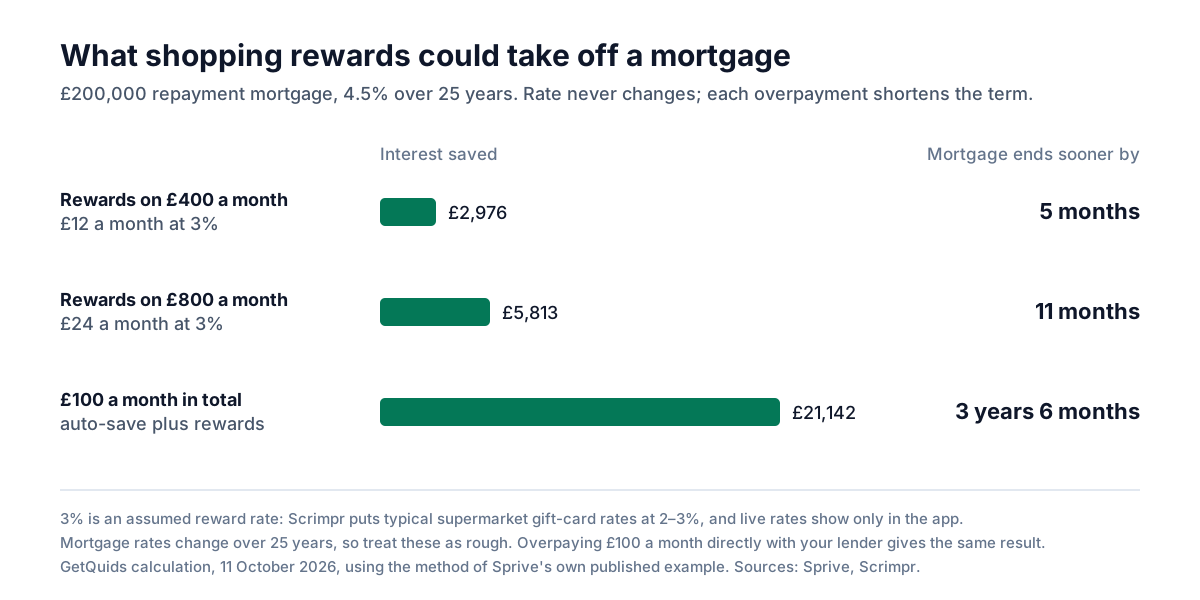
We ran the numbers for a £200,000 repayment mortgage at 4.5% over 25 years, assuming the rate never changes, every overpayment shortens the term, and rewards are 3% (a planning figure; live rates are in the app). Our method matches Sprive's own published example, which says £25 a month on a £250,000 mortgage at 4% over 30 years saves £7,969 and 1 year 1 month; we get £7,980 and 13 months.
A £400 monthly shop at 3% earns about £12 a month. Paid to the lender each month, that saves about £2,976 in interest and ends the mortgage about five months sooner. Doubling the spend to £800 a month gives £24, which saves about £5,813 and 11 months. Overpaying £100 a month in total, with auto-save making up the rest, saves about £21,142 and about three and a half years.
So the rewards are a modest top-up, and the regular overpayment is the main event. You can overpay your lender directly without Sprive; the app's value is that it automates the habit, tracks your limit and adds the shopping rewards on top. Sprive itself says to make sure you have an emergency fund and have paid off more expensive debts before you overpay, and remember that an overpayment can't be reversed once paid.
Remortgaging, and how Sprive makes money
Sprive compares your mortgage with the market every day and, when it finds a cheaper option or your deal is ending, puts you in touch with an adviser at Connect IFA. For app users with an open Sprive account there's no advice fee on residential remortgages, buy-to-let remortgages and product transfers with your current lender; Sprive's homepage puts the fee it covers at £500. More complex cases, such as converting a buy-to-let mortgage to a residential one, carry a fee that the adviser confirms before you go ahead.
That is one way Sprive earns: it receives commission from the lender if you remortgage through it, and it also makes money from the rewards brands pay when you shop. It may receive a fee or commission if it connects you to an insurance specialist too. The app is free today, but its terms reserve the right to charge fees in future. As Sprive's own site warns, your home may be repossessed if you do not keep up repayments on your mortgage.
The referral code, and our disclosure
Our invite says that if you sign up with code you get Sprive Plus free and a chance to win your next mortgage payment. Sprive's public pages don't define Sprive Plus, and its referral policy says referral bonuses vary by campaign, so check what the app shows after joining rather than counting on a particular feature.
The mortgage-payment chance is Sprive's Next Mortgage Payment Prize Draw, which every new user can enter: do your first shop through the app before 23:59 on Sunday 3 January 2027 for one entry. One winner a week has their next mortgage payment covered, capped at £5,000 and credited to their Sprive account for paying to the lender only. You must be 18 or over, live in the UK and never have had a Sprive account under another email address. The prize can't normally be withdrawn as cash; the terms make one exception: if the mortgage payment can't be made, the same amount, still capped at £5,000, is paid to your linked bank account instead.
Join with our code . It only works if you are new to Sprive, meaning you haven't downloaded the app and accepted its terms before. Sprive counts a referral once the new user has signed up with the code or link, accepted the terms, finished sign-up with an active direct debit and completed any other steps of the campaign.
Disclosure: CPR1I93Y is GetQuids' own code. When someone who joined with it does their first shop, we get one entry into Sprive's weekly referral prize draw. Every entry wins at least £5, the weekly top prizes are £2,000, £250 and £100, and prizes can only be paid towards a mortgage, not taken as cash. Sprive caps a referrer at 10 entries.
What users complain about
On 11 October 2026 Sprive was rated 4.8 from 8,422 ratings on the App Store (version 29.0.1, released 7 October), 4.8 from about 3,310 reviews on Google Play (100,000+ downloads), and 4.4 from 1,647 reviews on Trustpilot, where 72% are five-star and 5% one-star. Of the 100 most recent UK App Store reviews, from 14 August to 9 October 2026, 79 gave four or five stars and 13 gave one or two.
The positive reviews mostly say the same thing: overpayments show up on the lender's statement, and small rewards on the grocery shop add up over time.
The complaints cluster around a few themes. Shopping-card codes arrive late or not at all at the till, sometimes leaving people paying twice, with refunds passed back and forth between the shop and Sprive. Checkouts can be awkward: some codes have no barcode, so the cashier types them in, some cards are in-store only, and small balances get left over. Sign-up problems include bank connections failing and mortgage verification blocking people mid-shop, and some reviewers object to the bank and credit-file data the app asks for. Others report a slow or crashing app and slow replies from email-only support, benefits being cut or changed (Amazon rewards, surveys, retailers dropped from weekly deals), pressure to refer friends, with some brands locked until you do, and rewards stuck below the transfer threshold. A few conclude that a standing overpayment with their lender is less hassle.
Signing up and closing your account
You need to be 18 or over, live in the UK with a bank account, and pass identity and anti-money-laundering checks. Sign-up is in the app only: your email, name and address, then a read-only Open Banking link to a current account at a supported bank, which can include up to six years of transaction history where your bank makes it available. With your permission, Sprive reads your mortgage details from your credit file once a month by soft search, which lenders can't see and which doesn't affect your credit score.
To close your account, email hello@sprive.com or use the app. Deleting the app doesn't cancel the direct debit or close the account; to stop auto-save, go to Menu, Settings, Close Account, Cancel Direct Debit, or cancel it with your bank. Any e-money is returned to your bank within two business days. Apply your Reward Credits as an overpayment first, because unapplied rewards lapse when the account closes, and you can only apply them once they are over the minimum. If Sprive decides to close your account, it normally has to give you at least 90 days' notice, though its terms allow less where the law permits or requires it.
Who should get it, and who should skip it
Consider it if you have a repayment mortgage with one of the 16 supported lenders, room in your overpayment allowance, an emergency fund already in place, and a regular shop at brands Sprive lists. It suits people who won't overpay unless it happens automatically, and who don't mind buying a code before every shop.
Skip it if your lender isn't supported, if you're close to your overpayment limit, if you'd rather have cashback you can spend, if you shop mainly at Aldi or Lidl, or if you aren't comfortable linking your bank account and credit file. If you already overpay by standing order with your lender, Sprive mainly adds the shopping rewards and an extra step at the till.
FAQ
- Is Sprive free?
- Sprive says it charges no fees. It earns from the rewards brands pay when you shop and from lender commission if you remortgage through it. Its terms reserve the right to charge fees in future.
- Is my money safe with Sprive?
- Auto-saved money is e-money safeguarded by PrePay Technologies, but it has no FSCS cover. Shopping rewards are Reward Credits, which are not e-money and not safeguarded until you pay them to your lender.
- Can I withdraw my shopping rewards as cash?
- No. Rewards can only be paid to your mortgage lender as an overpayment, once you reach the minimum shown in the app. Money you auto-save can be withdrawn to your bank.
- Do Sprive rewards expire?
- Yes. They expire if you neither earn nor apply any for 12 months in a row, and they lapse if you close your account.
- Which mortgage lenders does Sprive work with?
- Sixteen: Nationwide, First Direct, HSBC, Lloyds, Barclays, Santander, RBS, Virgin Money, Halifax, NatWest, Yorkshire, Coventry and Leeds building societies, Accord Mortgages, TSB and the Co-operative Bank.
- Could overpaying through Sprive cost me an early repayment charge?
- It could if you go over your deal's overpayment allowance, often 10% of the balance a year on fixed rates. Sprive isn't liable for these charges, so check your limit with your lender and set it in the app.
- Does Sprive check my credit file?
- With your permission it runs a soft search once a month to read your mortgage details. Lenders can't see it and it doesn't affect your credit score.
- What do I get for using code CPR1I93Y?
- Our invite says you get Sprive Plus free and a chance in Sprive's Next Mortgage Payment Prize Draw, which new users enter by doing a first shop before 3 January 2027. Sprive's public pages don't define Sprive Plus, so check what the app shows after joining. CPR1I93Y is GetQuids' own code: when someone who used it does their first shop, we get a prize-draw entry worth at least £5 towards a mortgage.