Raisin UK Review: Is the £100 Bonus Worth Locking Away £10,000?
Raisin UK reviewed: how the savings platform moves and protects your money, its fixed, notice and easy access accounts, what the £100 referral bonus is worth on £10,000, tax, the catches, what users complain about and who should skip it.
Last updated 12 October 2026
Best for
UK savers with at least £10,000 they won't need for a year or more, who want fixed rates from several banks under one login and don't need a Cash ISA.
Raisin UK is a free, straightforward way to hold fixed-rate savings at several UK banks without opening an account at each one. The £100 bonus only pays off if you were going to fix at least £10,000 for a year or more anyway: in a one-year bond at 4.95% AER it lifts the year's return from £495 to £595, about 5.95% on £10,000, and over two years it adds about half a percentage point a year. The catches: the bond has to be your first account on the platform, the money is locked until maturity, it earns nothing for a few business days on the way in and out, and there is no Cash ISA yet. If you might need the money within the year, or want instant access, skip it.
Pros
- One login and one application for fixed, notice and easy access accounts from over 40 banks and building societies
- Free to use: the partner banks pay Raisin, not you
- Fixed rates on 12 October 2026 of up to 4.95% AER for one year and 5.00% for two
- FSCS cover of £120,000 per person per banking licence, and Raisin caps what you can place with one bank at that limit
- Interest paid gross, with one tax statement a year covering every account
- A £100 bonus on a first fixed bond of £10,000 or more: an extra percentage point on a one-year bond
Watch-outs
- The bonus needs £10,000 in one fixed bond of a year or longer, and it must be your first savings account on Raisin
- No early withdrawals from fixed bonds, except in exceptional circumstances
- Money earns nothing in transit: up to 2 business days to open an account and up to 2 to come back at maturity
- Easy access isn't instant, and only your nominated bank account can pay in or receive withdrawals
- No Cash ISA yet and no joint accounts, so interest above your Personal Savings Allowance is taxable
- Strict eligibility: sole UK tax residency, and no existing MSE Savings Hub, Willis Owen, AJ Bell Cash savings hub or Aviva Save account
Current related offer
Raisin UK offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Raisin UK
Register through our link as a new Raisin UK customer, then make your first savings account a fixed-rate bond of one year or longer with at least £10,000 in it, opened and funded within 365 days of registering. Raisin pays you £100 within 28 days of opening and funding, with no claim needed. Bond money is normally locked until maturity, so compare the rate and term first.
Requirement: At least £10,000 in one first qualifying fixed-rate bond for one year or longer, opened and funded within 365 days of registering
MediumApproval time varies; up to 2 business days to open after fundingPayout Within 28 days of opening and funding the qualifying bond; no claim needed
Verified 12 October 2026
Full claim instructions are on the Raisin UK offer page.
What Raisin UK is and how your money moves
Raisin UK is a savings marketplace, not a bank. It is a trading name of Raisin Platforms Limited (company 11075085, Cobden House, Manchester), which its terms say is authorised by the FCA under firm reference 813894 for investment services and 978619 for payment services. Check both numbers on the FCA register before you pay in. Its homepage says it was Moneyfactscompare's Savings Platform of the Year for 2026.
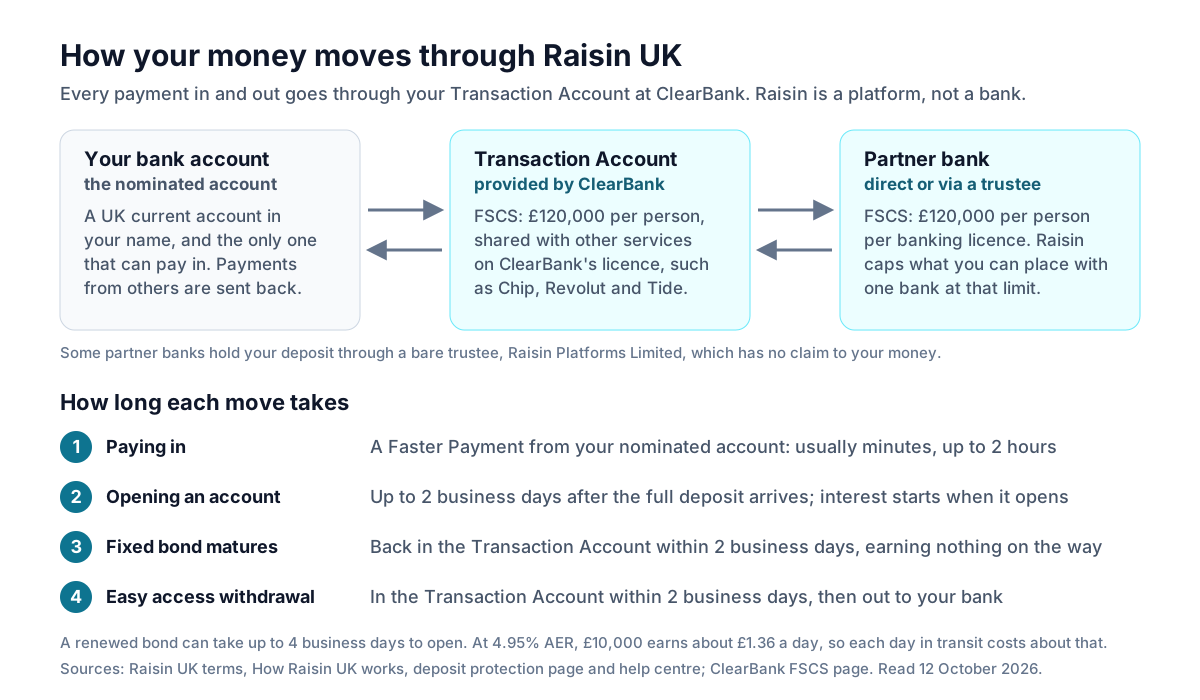
Your money passes through three places. You pay in by Faster Payment from your nominated account, a UK current account in your name, to a Transaction Account provided by ClearBank (FRN 754568). When you open a savings account, Raisin moves the money either straight to the partner bank or to Raisin Platforms Limited acting as bare trustee, which places it with the bank and has no claim to it. Raisin took over the trustee role from Meteor Asset Management in a handover that ran from March to June 2025. Interest and maturing deposits come back to the Transaction Account, and from there you withdraw to your nominated account.
Only the nominated account can pay in; money from any other account, even one in your name, is sent back. Raisin says a Faster Payment usually arrives within minutes and can take up to two hours. Once the full deposit is in your Transaction Account, the savings account can take up to two business days to open and start earning.
How your savings are protected
Raisin says it currently offers savings accounts only from UK-regulated banks, so deposits at partner banks are covered by the FSCS up to £120,000 per person, per banking licence. That limit has applied since December 2025. Some brands share one licence; Raisin's own example is Whiteaway Laidlaw, which is part of Shawbrook. The platform caps how much you can place with one bank, or one licence, at the FSCS limit.
That cap only sees what you hold through Raisin. Money you hold directly with the same bank, or with another brand on the same licence, shares the same £120,000. The FSCS information sheet you get with each new account sets out its protection, and the FCA register shows which licence a bank uses.
Money waiting in the Transaction Account is covered separately through ClearBank, up to £120,000. ClearBank provides accounts for other firms too, including Chip, Revolut, Tide and Wealthify, and anything you hold with those counts towards the same limit. If Raisin itself stopped trading, Raisin says your deposits would stay with the partner banks.
One inconsistency: a help centre article still says the most Raisin allows you to deposit at one time is £85,000, while its deposit protection page says deposits are capped at the £120,000 FSCS limit. The limit shown when you apply is the one that counts.
The accounts and rates
Raisin lists fixed rate bonds (from under a year to five years), notice accounts and easy access accounts. On 12 October 2026 its tables showed these top rates: 4.95% AER for one year (FCMB Bank UK, and QIB's Sharia account), 5.00% for two years (Investec), 5.03% for five years (Melton Building Society) and 4.15% AER variable for easy access (Whiteaway Laidlaw). Rates change often, so check the live table before you apply.
A fixed bond's rate is set once it opens and the money is locked until maturity. Raisin's help centre says early withdrawal isn't allowed except in exceptional circumstances. Some partner banks offer a 14-day cooling-off period, and the product information sheet says whether yours does. If the bank cuts the rate before you have fully funded your application, the order is usually cancelled on the day the cut takes effect, and if you fund afterwards you get the lower rate.
Notice accounts pay a variable rate; you can't make partial withdrawals, and to take money out you give notice and close the account. Easy access accounts allow unlimited withdrawals down to each account's minimum balance, but the money goes back to your Transaction Account first, which can take up to two business days, before you move it to your bank. The help centre gives £1,000 as the minimum to open an easy access account, while Raisin's easy access page says minimums start at £100; the product sheet has the exact figure. One-year bonds typically need about £1,000 or more.
Sharia accounts pay an expected profit rate instead of interest. Unlike a conventional bond, that rate can change with the bank's performance; if it falls, Raisin says you are told and can either accept the new rate or close the account.
What Raisin doesn't do: there is no Cash ISA yet (its Cash ISA page says it is "launching soon" and has a waiting list), no joint accounts, and you can't move money straight in from an existing ISA.
What £10,000 is worth, with and without the bonus
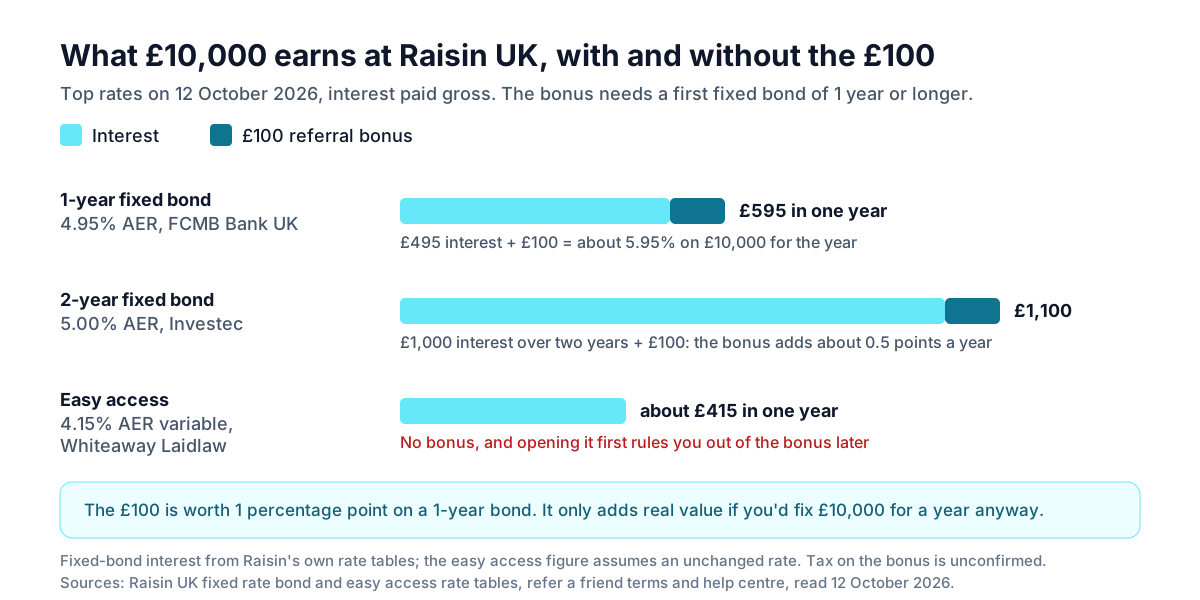
Raisin's rate tables show what each bond earns over its full term, and these figures scale them to £10,000. In the one-year bond at 4.95%, £10,000 earns £495. Add the £100 bonus and the year comes to £595, about 5.95% on £10,000. In the two-year Investec bond at 5.00% it earns £1,000 over the term, so with the bonus £1,100: the £100 is worth about 0.5 percentage points a year. The same £10,000 in the 4.15% easy access account would earn about £415 in a year if the rate doesn't change, and gets no bonus.
So the bonus is the main attraction only if you already wanted to fix at least £10,000 for a year or more. If you'd rather keep access to the money, the bonus isn't worth locking it away for. Also count the days in transit: at 4.95%, £10,000 earns about £1.36 a day, so each business day between accounts costs about that.
Tax: interest is paid without tax taken off. £495 fits inside a higher-rate taxpayer's £500 Personal Savings Allowance if you have no other savings interest, and a basic-rate taxpayer has £1,000. Raisin doesn't say how the £100 bonus is treated for tax.
The £100 referral bonus
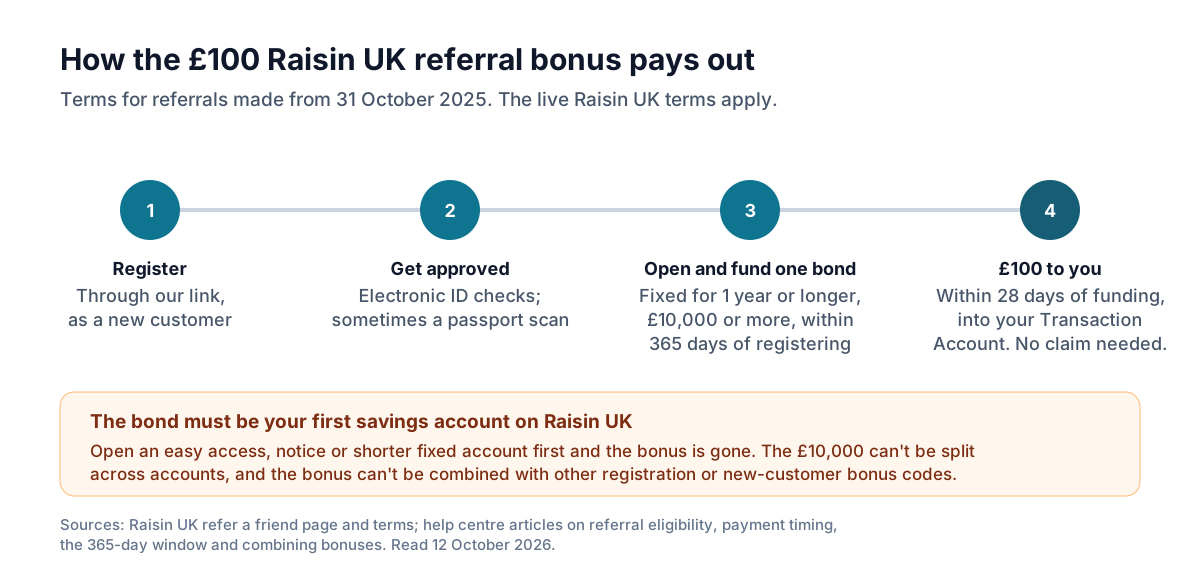
Register through our link as a new Raisin UK customer, then open and fund a fixed rate bond with a term of one year or longer and at least £10,000. All £10,000 has to go into that one account, though you can transfer it to your Transaction Account in several payments. The bond must be your first successfully opened savings account on Raisin, and you must open and fund it within 365 days of registering. Raisin pays the £100 into your Transaction Account within 28 days of the bond being opened and funded, with no claim needed.
What rules you out: opening any other savings account first, such as an easy access, notice or shorter fixed account; splitting the £10,000 across several accounts; and using another registration or new-customer bonus code, which Raisin says can't be combined with the referral bonus. These terms apply to referrals made from 31 October 2025. Raisin gives no end date, but says the scheme runs only while the offer is available.
The terms don't ask you to keep the bond for a set time, but a fixed bond is locked until maturity anyway.
Disclosure: the link on this page is GetQuids' own Raisin UK referral link, so when you qualify, Raisin pays us £100 too. That doesn't change what you get.
Fees, tax and how Raisin makes money
There are no fees for using the platform, and moving money into and out of the Transaction Account is free. Raisin says it earns an intermediary fee from the partner banks for each account opened through it, and nothing while deposits are in transit.
The real costs are elsewhere: interest lost while money moves between accounts, a rate that some users say can trail what the same bank pays elsewhere, and tax. Partner banks pay interest gross. For 2026/27 the Personal Savings Allowance is £1,000 for basic-rate taxpayers, £500 for higher-rate and nothing for additional-rate. Raisin puts one tax statement covering all your accounts in your Raisin postbox each tax year, but it doesn't give tax advice.
Maturity, renewal and the catches
Raisin contacts you about a month before a bond matures. If you do nothing, some bonds renew automatically with the same bank, so turn renewal off at least five days before maturity if you don't want it. A renewed bond can take up to four business days to open and start earning.
If you don't renew, the deposit and interest reach your Transaction Account within two business days of maturity, or later if maturity falls on a weekend or bank holiday, and no interest is paid in transit. One trap: if you have an unfunded application waiting and the matured money covers it, Raisin opens that account automatically, so cancel any application you no longer want.
What users complain about
On 12 October 2026 the Raisin app was rated 4.6 from 1,542 ratings on the UK App Store and 4.2 from about 11,500 reviews on Google Play, with more than a million downloads. Both apps serve Raisin's customers across Europe, not just the UK, and version 6.0.0, a full redesign, only came out on 6 October 2026. Raisin UK's Trustpilot profile scored 4.3 from 4,025 reviews, 436 of them in the past 12 months; 61% were five-star and 19% one-star.
The low-rated reviews repeat a few themes: money that seems to disappear for days while a bond is funded, at maturity or between accounts, earning nothing; easy access withdrawals that take two or more business days; identity checks, failed video verification and accounts waiting days for approval; app bugs and help pages written for the website rather than the app; slow replies to emails and secure messages, and long phone waits; and rates that trail what the same bank pays elsewhere or are cut before funding is complete. Long-standing users mostly praise the single login, the fixed rates and maturities that arrive on time.
Applying, opening and closing
You need to be 18 or over, a UK resident with sole UK tax residency (people in the Crown Dependencies and British Overseas Territories can't apply) and not a US tax resident. You also need a UK bank or building society current account in your name (not a business account), a National Insurance number or UK tax ID, an email address and a UK mobile number that isn't linked to another Raisin account. You can't open one if you already have a Raisin UK account, MSE Savings Hub, Willis Owen Smart Savings, AJ Bell Cash savings hub or Aviva Save.
Registering asks for your name, address, date of birth and National Insurance number. Raisin checks your identity electronically against databases including credit data and the electoral register, and again each time you apply for a savings account; some partner banks also ask for a scanned passport. Raisin doesn't publish how long approval takes, and delays here are a common complaint.
To leave, send a secure message or email Raisin and give 30 days' notice. You can only close once every savings account has closed or matured, so a bond ties you to the platform until its end date, except in exceptional circumstances such as death, terminal illness or bankruptcy. Download your statements during the notice period, because you can't access them after the account closes.
Who should use it, and who should skip it
Use it if you have £10,000 or more you won't need for at least a year, want a fixed rate without opening accounts at several banks, and are fine with interest being taxable outside an ISA. It also suits savers with more than £120,000 who want to spread money across banking licences from one login.
Skip it if you might need the money before the bond matures, want instant access, need a Cash ISA or a joint account, aren't solely UK tax resident, or already hold one of the excluded savings hubs. If you plan to open an easy access account first, know that you will lose the bonus.
FAQ
- Is Raisin UK a bank?
- No. It is a savings platform run by Raisin Platforms Limited, which its terms say is FCA-authorised. Your Transaction Account is provided by ClearBank, and your savings are held at the partner banks, either directly or through Raisin Platforms Limited as bare trustee.
- Is my money protected?
- Savings at partner banks are covered by the FSCS up to £120,000 per person per banking licence, and Raisin caps deposits at that limit. Money you hold directly with the same bank counts too. The Transaction Account is covered through ClearBank, shared with other ClearBank-based services such as Chip and Revolut.
- How do I get the £100 bonus?
- Register through our link, then make your first savings account a fixed bond of one year or longer with at least £10,000 in it, opened and funded within 365 days of registering. The £100 arrives in your Transaction Account within 28 days, with no claim needed.
- Does an easy access account count for the bonus?
- No. Only a fixed bond of one year or longer qualifies, and it has to be your first savings account on Raisin, so opening an easy access account first rules you out.
- Can I use the referral bonus with another welcome code?
- No. Raisin says the referral bonus can't be combined with other registration or new-customer bonus codes.
- Can I take money out of a fixed bond early?
- Not normally. Raisin only allows early closure in exceptional circumstances. Some banks offer a 14-day cooling-off period, which the product information sheet will show.
- Is the interest taxed?
- Yes, if it goes over your Personal Savings Allowance (£1,000 basic rate, £500 higher rate, £0 additional rate in 2026/27). Interest is paid gross and Raisin sends one tax statement a year. Raisin doesn't say how the £100 bonus is taxed.
- Does Raisin UK offer a Cash ISA?
- Not yet. Its Cash ISA page says it is launching soon and has a waiting list.