Nationwide Current Account Review: Is the £175 Switch Worth It?
Nationwide's £175 switch offer reviewed across FlexDirect, FlexAccount and FlexPlus: the 28-day and 31-day conditions, who is shut out, what FlexDirect's first-year interest and cashback add, the fees, the FSCS limit shared with Virgin Money, app complaints and who should skip it.
Last updated 11 October 2026
Best for
People who haven't had a Nationwide switch bonus since 2021, can close a current account at another bank (not Virgin Money) that has at least 2 active Direct Debits, and can route £1,500 a month through FlexDirect for its first-year interest and cashback.
Worth doing if you are eligible, and FlexDirect is the account to pick. The £175 needs a full switch moving 2 Direct Debits within 28 days, then £1,000 paid in and one card payment within 31: ordinary tasks, as long as you watch the two clocks. FlexDirect costs the same as FlexAccount (nothing) and, with £1,500 a month paid in and £1,500 left in it, adds up to £120 of cashback and about £75 of interest in year one, which is how Nationwide gets to £370. After that it is a plain account paying 1% AER on up to £1,500 with a 2.99% fee abroad, so the long-term case rests on branches, service and member perks. The catches: one sole and one joint bonus per person since 2021, nothing for switching from Virgin Money, and FlexPlus's £18 monthly fee, which outruns the bonus within the year.
Pros
- £175 for a full switch into a new or existing FlexDirect, FlexAccount or FlexPlus, with no published end date
- FlexDirect adds 5% AER on up to £1,500 and up to £120 of cashback in the first 12 months, with no monthly fee
- Paid within 10 days of meeting every requirement
- No charge for trying to go past your limit (Nationwide tries to stop the payment), and the first £50 of an arranged overdraft is interest-free
- 605 branches promised to stay open until at least the start of 2030, plus 24/7 chat with a person in the app
- Membership opens the 6.50% Flex Regular Saver and member credit cards with no fee on foreign purchases
Watch-outs
- Only one sole and one joint switch bonus per person since 2021, and none for switching from Virgin Money
- Two clocks: the switch must complete within 28 days, the £1,000 and card payment within 31
- FlexDirect's interest and cashback need £1,500 paid in every month and stop after 12 months
- 2.99% fee on card spending and cash abroad with FlexDirect and FlexAccount
- FlexPlus's £18 monthly fee outweighs the bonus within the first year unless you use the insurance
- App reviewers complain about card reader prompts, frequent forced updates and no alerts for ordinary payments
Current related offer
Nationwide offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Nationwide
Switch a current account from another bank in full, moving at least 2 active Direct Debits, within 28 days; then pay in £1,000 and make one eligible debit-card payment within 31 days. A new or existing FlexDirect, FlexAccount or FlexPlus can qualify; switches from Nationwide or Virgin Money are excluded, and sole and joint bonuses are limited to one each since 2021. Pick the earliest switch date offered.
Requirement: Switch completes within 28 days; £1,000 paid in and one eligible debit-card payment within 31 days of opening or of asking to switch into an existing account
Medium15-20 minutesPayout Within 10 days after all requirements, shown as 'Switching Offer', with the account still open
Verified 11 October 2026
Full claim instructions are on the Nationwide offer page.
What Nationwide is
Nationwide is a building society, owned by its members rather than shareholders. It is authorised by the Prudential Regulation Authority and regulated by the FCA and the PRA (registration number 106078). Holding one of its current accounts makes you a member, and membership is what opens its member-only savings accounts, loans and credit cards.
Nationwide bought Virgin Money, and the legal transfer of Virgin Money's business completed on 2 April 2026. Virgin Money keeps its own brand, apps and branches for now, but the two share one FSCS limit: eligible deposits across all your Nationwide and Virgin Money accounts are protected up to £120,000 per person, or £240,000 combined on a joint account. If you keep savings with both, the limit is shared, not doubled.
It has 605 branches, and its Branch Promise says every one will stay open until at least the start of 2030, barring circumstances beyond its control. In December 2025 the FCA fined it £44m for weak anti-financial-crime systems and controls between October 2016 and July 2021, mainly in how it monitored personal current accounts; Nationwide began a large financial-crime programme in July 2021.
FlexAccount, FlexDirect or FlexPlus?
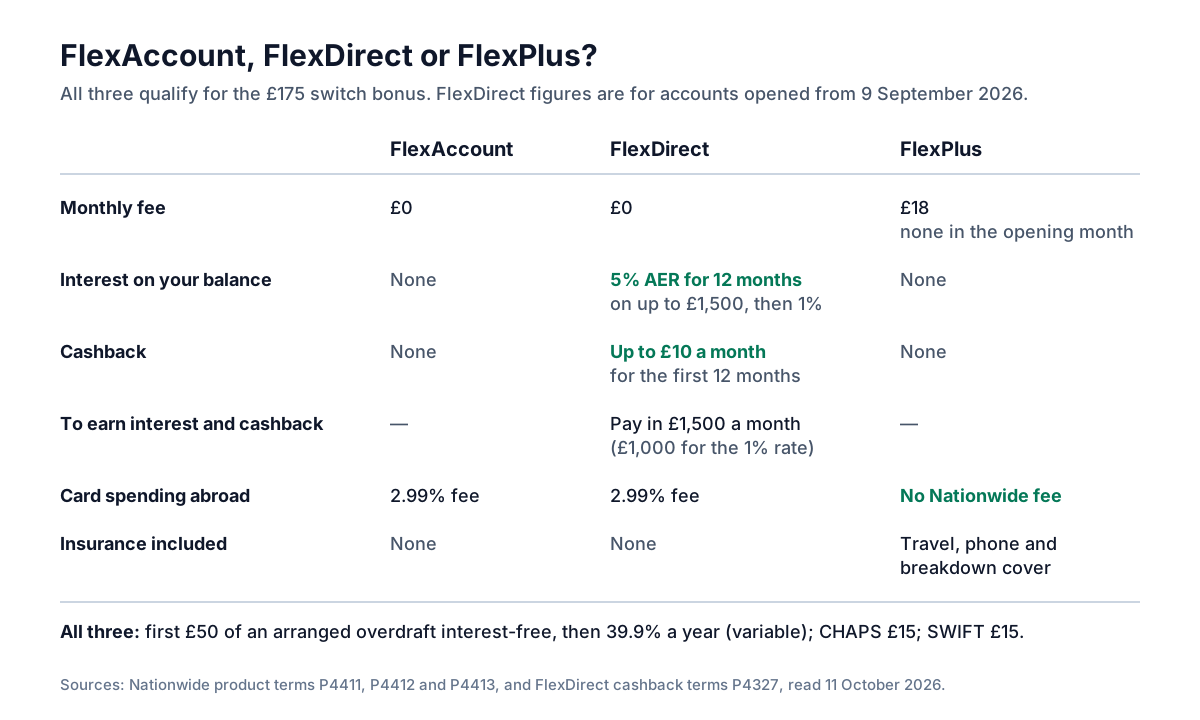
All three qualify for the £175, so the choice is about what you get after the bonus. FlexAccount is the plain one: no monthly fee and no interest. FlexDirect, relaunched for accounts opened from 9 September 2026, also has no monthly fee and adds first-year interest and cashback if you pay in £1,500 a month; you must register for Digital Banking to have it. FlexPlus costs £18 a month and bundles insurance with fee-free card spending abroad.
FlexPlus's fee is taken on the last day of each month, except in the month you open the account and the month you close or change it. It includes worldwide family travel insurance from Aviva for trips of up to 31 days (up to £10m of emergency medical cover, up to £5,000 for cancellation, a £50 excess per person per incident), family mobile phone insurance from Assurant, and AA breakdown cover in the UK and Europe. Travel cover is for you, a partner who lives with you and dependent children under 23, all UK residents, and pre-existing medical conditions are excluded unless you buy an upgrade. You can't drop individual benefits, and the fee is due even if you don't qualify for them.
For most people FlexDirect wins on paper: the same bonus, the same zero fee and extra money in year one. There is no penalty for missing its £1,500 pay-in in a given month; you just miss that month's cashback and introductory interest.
The £175 switch bonus, condition by condition
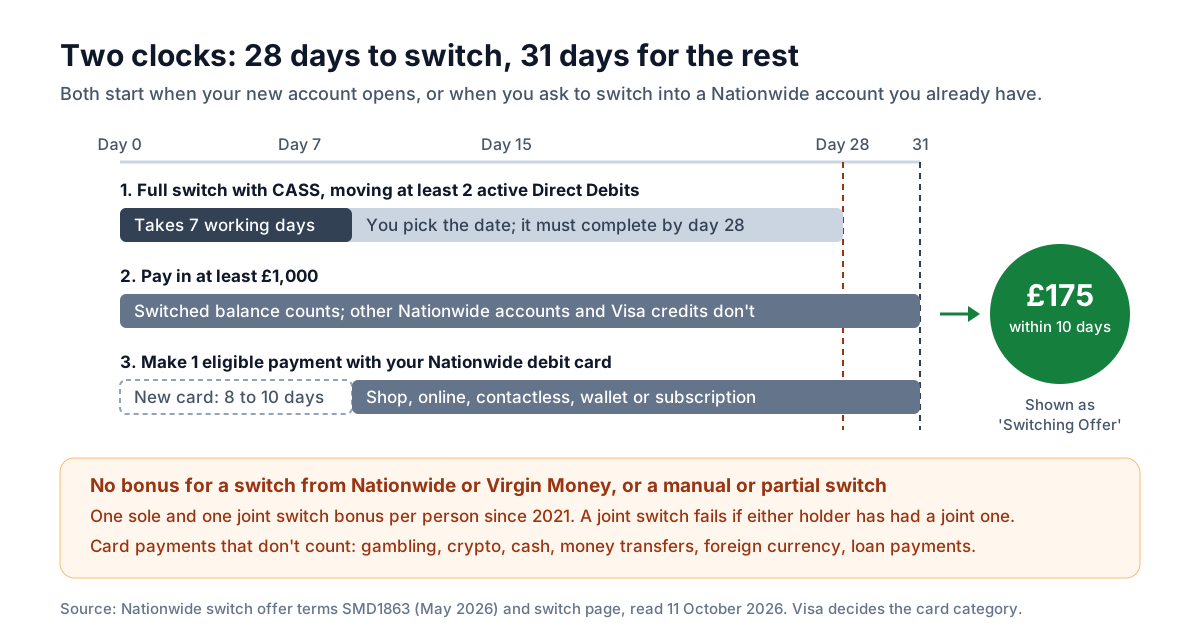
The offer started on 21 May 2026 and has no fixed end date. Open a FlexDirect, FlexAccount or FlexPlus and choose to switch while applying, or switch into one of those accounts you already hold. It must be a full switch through the Current Account Switch Service (CASS) from a current account at another provider, in your name or a joint account in your name, and the old account is closed as part of it. A manual or partial switch doesn't count. In the online application, answer Yes when asked whether Nationwide should close your old account.
The switch has to move at least 2 active Direct Debits; standing orders and recurring card payments don't count towards the two. It must complete within 28 days of your Nationwide account opening, or within 28 days of telling Nationwide you want to switch into an existing account.
Within 31 days of the same starting point, pay in at least £1,000 and make at least one payment with the debit card of the account you switched into. The £1,000 can arrive in one go or in parts; the balance moved by the switch counts, and so does a salary once it is paid into the new account. Money already sitting in an existing account, transfers from any other Nationwide account (even someone else's) and Visa credits such as refunds don't count.
Most card payments in shops or online count, including contactless, Apple Pay, Google Pay, Samsung Pay and subscriptions charged to the card. Gambling, crypto, cash withdrawals, money transfers, buying foreign currency or traveller's cheques, money orders, and loan, lease or mortgage payments don't. Nationwide goes by the category Visa gives the retailer, not by what you bought, so make the qualifying payment somewhere ordinary.
Nationwide pays the £175 into the account within 10 days of you meeting every requirement, shown on your statement as 'Switching Offer'. The account must still be open on the day, and a joint account gets one payment. Nationwide can end, change or replace the offer at any time, but if you have already asked to switch you still get it once you meet the requirements.
Two timing traps. CASS takes 7 working days and lets you pick a completion date up to 28 days ahead, so a date at the far end of that range leaves no room if anything slips; take the earliest date offered. And a new debit card arrives 8 to 10 days after the account opens, which leaves about three weeks for the card payment. If Nationwide needs extra checks before opening the account, the 31 days only start once it is open.
Who can't get it
You can get a Nationwide switch bonus at most twice: once for your first eligible sole switch since 2021 and once for your first eligible joint switch since 2021. A past sole bonus doesn't block a joint one, and the other way round. But a joint switch fails if either of you has already had a joint switch bonus, even if the other hasn't, and an existing Nationwide account that has received a switch bonus since 2021 can't earn another.
Read together, those rules let a couple with no bonus since 2021 collect up to three: one sole switch each plus one joint switch, £525 in total. Each needs its own old account at another bank with 2 active Direct Debits to close, and a joint old account can only switch into a Nationwide joint account with the same person.
You are also shut out if you switch from an account already with Nationwide, including under another trading name such as Virgin Money; if you asked to switch before 21 May 2026 or after the offer is withdrawn; if you or a joint holder has a Nationwide current account being handled by its Collections and Recoveries team when the switch completes; or if a sanction, restraint order or suspected fraud is involved. Changing an existing Nationwide account to a different Flex account isn't a switch either and earns nothing.
FlexDirect's first-year interest and cashback
For FlexDirect accounts opened from 9 September 2026, Nationwide pays 4.89% gross (5% AER) on balances up to £1,500, fixed for the first 12 months, when you pay in at least £1,500 a month. Nothing above £1,500 earns interest. It is worked out on the end-of-day balance and paid on the last day of each month. After 12 months, or if you don't qualify for the introductory rate, the standard rate is 0.99% gross (1% AER) variable, again only on up to £1,500, and needs £1,000 a month paid in.
The cashback is £5 in any month you spend at least £500 with the debit card, and another £5 in any month at least £300 goes out by Direct Debit: up to £10 a month, or £120 over the 12 months, as long as £1,500 was paid in that month. The 12 months run from the month you open, so timing matters: Nationwide's own example is that opening on 22 October leaves ten days to hit October's spend. Cashback lands on the last day of the month as 'Everyday Card Spend Cashback' and 'Everyday Direct Debit Cashback', and a joint account is still capped at £10 a month.
The pay-in can't come from another Nationwide account, and Visa credits, including refunds, don't count. The cut-off is 8.30pm on the last day of the month, or 8.30pm on the Saturday when the month ends on a Sunday. The introductory rate and the cashback are only for your first FlexDirect, or your first in 3 years; the exceptions are a sole account if you previously had only joint ones, and a joint account with someone you haven't held a FlexDirect with before. Card spend for cashback excludes the same categories as the switch offer, plus transfers, standing orders and Direct Debits.
Nationwide can change or stop the cashback with at least 30 days' notice if its budget runs out or for technical, legal or regulatory reasons, and can stop offering it to new applicants at any time. If you already hold a FlexDirect opened before 9 September 2026, the new product terms and cashback don't cover it, although you can still switch into it for the £175.
What the first year is worth
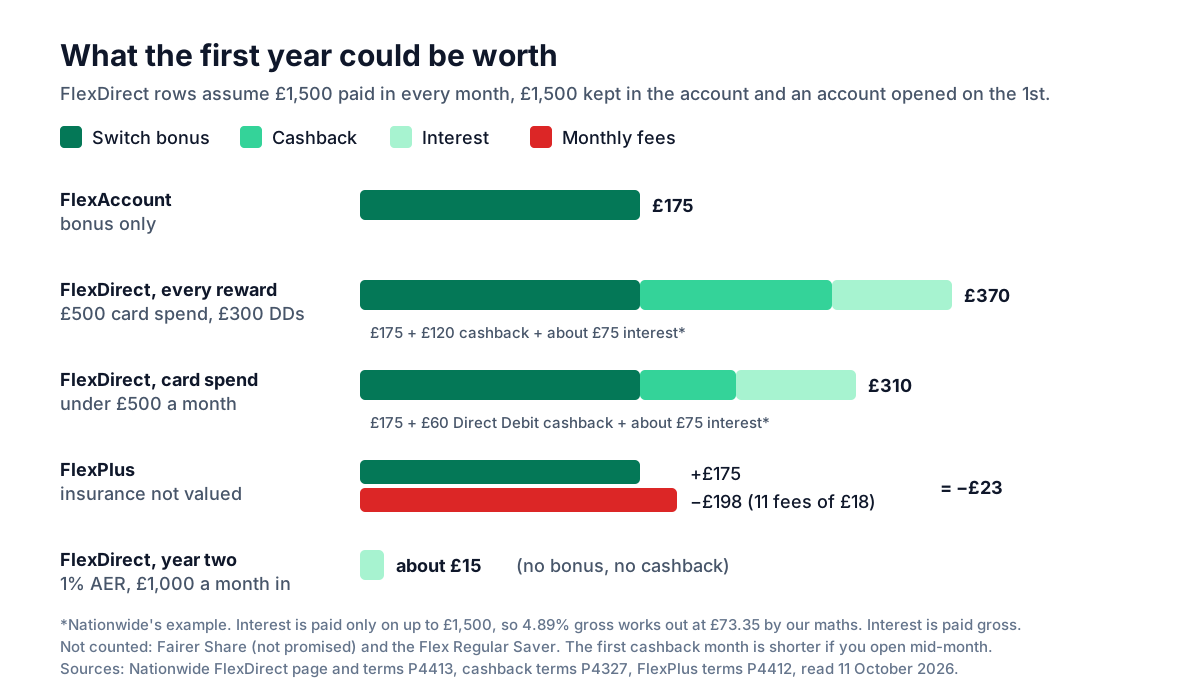
On a FlexAccount the first year is worth the £175 and nothing else. On FlexDirect with everything in place, meaning £1,500 paid in and at least £1,500 kept in the account every month, £500 on the card and £300 of Direct Debits, and an account opened on the 1st, Nationwide puts it at up to £370: £175 plus £120 of cashback plus about £75 of interest. That interest figure is Nationwide's own example; because only the first £1,500 earns anything, 4.89% gross works out at £73.35 by our maths.
If your card spending is nearer £300 a month, drop £60: about £310. FlexPlus runs the other way: 11 monthly fees of £18 in the first 12 months come to £198, so after the bonus you are £23 down before you count the insurance. In year two FlexDirect has no bonus and no cashback and pays 1% AER on up to £1,500, about £15 a year.
So the bonus is still most of the value, and FlexDirect's extras add roughly £135 to £195 if your normal spending already goes through the account. Moneyfacts, quoted in Nationwide's press release, puts the first year at up to £470 by adding a £100 Fairer Share payment, which Nationwide doesn't promise (see below), so we leave it out.
Overdraft, fees and spending abroad
All three accounts charge no interest on the first £50 of an arranged overdraft; above that it is 39.9% a year compounded (variable), or 38.2% APR representative on an assumed £1,200 limit. Nationwide's own example for £500 overdrawn: £2.94 for 7 days, £12.59 for 30 days and £25.54 for 60. You get 14 days' notice before interest is taken. Overdrafts depend on your circumstances and don't move across with the switch, so apply separately if you need one.
There are no unarranged overdraft charges. If a payment would take you past your balance or arranged limit, Nationwide tries to stop it and charges nothing, but you can't take out or spend money until you are back in credit or within your limit. If you do end up in an unarranged overdraft and don't pay it back, Nationwide can use money in your other accounts with it to clear it.
FlexDirect and FlexAccount charge 2.99% on card payments and cash withdrawals in a foreign currency. Nationwide's example: €100 costs £86.82 at the Visa rate plus £2.60. Taking out foreign-currency cash in the UK at a LINK cash machine or over the counter is free of that fee, and FlexPlus has no Nationwide fee on any of these. If you travel, Nationwide's member credit cards charge no fee on foreign purchases, subject to approval.
A CHAPS payment costs £15, and so does a SWIFT payment abroad or in a foreign currency, except euros sent to the UK or the EEA.
Member extras: the Regular Saver and Fairer Share
A Nationwide current account gives you access to the Flex Regular Saver: 6.50% AER/gross (variable) on up to £200 a month for 12 months. Nationwide's example is £84.50 of interest on £2,400 saved, paying in £200 on the 1st of each month and making no withdrawals. Up to 3 withdrawals keep the 6.50% rate; a fourth drops it to 1.05% for the rest of the year. It is online only and you can hold one at a time. It is a separate product, so it isn't in our figures above.
Fairer Share is Nationwide's profit share. In 2026 more than 4 million members got £100, paid between 10 and 30 June, if on 31 March 2026 they had a qualifying current account plus at least £100 in Nationwide savings at the end of any day in March, or a Nationwide mortgage with at least £100 owing. It has been paid every year since 2023, but Nationwide says it isn't promised: it depends on financial performance, and the amount and rules can change. Anyone switching now has missed the 2026 cut-off, and Virgin Money current accounts didn't qualify for 2026.
Service, the app and what users complain about
Nationwide says it ranked first for customer satisfaction in the UK Customer Satisfaction Index of July 2026, and it is a Which? Recommended Provider for current accounts. It offers 24/7 chat with a person in the app and internet bank, UK call centres and branches. Its results in the CMA's service quality survey are published on its own results page.
On 11 October 2026 the Nationwide app was rated 4.8 from 744,986 ratings on the App Store and 4.8 from about 232,000 reviews on Google Play. Trustpilot is lower: 3.7 from 10,966 reviews, 61% of them one-star, although Nationwide hasn't invited reviews there recently, and Trustpilot warns they may not be representative.
The low-rated reviews repeat a few themes: the card reader being demanded for payments, new payees and other changes; frequent forced updates, and the app stalling at login after one; no notifications for ordinary payments, only overdraft and low-balance alerts; payments taking a while to show in the app; and scripted or unhelpful chat and phone support. Nationwide's app page says that with biometrics set up you can approve small and repeat payments in the app, and that adding account biometrics removes the need for the card reader altogether.
A practical point if you are new to the UK: Nationwide says the app can only be downloaded from the UK App Store or Google Play onto a UK device, and needs iOS 15 or Android 8.0 or later.
Applying, switching and closing
You need to be 18 or over and a UK resident, open the account for personal use, and hold no more than 3 Nationwide current accounts already. Apply online with your address history for the past 3 years; a UK passport or driving licence makes it quicker, but without one Nationwide may ask you to prove your identity in a branch. You can also apply by phone on 0800 121 6943 (Monday to Friday 8am to 6pm, Saturday 9am to 1pm) or in a branch. Nationwide's account pages don't say whether applying involves a hard or soft credit search.
To switch, have your old bank's name, sort code and account number ready, plus the long number on your old debit card, and make sure your name and address match at both banks, because a mismatch can delay or stop the switch. For days 1 to 6 you keep using the old account; on day 7 the switch completes, your Direct Debits, standing orders, payees and balance move over, and the old card stops working. Card subscriptions, Apple Pay and similar wallets, any overdraft and your transaction history don't move, so download old statements and give subscriptions your new card. Existing members can switch into an account they already hold through the app, internet bank, a branch or by phone.
To close, use the internet bank (More options, Other account services, Close account), visit a branch with your card and ID, or write to any branch; you can't close by email. The account can't be overdrawn or have charges pending, and any linked savings account has to be closed first. Leftover money is usually sent by cheque to your registered address. Keep the account open until the £175 and any cashback have been paid, since both need it open on the day.
Who should switch, and who should skip it
Switch if you haven't had a Nationwide switch bonus since 2021 (or only a sole one, and you are switching a joint account), have a current account at another bank with at least 2 active Direct Debits that you're happy to close, and can pay in £1,000 within 31 days. Pick FlexDirect if your salary or another £1,500 a month can go into it for the first year, and £1,500 can sit in it: it costs nothing and adds up to about £195 on top of the bonus.
Skip it if you have already had the bonus you would be claiming, if your only spare account is with Virgin Money, if you want to keep your old account open, or if you spend abroad often and won't pay for FlexPlus. Skip FlexPlus itself unless you would buy travel, phone and breakdown cover anyway: its fees outweigh the bonus within the year.
FAQ
- How do I get Nationwide's £175?
- Open a FlexDirect, FlexAccount or FlexPlus (or use one you already have) and complete a full CASS switch from another bank, moving at least 2 active Direct Debits, within 28 days. Within 31 days, pay in £1,000 and make one eligible debit card payment. The £175 arrives within 10 days of meeting everything.
- Can I get it if I've had a Nationwide switch bonus before?
- Only once for a sole switch and once for a joint switch since 2021. A previous sole bonus doesn't block a joint one, but a joint switch fails if either holder has had a joint bonus, and an account that has already been paid a switch bonus since 2021 can't earn another.
- Can I switch from Virgin Money?
- Not for the bonus. Virgin Money is now part of Nationwide, and the terms exclude switches from any Nationwide account, including under the Virgin Money name.
- Which account should I choose?
- FlexDirect if you can pay in £1,500 a month: the same bonus and no fee, plus first-year interest and cashback. FlexAccount does the job if you only want the bonus. FlexPlus only makes sense if you would pay £18 a month for its insurance anyway.
- Does the £1,000 have to stay in the account?
- The terms set no holding period. They only exclude money already in an existing account, transfers from other Nationwide accounts and Visa credits. The balance moved by the switch counts.
- Can I switch into a Nationwide account I already have?
- Yes, into an existing FlexDirect, FlexAccount or FlexPlus, as long as that account hasn't had a switch bonus since 2021. The 28 and 31 days start when you tell Nationwide you want to switch, and money already in the account doesn't count towards the £1,000.
- Is my money protected?
- Yes, by the FSCS up to £120,000 per person (£240,000 combined on a joint account), but that limit covers your Nationwide and Virgin Money accounts together.
- Can I close the account once I've been paid?
- Yes, through the internet bank, in a branch or by letter, as long as it isn't overdrawn. On FlexDirect, closing early also ends the interest and cashback, and cashback is only paid if the account is open on the last day of the month.
Featured in these guides
UK bank switch problems: payments, delays and missing incentives
A CASS troubleshooting checklist: find which date matters, preserve evidence and separate payment-transfer errors from a bank's promotional reward decision.
7 min readUK bank switching bonuses: how to switch safely and get paid
How the Current Account Switch Service works, which switching offers are open now, the banking-group rules that decide who qualifies, and a checklist so the bonus actually arrives.
9 min read