Marriott Bonvoy Debit Card Review: Is the £55 or £175 Card Worth It?
Currensea's Marriott Bonvoy debit cards reviewed: how they spend from your own bank account, what the points and elite status are worth, the fees, the catches and who should skip them.
Last updated 10 October 2026
Best for
UK travellers who already stay at Marriott hotels, spend regularly in foreign currencies and care more about elite status than cashback.
This is a status card more than a points card. On points alone neither version pays for itself: in our worked example, someone spending £5,000 a year in foreign currencies roughly breaks even in year one and is behind after that. What can tip it is Silver or Gold Elite status and the yearly Elite Night Credits, which matter if you already stay at Marriott hotels. If you don't, a travel debit card with no annual fee is the simpler choice.
Pros
- No new bank account: it spends from the current account you already have, through Open Banking
- Silver Elite (standard) or Gold Elite (Premium) for as long as the card is active
- 10 or 15 Elite Night Credits a year, which Marriott says combine with the Marriott Bonvoy Amex card's
- A 0.5% foreign exchange fee on both versions
- Premium adds a Free Night Award at renewal once you spend £5,000 in foreign currencies
- Currensea says any credit check is a soft one
Watch-outs
- Annual fee paid up front (£55 or £175), with no monthly option and no refund once you have used a benefit
- Spending in pounds earns only 1 point per £1 (1.5 on Premium)
- Paying in pounds abroad earns the lower domestic rate
- It is a debit card, so no Section 75 protection
- Bank-linking and app problems are the most common complaints in app reviews
- Cash withdrawals earn no points and are only allowed abroad
Current related offer
Marriott Bonvoy Debit Card (Currensea) offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Marriott Bonvoy Debit Card (Currensea)
Stacking travel points without another credit card? Quite. Apply for the Marriott Bonvoy Debit Card (by Currensea) with referral code CK7LHN, get approved, and make one genuine purchase — the official terms name no minimum amount — and you earn 2,000 Marriott Bonvoy bonus points, credited within 14 calendar days of the qualifying transaction. Three rules: the transaction can't be cancelled, refunded or reversed; don't close the account within 90 days of approval or the bonus is lost; and the reward is points, not cash — non-transferable, no cash value. You need to be 18+, have a valid mobile number, and never have held either Marriott Bonvoy Debit Card.
Requirement: First genuine card purchase; no minimum transaction amount is stated
Medium10-15 minutesPayout Within 14 calendar days of the qualifying transaction
Verified 10 October 2026
Full claim instructions are on the Marriott Bonvoy Debit Card (Currensea) offer page.
How the card works
It is not a bank account and not a credit card. Currensea, an FCA-authorised payment institution (FRN 843507), links the card to a current account you already hold using Open Banking. When you pay, the amount is collected from that account by Direct Debit two to three working days later. Currensea does not hold your money, so your own bank's protection still applies to it.
Because collection is delayed, keep a buffer in the linked account. Whether your overdraft counts towards the card's available balance depends on what your bank shares with Currensea, and a failed collection can cost a late payment fee of up to £35.
It is a Mastercard, so it works wherever Mastercard does, although cardholders on the Head for Points forum report occasional declines at merchants such as eBay. Supported banks, as of 30 August 2026: AIB (GB), Bank of Ireland, Bank of Scotland, Barclays, Chase, Coutts, Danske, First Direct, HSBC, Halifax, Lloyds, Monzo, Nationwide, NatWest, Revolut, RBS, Santander, Starling, TSB, Ulster, Virgin Money and Wise. Basic bank accounts are not supported.
Standard or Premium?
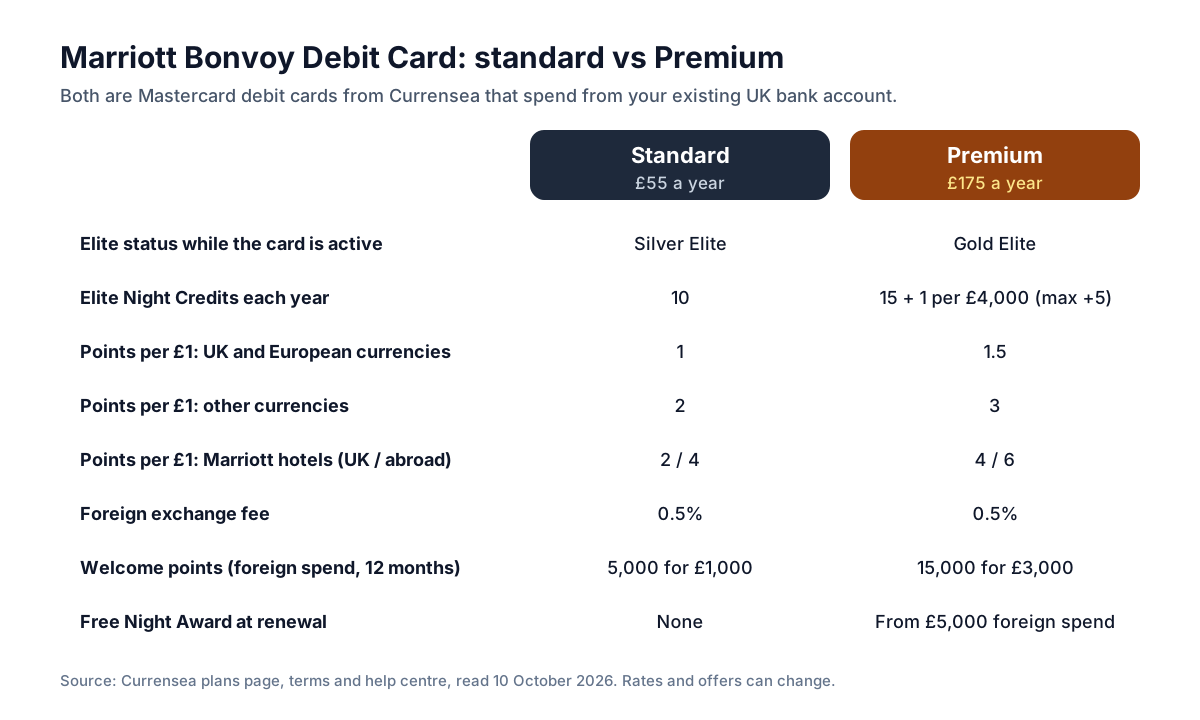
The extra £120 a year for Premium buys Gold Elite instead of Silver, 15 Elite Night Credits instead of 10 (plus one more for every £4,000 you spend, up to five), 50% more points per pound, a 15,000-point welcome bonus instead of 5,000, and a Free Night Award each renewal once you have spent £5,000 in foreign currencies.
Gold Elite adds 2pm late checkout and 25% more points on stays; Silver gives 10% more points. Status is applied within eight weeks of the annual fee being collected and lasts as long as the card is active.
The simple test: if you won't spend £5,000 a year in foreign currencies, most of the Premium case disappears, because the free night and most of the extra points depend on it.
How you earn points
The earning rate depends on the currency you pay in, not where you are. Spending in pounds, at home or abroad, earns the domestic rate: 1 point per £1 (1.5 on Premium). Listed European currencies earn the same. Other currencies earn 2 points (3 on Premium). Marriott hotels earn 2 points in the UK and 4 abroad (4 and 6 on Premium), but not third-party restaurants or shops inside a hotel.
So if a card machine abroad offers to charge you in pounds, say no: you would earn fewer points and the merchant's exchange rate is set by them, not by Currensea.
Points appear in your Marriott Bonvoy account about 14 days after each purchase and are taken back if the purchase is refunded. Rent, mortgage payments, taxes, card fees, cash withdrawals, financial products and education fees earn nothing.
Skip Point Booster. It rounds each purchase up to the nearest 10p or 20p and gives 1 point per penny rounded up, so you are paying 1p for a point that Head for Points values at about 0.5p.
What the points and perks are worth
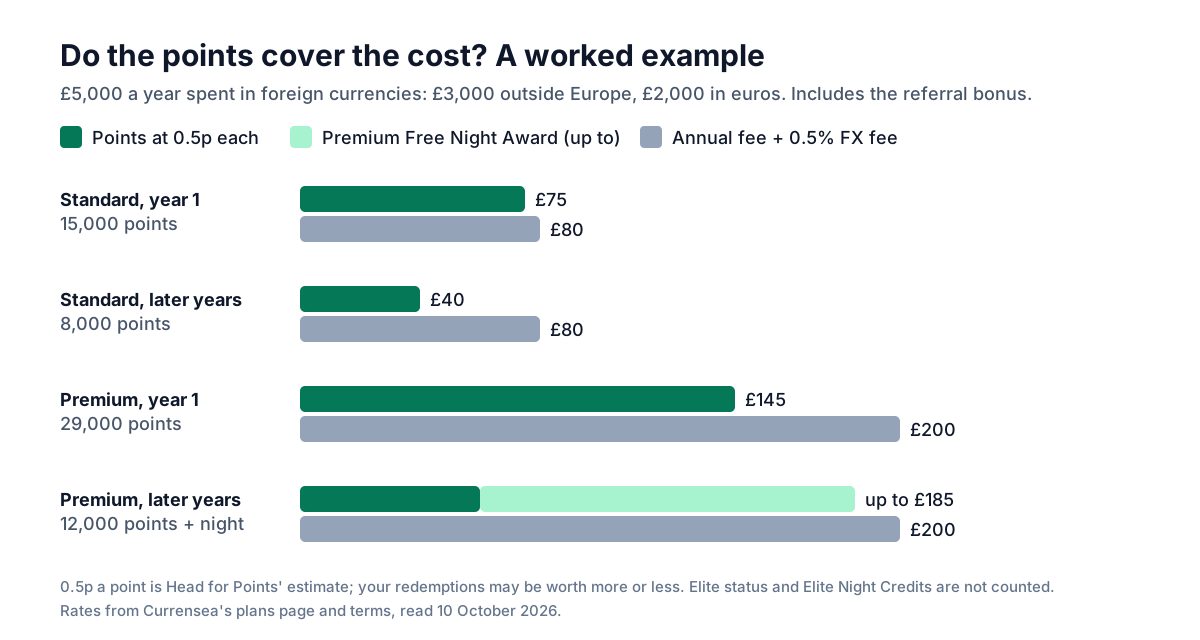
We ran the numbers for someone spending £5,000 a year in foreign currencies, £3,000 outside Europe and £2,000 in euros, valuing points at 0.5p each (Head for Points' estimate; your own redemptions may be worth more or less). Year one includes the welcome bonus and the 2,000 referral points. Currensea's referral terms don't rule out earning both, but check the live terms when you apply.
On those numbers the standard card earns about £75 of points in year one against £80 of fees, and about £40 against £80 after that. Premium earns about £145 against £200 in year one; in later years the Free Night Award (worth up to 25,000 points) brings it to as much as £185 against £200.
The gap is what you are paying for status and Elite Night Credits. Marriott's Platinum Elite needs 50 qualifying nights in a calendar year. Marriott says you can combine the debit card's credits with the Marriott Bonvoy American Express card's for up to 35 a year, which leaves 15 real nights to reach Platinum. The credits count towards the year in which they post, and the first batch arrives within 60 days of your first fee, so a card opened late in the year may credit the following year.
The referral bonus
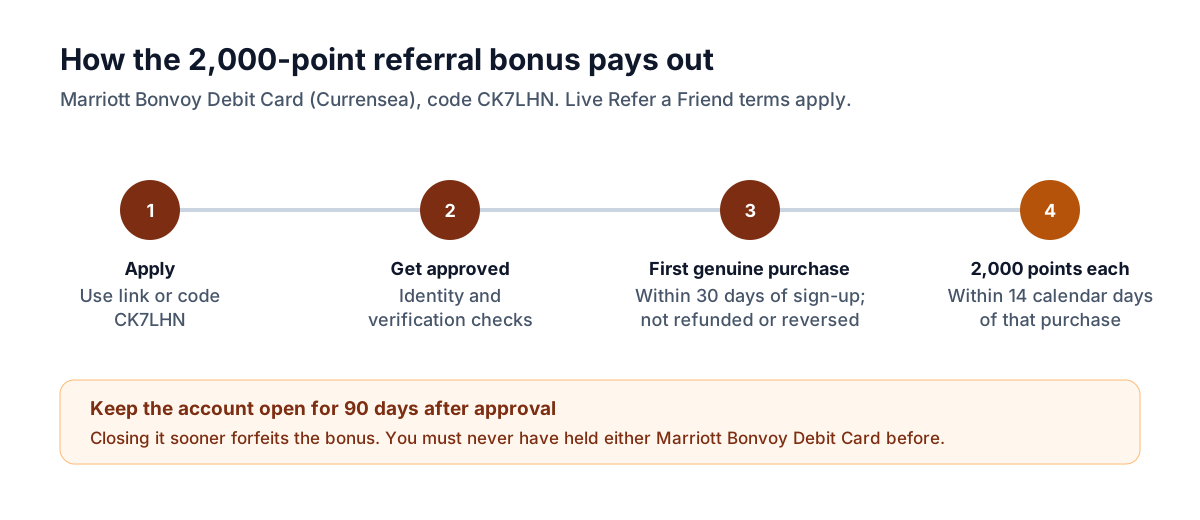
Apply through our link or with code and, once you are approved and make your first genuine purchase, you and the person who referred you each get 2,000 Marriott Bonvoy points within 14 calendar days. The referral terms set no minimum spend, but Currensea's help centre says the first transaction should be within 30 days of signing up, so don't leave it.
You won't get the points if the purchase is cancelled, refunded or reversed, if you close the account within 90 days of approval, or if you have held either Marriott Bonvoy Debit Card before. Disclosure: CK7LHN is GetQuids' own code, so we receive 2,000 points too when you use it.
Fees and cash withdrawals
The annual fee is £55 or £175, collected up front once a year. A replacement card is £5.
Foreign spending is charged at Currensea's Realtime Rate plus a 0.5% FX fee, on both cards. Currensea's help centre explains how the Realtime Rate is set for each currency.
Cash machines can only be used abroad, never for pounds. Withdrawals cost 0.5% up to £250 a calendar month and 2.5% after that, and earn no points.
Tax payments are unclear: the card terms say HMRC payments earn points for a small service fee, while a help article updated on 22 September 2026 lists HMRC as earning nothing. Ask Currensea before you pay a tax bill with it.
What cardholders complain about
On 10 October 2026 the Marriott Bonvoy Debit Card app was rated 4.5 from 198 ratings on the App Store and 4.1 from 43 reviews on Google Play. Currensea's own Trustpilot profile scores 4.9 from about 23,500 reviews, but it covers all of Currensea's cards, not just this one.
The low-rated reviews repeat a few themes: linking a bank account fails or keeps dropping, the app gets stuck during set-up or phone verification, some merchants decline the card, and support has no phone line. Android users also ask for a tracker showing progress towards the Free Night Award spend.
Applying and cancelling
You need to be 18 or over, with a mobile number, no active County Court Judgments, and an active current account at a supported bank with online or mobile banking. Identity checks run through Onfido and Currensea says it replies within two working days. If it runs a credit check, it is a soft one.
Cancel in the app under settings. There is no cooling-off period, and once you have used any benefit the annual fee is not refunded. To stop it renewing, give at least 30 days' notice before the renewal date. Points that haven't posted yet are lost when you close, and you can only switch between standard and Premium at renewal.
Who should get it, and who should skip it
Consider it if you stay at Marriott hotels a few times a year and value Silver or Gold perks, if you are chasing Platinum alongside the Marriott Bonvoy Amex card, or if you regularly spend more than £5,000 a year in foreign currencies (that is where Premium starts to make sense).
Skip it if you rarely stay with Marriott, if you want cash rather than points, if most of your spending is in pounds, if you rely on Section 75 protection for big purchases, or if your bank isn't on the supported list.
FAQ
- Is the Marriott Bonvoy Debit Card a credit card?
- No. It is a Mastercard debit card that spends from a current account you already have, through Open Banking. You don't borrow, and payments are collected from your bank two to three working days later.
- Does applying affect my credit score?
- Currensea says that if it needs a credit check it runs a soft one, which other lenders don't see. It also checks your identity through Onfido.
- Should I choose the standard or Premium card?
- Premium (£175) only starts to make sense if you spend at least £5,000 a year in foreign currencies, which unlocks its Free Night Award, or if Gold Elite perks are worth the extra £120 to you. Otherwise the £55 card gives you Silver Elite and 10 Elite Night Credits for less.
- Do I earn more points when I'm abroad?
- Only if you pay in the local currency. The rate depends on the currency, not the country: paying in pounds earns the domestic rate wherever you are.
- Can I use it to withdraw cash?
- Only abroad and never in pounds. Withdrawals cost 0.5% up to £250 a month and 2.5% after that, and earn no points.
- Can I hold it alongside the Marriott Bonvoy American Express card?
- Yes. Marriott says the two cards' Elite Night Credits combine for up to 35 a year. The referral terms only exclude people who have held either Marriott Bonvoy Debit Card before.
- How do I get the 2,000 referral points?
- Apply with code CK7LHN, get approved and make a genuine purchase, ideally within 30 days of signing up. The points arrive within 14 calendar days. Keep the account open for at least 90 days after approval.
- Can I get my annual fee back if I cancel?
- Not once you have used any benefit, and there is no cooling-off period. To avoid paying for another year, cancel at least 30 days before your renewal date.