
iFAST Global Bank Review: Is the 2.65% Multi-Currency Account Worth Opening?
iFAST Global Bank reviewed: what its 11-currency current account pays, the fixed-term and notice rates, the fees and exchange-rate catches, the £5 referral, what customers complain about and who should skip it.
Last updated 12 October 2026
Best for
People in the UK who hold or send money in more than one currency, want interest on an instant-access balance and are happy to bank entirely through an app.
Worth opening as a second account, not as your only one. Pounds earn 2.65% AER (variable) with instant access, ten other currencies earn interest too, and converting between them or spending abroad on the card carries no listed fee, although iFAST's margin sits inside an exchange rate it doesn't publish. The £5 referral is a small extra: put in £500 and you and your referrer each get £5 the next day, with no holding period, so £500 left for 30 days earns about £6.08 in total. Over a year the interest (about £13.25 on £500) matters more than the bonus. The catches are practical: no phone line, a debit card for UK residents only, and repeated reports of accounts placed under review with money stuck for weeks.
Pros
- 2.65% AER (variable) on pounds with instant access, paid monthly with no tax taken off
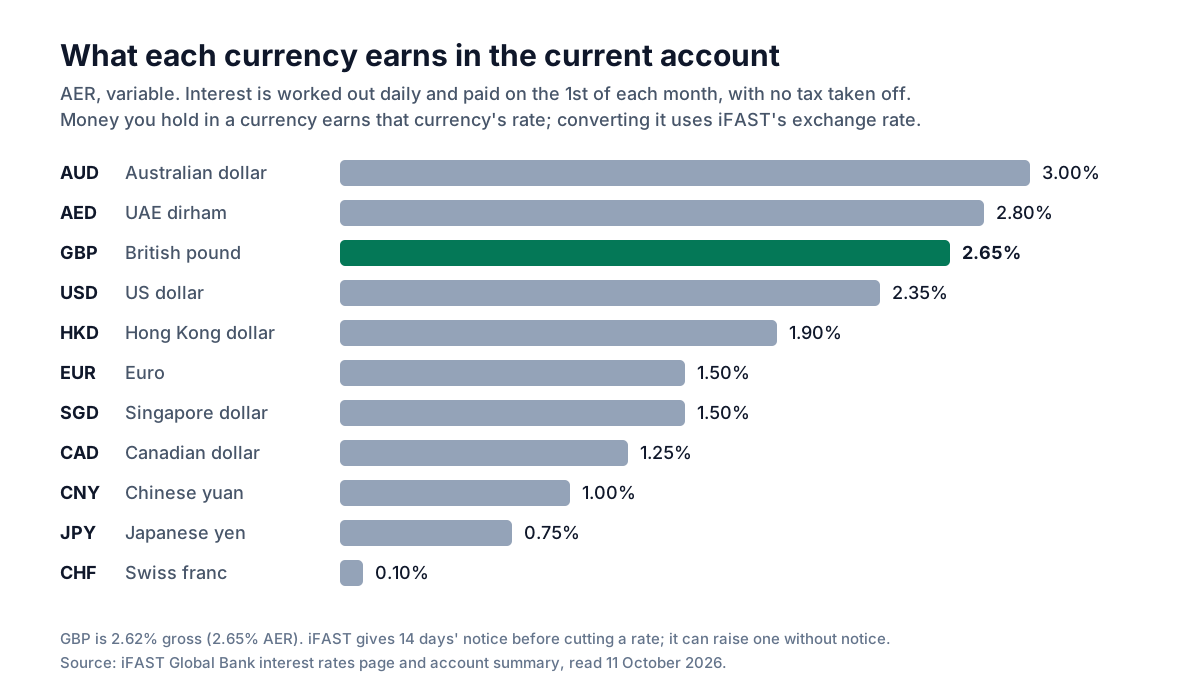
- Holds 11 currencies and every one earns interest, from 0.10% on Swiss francs to 3.00% on Australian dollars
- No listed fee for UK payments in pounds, cross-currency transfers, card spending abroad or cash withdrawals
- A UK bank (FRN 716167), so eligible deposits are FSCS-protected up to £120,000
- £5 each for a £500 first deposit, paid the next day with no holding period
- Fixed terms from 1 to 60 months (3.50% to 4.50% AER) and a 95-day notice account (3.80% AER), all from £1
Watch-outs
- App and online only: no branches, no telephone banking, and live chat keeps set hours
- The debit card is for UK residents only; nine other countries get only an Early Access waitlist
- Conversions use iFAST's own exchange rate, and it doesn't publish the margin
- Same-currency SWIFT payments cost a fee: £15 to send pounds abroad, €12 for euros, US$18 for dollars
- Reviewers repeatedly report accounts put under review or frozen, and payments held for checks, with slow replies
- Sole-name accounts only, no overdraft or cheques, and US persons can't open one
Current related offer
iFAST Global Bank offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
iFAST Global Bank
Open an iFAST account through this referral link, put in at least £500 within 30 days of approval and the £5 arrives the next day, with no need to keep the money there. It's a small extra: at 2.65% AER, £500 left for 30 days earns about £1.08 of interest on top, so the bonus matters most if you'd use iFAST as a second account anyway.
Requirement: First deposit of at least £500 (or the equivalent) within 30 days of approval, per the latest published (Q3 2026) terms; the 30 September extension calls it a minimum first deposit and published no new terms
Easy10-15 minutesPayout The day after the qualifying £500 deposit; no holding period
Verified 12 October 2026
Full claim instructions are on the iFAST Global Bank offer page.
What iFAST Global Bank is
iFAST Global Bank is the trading name of iFAST Global Bank Limited, a UK bank authorised by the Prudential Regulation Authority and regulated by the PRA and the Financial Conduct Authority (FRN 716167, company number 4797759, registered at 77 Marsh Wall in London). It is part of the iFAST group; the App Store lists iFAST Corporation Ltd as the app's seller. Eligible deposits are protected by the Financial Services Compensation Scheme up to a total of £120,000 per eligible depositor.
Everything runs through the app and online banking. There are no branches and no telephone banking, and iFAST doesn't offer overdrafts, cheque books or credit cards. The core product is the Multi-Currency Current Account: one account in your sole name, with balances in up to 11 currencies. Once it is open you can add fixed-term, notice and Flexible Cash ISA accounts, and a Visa debit card if you live in the UK.
Eleven currencies, each with its own rate
The account holds pounds, euros, US dollars, Hong Kong dollars, Singapore dollars, Chinese yuan, Japanese yen, Swiss francs, UAE dirhams, Canadian dollars and Australian dollars. The July 2026 terms list nine of these; Canadian and Australian dollars appear in iFAST's account summary and rate table but not yet in the terms.
Each balance earns its own variable rate. On 11 October 2026 pounds earned 2.62% gross, or 2.65% AER, and the other currencies ranged from 3.00% AER on Australian dollars down to 0.10% on Swiss francs. Interest is worked out daily and paid on the 1st of each month without tax taken off, so any tax due is yours to sort out. iFAST has to give 14 days' notice before it cuts a rate.
The rate belongs to the currency, not to you. Converting pounds into Australian dollars to earn 3.00% exposes you to exchange-rate moves and to iFAST's conversion margin on the way in and again on the way out, which can easily cost more than the extra interest.
Fixed-term, notice and ISA accounts
Fixed-term deposits in pounds pay a fixed rate for 1 to 60 months, from £1. On 11 October 2026 the rates were 3.50% AER for 1 month, 3.75% for 3 months, 4.00% for 6, 4.20% for 12, 4.30% for 24, 4.35% for 36, 4.45% for 48 and 4.50% for 60 months. Other currencies have their own fixed terms. The terms say a fixed-term account doesn't allow withdrawals during the term; iFAST may allow early closure in exceptional circumstances, which can cost the accrued interest plus a penalty, so only lock away money you won't need. Unless you chose auto-renewal, the deposit and interest go back to the same currency in your current account at maturity.
The 95-day notice account pays 3.80% AER on pounds (3.73% gross), 3.14% on US dollars and 2.65% on Hong Kong dollars, and you give 95 days' notice before taking money out. There is also a Flexible Cash ISA for UK tax residents aged 18 or over who hold the current account: money taken out can be put back in the same tax year without using more of your allowance. When we checked in October 2026 it paid 3.00% AER (variable).
All of these hang off the current account. Close it and the fixed-term and notice accounts close too, so read the information sheet for any penalty before you do.
Everyday banking and the debit card
Pounds move by Faster Payments and CHAPS, free both ways. You can have a salary paid in by Bacs and opt in to Early Salary Credit, which credits a Bacs payment one business day early (iFAST can take it back if the payer's money never arrives). Standing orders in pounds are free. The July 2026 terms cover Direct Debits, but iFAST's October 2025 fee document still lists them as not available, so check in the app before you move bills across.
The Visa debit card works with Apple Pay and Google Pay, with no fee for spending or cash withdrawals in the UK or abroad. It is only for UK residents. If you live elsewhere but plan to move, work or study in the UK, the terms say you can send proof and iFAST will help with the application. In a 29 September 2026 announcement iFAST opened an Early Access waitlist for customers in Hong Kong, Singapore, Thailand, Malaysia, Taiwan, the UAE, Pakistan, Germany and Italy: digital cards first, physical cards later, and each successful referral moves you up the queue.
The app also has Worldwide Scan & Pay, for paying by QR code at participating merchants abroad from any of your balances; same-currency payments aren't supported. From 17 August to 30 November 2026 it pays 1.5% cashback on up to £2,000 of Scan & Pay spending a month (£30 maximum), credited the month after (November's on 31 December). The older 1.5% card cashback ended on 31 December 2025, and we found no 2026 replacement.
What it's worth
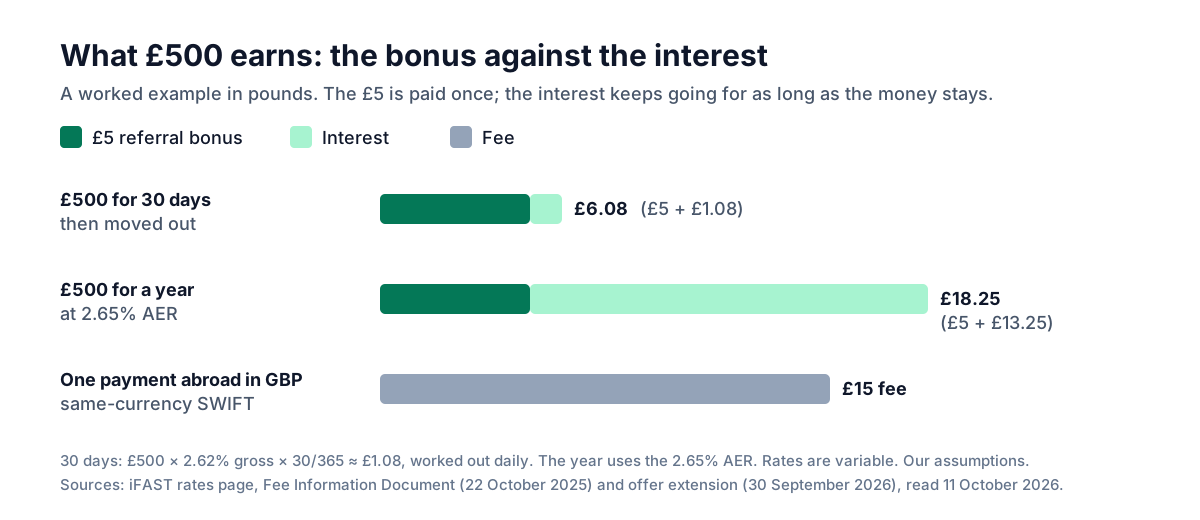
For most people the interest is worth more than the bonus. Using iFAST's own method (interest worked out daily at 2.62% gross), £500 left in pounds for 30 days earns about £1.08, so with the £5 referral bonus that is roughly £6.08. Left for a year at 2.65% AER, the same £500 earns about £13.25, or £18.25 with the bonus. Bigger balances earn proportionally more interest; the bonus stays at £5.
So the £5 is the main value only if you open the account just to pass £500 through it. If you would hold money in several currencies anyway, it is a small extra on top. One expensive slip undoes either: a same-currency SWIFT payment of pounds abroad costs £15, three times the bonus.
The £5 referral
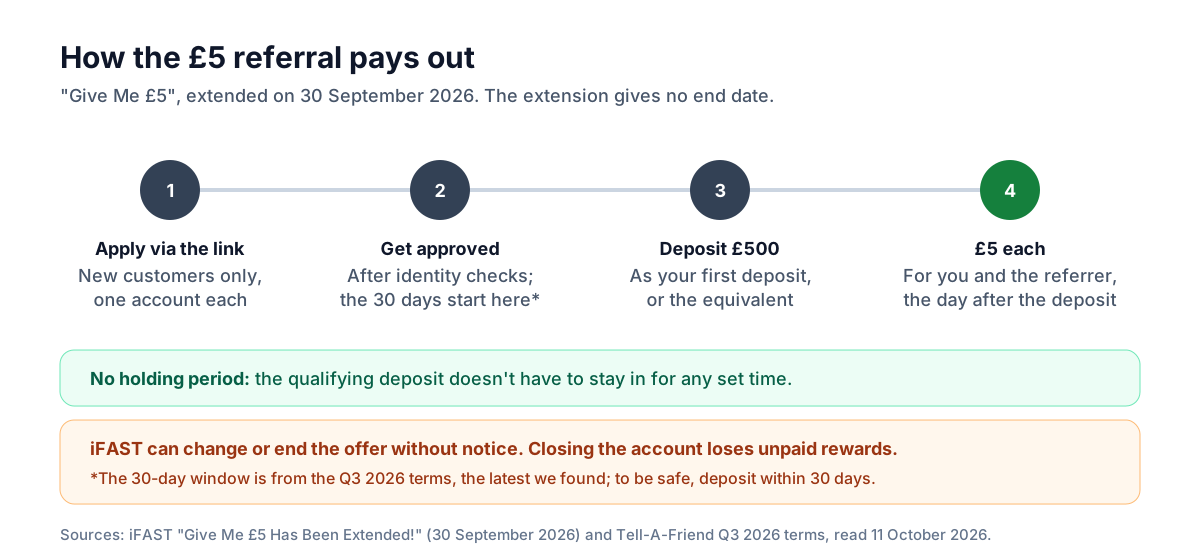
iFAST extended its Give Me £5 promotion on 30 September 2026, the day the published window (8 March to 30 September 2026) was due to end. Apply through the link on this page, pass the identity checks and make a first deposit of at least £500, or the equivalent in another supported currency, and you and the person who referred you each get £5. The extension article says the qualifying deposit doesn't need to be held for any set period.
The extension article gives no end date and we found no newer terms, so the latest published terms are the Q3 2026 ones. They ask for the £500 within 30 days of your account being approved and pay the £5 the day after the deposit. To be safe, put the whole £500 in as one deposit inside those 30 days, and wait until the £5 has landed before moving the money out.
You won't get it if you already bank with iFAST, if you refer yourself or open a duplicate account, or if iFAST suspects improper or fraudulent activity; it can also freeze an account over suspicious referral activity. If the account closes before the reward is paid, the reward is lost. iFAST can swap the £5 for a different reward, or change or end the programme, without notice.
Disclosure: the link on this page carries , GetQuids' own referral code, so we receive £5 too when you qualify. Once your account is open you get your own link, and iFAST says you can refer as many friends as you like at £5 each.
Fees and catches
Running the account is free, as are Faster Payments, CHAPS, transfers between iFAST accounts, incoming SWIFT payments, and cross-currency payments sent by SWIFT or EzRemit. Same-currency SWIFT payments are charged: £15 to send pounds abroad, and €12, US$18, S$25, HK$145, ¥126 (yuan), JP¥2,050, CHF18 or AED95 to send those currencies, whether to another country or to another UK bank. The fee document predates Canadian and Australian dollars and lists no fee for them. The July 2026 terms also let you send euros by SEPA, which the fee document doesn't cover either, so check the fee in the app before choosing SWIFT. Banks along the way may take their own charges.
There is no separate foreign exchange fee: the cost is built into the exchange rate iFAST quotes, and it doesn't publish its margin. Compare the app's rate with the mid-market rate before converting a large sum.
Smaller costs: the first replacement card is free, then £5 each, and cancelling a payment costs £25 if iFAST manages to cancel it. Payments go out on business days with a 3pm cut-off and can take up to five business days. For UK payments in pounds iFAST may ask you to send a small test payment and confirm the payee before releasing the rest, and daily payment limits can be adjusted based on your account and how you use it. Card limits are set at iFAST's discretion; the app shows yours.
What customers complain about
Ratings are high. On 11 October 2026 the iFAST GB app scored 4.7 from 1,059 ratings on the App Store and 4.5 from about 1,800 reviews on Google Play. Trustpilot showed 4.6 from 3,017 reviews, and Smart Money People 4.75 from 1,355, though its recent trend there was negative.
The low-rated reviews repeat a few themes: accounts placed under review, frozen or closed, with weeks of silence; transfers blocked or questioned by security checks, even between your own accounts; slow onboarding; no phone line, slow email and chat, and an unhelpful AI assistant; app logouts and form errors; restrictive transfer limits; and the card being unavailable outside the UK. The praise is for the rates, handling several currencies in one place, free cross-currency transfers and the fee-free card abroad.
Applying and cancelling
You need to be 18 or over and apply in your own name: there are no joint accounts, and you can hold only one Multi-Currency Current Account. Apply in the app or on the website and complete the identity checks. You don't need to live in the UK to open the account, only to get the card. The minimum deposit is one unit of any supported currency, with no maximum. iFAST can't open accounts for US citizens or green card holders, or for anyone with a US tax number or US address. It doesn't publish a standard opening time, and slow onboarding is a common complaint.
Support is by live chat, including audio and video calls, from 1am to 11pm GMT (2am to midnight BST) on business days and 8am to noon GMT (9am to 1pm BST) at weekends, or by email at clienthelp@ifastgb.com. There is no phone line.
You can cancel within 14 days of the day after iFAST confirms your account is open, by emailing clienthelp@ifastgb.com. After that you can close at any time, also by email. Closing the current account also closes the card and any fixed-term and notice accounts, and any referral reward not yet paid is lost.
iFAST can close your account too. The key information at the front of its terms says it gives three months' notice, while clause 2.8.1 says at least two months; either way, it can act immediately in listed cases such as suspected fraud or a serious breach of the terms.
Who should get it, and who should skip it
Consider it if you earn, hold or send money in more than one currency, for example if you split your life between the UK and Hong Kong, Singapore or the UAE; if you want 2.65% AER on an instant-access pound balance alongside your main bank; or if you would use the fixed terms or notice account anyway. The £5 is a pleasant extra on a deposit you were going to make.
Skip it if you want a phone line or a branch, if this would be your only account for rent and bills (account reviews can lock money for weeks), if you need the card but don't live in the UK, if you are a US person, or if you mostly send pounds abroad, where each same-currency SWIFT payment costs £15.
FAQ
- Is my money safe with iFAST Global Bank?
- It is a UK bank authorised by the PRA and regulated by the PRA and FCA (FRN 716167), so eligible deposits are protected by the FSCS up to £120,000 in total per eligible depositor.
- Is the £5 referral offer still running?
- iFAST extended it on 30 September 2026. The extension gives no end date, we found no newer terms, and iFAST can change or end the offer without notice, so check the offer shown when you open our link before you apply.
- Do I have to keep the £500 in the account?
- No. The extension says the qualifying deposit doesn't need to be held for any set period. The £5 is paid the day after the deposit, so wait until it lands before moving the money.
- Can I get the debit card if I don't live in the UK?
- Not yet. The card is for UK residents; if you are moving to the UK, iFAST says it will help once you send proof. Customers in nine countries, including Hong Kong, Singapore and the UAE, can join an Early Access waitlist for a digital card.
- How much does it cost to send money abroad?
- Cross-currency payments have no listed fee, but the cost sits in iFAST's exchange rate. Sending a currency without converting it costs a SWIFT fee, such as £15 for pounds or US$18 for dollars.
- Is the interest taxed?
- iFAST pays interest without deducting tax, and you are responsible for any tax due on it.
- Can I open a joint account?
- No. Accounts are in a sole name only, and each person can hold one Multi-Currency Current Account.
- How do I close the account?
- Email clienthelp@ifastgb.com. Within the 14-day cooling-off period that cancels it; after that it closes it. Closing also ends the card and any fixed-term and notice accounts, and unpaid referral rewards are lost.