
HSBC Bank Account Review: Is the £220 Switch Bonus Worth It?
HSBC's Bank Account and its £220 switch offer reviewed: every condition, who counts as an existing customer, how it compares with first direct's offer, the fees abroad, the complaints and who should skip it.
Last updated 11 October 2026
Best for
Switchers with a spare current account and at least 2 Direct Debits, who can pay in £2,000 and put £500 of normal spending on the card within 60 days, and who haven't had an HSBC UK or first direct current account since the start of 2023.
Worth doing if you qualify and can hit the targets without buying things you don't need: £220, no monthly fee, and a 5% Regular Saver that adds about £81 in year one if you save £250 a month. Two things to weigh first. HSBC and first direct are the same group and each one's offer shuts out recent customers of the other, and first direct's £210 asks for half the pay-in and five card payments instead of £500 of spending. And HSBC can take up to 60 days after you qualify to pay, so allow around four months from opening to cash. As an everyday account it is ordinary: 2.75% on foreign spending, only £25 of interest-free overdraft, and 11th of 17 for overall service in the official survey.
Pros
- £220 with no fixed end date, and if HSBC withdraws the offer after you have requested your switch, you still qualify
- No monthly account fee
- The £2,000 can be paid in in several parts and doesn't have to stay in the account
- Opens HSBC's Regular Saver: 5.00% AER/gross fixed for 12 months on £25 to £250 a month
- Access to Global Money, a multi-currency account whose card spends abroad with no HSBC fees
- The App Store rates HSBC's app 4.8 from more than 1.7 million ratings
Watch-outs
- Sole accounts opened in the app only: joint accounts and applications online, in branch or by phone don't qualify
- Excluded if you are an HSBC UK or first direct customer, or opened one of their current accounts on or after 1 January 2023
- Twice first direct's pay-in, and £500 of real card spending rather than a handful of payments
- Payment can take up to 60 days after you qualify, so up to about four months in all
- 2.75% on foreign card payments, plus 2% (minimum £1.75) on cash withdrawals abroad
- 11th of 17 providers for overall service in Great Britain in the August 2026 survey
Current related offer
HSBC offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
HSBC
Open a sole HSBC Bank Account in the HSBC UK app and, within 60 days, complete a full CASS switch with at least 2 Direct Debits, pay in £2,000 and spend £500 on the debit card. HSBC pays £220 within 60 days of you qualifying; current and recent HSBC UK or first direct customers are excluded. Screenshot each step as you go.
Requirement: Within 60 days of opening in the app: full CASS switch with at least 2 Direct Debits, £2,000 paid in and £500 of eligible debit-card purchases
Medium15-20 minutesPayout Within 60 days after all qualifying criteria are met
Verified 11 October 2026
Full claim instructions are on the HSBC offer page.
Related comparisons
HSBC vs First Direct Switch Bonuses
HSBC vs First Direct switch bonuses compared by cash reward, eligibility exclusions, pay-in rules and payout timing.
Read comparison →
Barclays vs HSBC Switch Bonuses
Barclays vs HSBC switch bonuses compared by headline reward, deposit/spend rules, deadlines and payout timing.
Read comparison →
What the account is and who runs it
The Bank Account is HSBC UK's standard current account, with no monthly fee and a Visa debit card. It is run by HSBC UK Bank plc, which is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority (Financial Services Register number 765112).
Eligible deposits are protected by the FSCS up to £120,000, or £240,000 for joint accounts. That limit is shared across HSBC UK, HSBC Private Bank, first direct, M&S Bank and M&S Savings and Investments, so money spread across those brands is only covered once.
HSBC doesn't advertise any interest on the current-account balance. The interest is in the savings accounts that come with it: the Regular Saver pays 5.00% AER/gross, fixed for 12 months, on £25 to £250 a month, and the Online Bonus Saver pays 3.35% AER (3.30% gross) on up to £50,000 in any month you don't withdraw, or 1.05% AER in a month you do. Current-account customers can also open a Global Money Account in the app and use HSBC's home&Away shopping and dining discounts.
The £220 switch offer, condition by condition
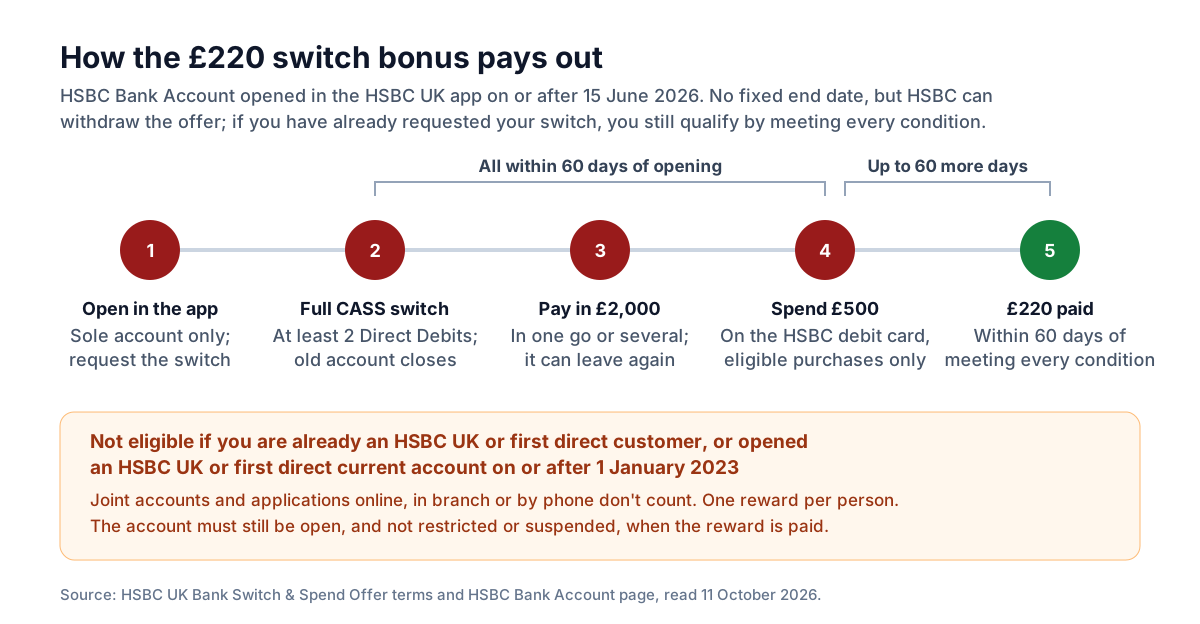
Open an HSBC Bank Account in the HSBC UK Mobile Banking app on or after 15 June 2026. You need to be a UK resident aged 18 or over, and it has to be a sole account: the app only opens sole accounts, and HSBC says applications not completed in the app don't qualify. A Basic Bank Account or Premier Bank Account doesn't count either.
Then, within 60 days of opening: complete a full switch with the Current Account Switch Service (CASS) that brings at least 2 Direct Debits with it, pay in at least £2,000, and spend at least £500 on your HSBC debit card. You qualify once HSBC has confirmation that the switch has completed and the pay-in and spending are done inside the 60 days.
The £2,000 can arrive in several payments (salary, transfers and cash all count) and doesn't have to stay. The £500 can be several purchases, including Apple Pay, Google Pay and Samsung Pay. Cash withdrawals, fees, refunded or reversed purchases, gambling, credit card or insurance payments, card-to-card payments and transfers from your other HSBC accounts don't count. Ordinary purchases are the surest way to reach £500.
HSBC pays the £220 into the account within 60 days of you meeting everything, once per person, and only if the account is still open and not restricted or suspended at that point. The offer has no end date, but HSBC can end it without notice; if you have already requested your switch when that happens, you still get the reward by meeting the conditions. HSBC can also refuse the reward and suspend the account if it reasonably believes you are trying to abuse the offer.
Who counts as an existing customer
You can't get the reward if you are already an HSBC UK or first direct customer, or if you opened an HSBC UK or first direct current account on or after 1 January 2023. That is the wording of the offer terms. The Bank Account page puts it more widely, as anyone who has held an HSBC UK or first direct current account since 1 January 2023, so if you had one open at any point since then, assume you don't qualify unless HSBC tells you otherwise. HSBC staff are excluded too.
The terms don't define "customer". HSBC asks existing customers to apply in a branch, and branch applications don't qualify, so a live HSBC UK credit card or savings account is likely to rule you out. Older relationships can cause trouble too: in the MoneySavingExpert forum thread on this offer, some people who had HSBC accounts before 2023 were told by HSBC's complaints team that the offer is only for customers new to the bank, wording the offer terms don't use, while others with similar histories were paid.
The bigger catch is first direct, which belongs to the same group. Its own switch offer excludes anyone who has opened an HSBC current account on or after 1 January 2018. So taking HSBC's £220 rules out first direct's offer under its current terms, and taking first direct's makes you a first direct customer, which rules out HSBC's. Pick one on purpose.
HSBC or first direct?
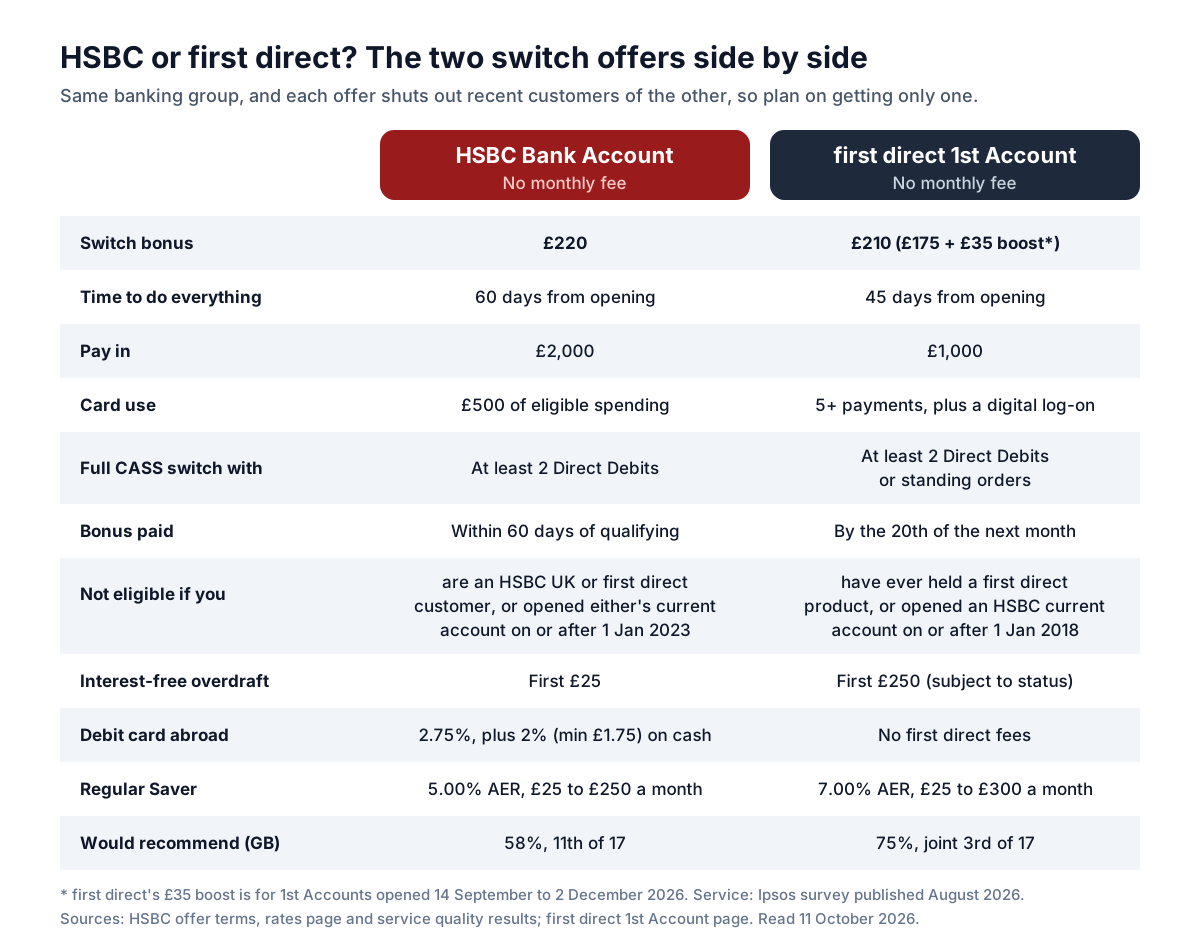
If you qualify for both, compare them before you apply. first direct currently pays £210 (£175, plus a £35 boost for 1st Accounts opened between 14 September and 2 December 2026) for less work: within 45 days, a full switch with at least 2 Direct Debits or standing orders, £1,000 paid in, five or more debit card payments and a log-on to its app or online banking. HSBC pays £10 more for twice the pay-in and £500 of actual spending, and can take longer to pay.
As an account to keep, first direct looks stronger on paper: no first direct fees on its debit card abroad against HSBC's 2.75%, the first £250 of overdraft interest-free (subject to status) against £25, a 7.00% Regular Saver against 5.00%, and 75% of its customers in the official Great Britain survey would recommend it, against 58% for HSBC. HSBC's case is the extra £10, its branches, and an exclusion that only looks back to 2023, which suits people who switch regularly.
If you have a salary or savings of £100,000 or more, HSBC's Premier Bank Account offer pays £500 for a full switch with a £100,000+ salary or for transferring £100,000+ in savings or investments. Its exclusion is different: you can't have held an HSBC or first direct account since 1 January 2025.
What it's worth
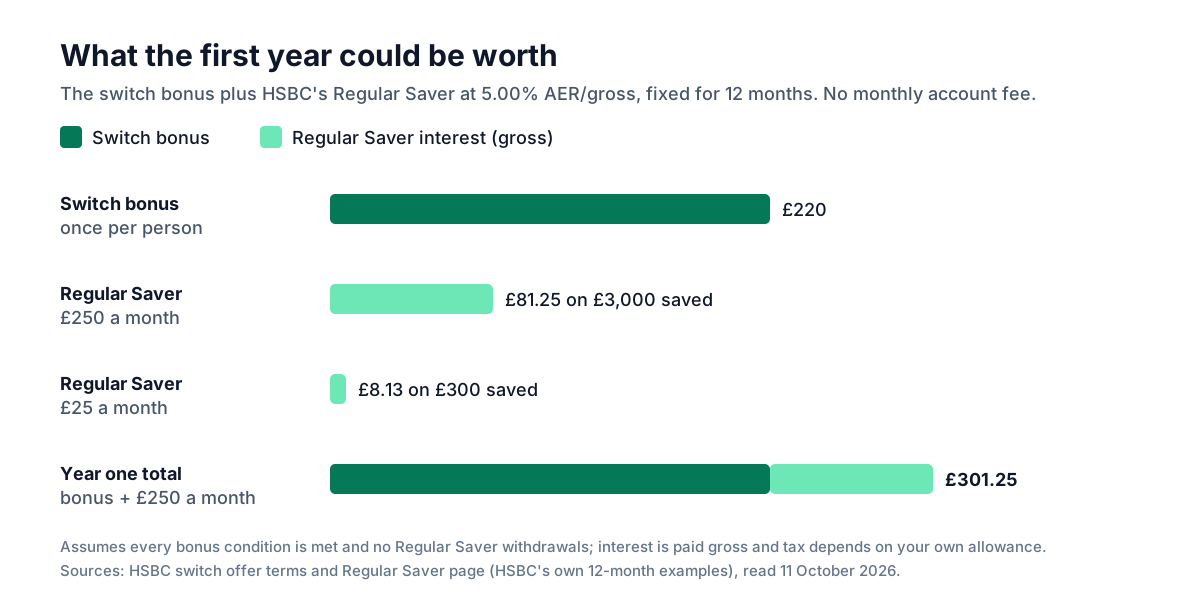
The bonus is the main value here. The £2,000 pay-in costs nothing if you move it straight back out, but the £500 of card spending is only free if it's spending you would do anyway, such as groceries, fuel or bills you can pay by card. Buying things to hit the target eats into the £220.
The Regular Saver adds a little. In HSBC's own example, £250 a month for 12 months at 5.00% AER grows to £3,081.25, which is £81.25 of interest; £25 a month earns £8.13. With the bonus and the saver maxed, year one comes to about £301.25 before any tax. Partial withdrawals aren't allowed, and closing the saver early means interest at the lower Flexible Saver rate.
On tax, HSBC says the reward may be reportable to HMRC and that you are responsible for any tax on it; it doesn't give tax advice. Savings interest is paid gross, so whether you owe tax on it depends on your Personal Savings Allowance.
Overdraft, cash and everyday fees
The overdraft is optional. The first £25 is interest-free; above that HSBC charges 34.05% a year variable (39.9% EAR), a representative 38.9% APR variable on a £1,200 arranged overdraft. You can't ask for an arranged overdraft when you open the account in the app, which is the only route to the bonus, but you can request one later.
HSBC's rates page says it stopped charging interest on unarranged overdrafts on 19 May 2026, although its printed terms still show the old pricing. Payments that would take you into one may simply be declined, and HSBC warns that an unarranged overdraft lasting more than 30 days could harm your credit rating.
You can pay in up to £3,000 in cash a day and £15,000 a calendar year across HSBC deposit machines, Post Offices, Banking Hubs and multi-bank deposit ATMs combined; above that, use an HSBC branch counter. Faster Payments in pounds are free. Receiving money from outside the UK costs £5 a payment, whether it arrives in pounds or another currency, except euros sent from within the EEA.
Using the card abroad
The Bank Account's debit card is an expensive way to pay abroad. Every payment in a foreign currency costs 2.75%, and cash machines outside the UK add 2% on top (minimum £1.75, maximum £5). A £100 meal abroad costs £2.75 extra, £100 from a cash machine costs £4.75, and a £20 withdrawal costs £2.30.
The way round it is Global Money, which is only available in the app and only to holders of an HSBC UK current account. Its multi-currency debit card spends and withdraws with no HSBC fees, you can hold 18 currencies, and cash withdrawals are capped at £500 a day; other cash machine operators may still charge. Conversions from pounds use the HSBC Global Money Exchange Rate, which includes a currency conversion charge, so check the rate shown in the app before you convert.
What customers complain about
On 11 October 2026 the HSBC UK Mobile Banking app was rated 4.8 from 1,719,239 ratings on the App Store and 4.7 from about 446,000 reviews on Google Play. HSBC UK's Trustpilot page showed 4.4 from 29,602 reviews the same day, although 34% of those reviews are one-star, and Trustpilot's separate listing for hsbc.com scores 2.1. All of these cover HSBC as a whole, not this offer.
The low-rated app reviews repeat a few themes: chat and phone support that doesn't resolve things, being locked out by security checks, trouble moving the app to a new phone, crashes, and older iPhones no longer getting updates. On Trustpilot the one-star reviews are mostly about unhelpful phone and chat support with long waits, being sent to a branch, fees, and how fraud and disputed payments are handled.
In the official service survey (Ipsos, July 2025 to June 2026, published August 2026), 58% of HSBC UK's customers in Great Britain would recommend it, 11th of 17 providers; Monzo led on 79%. HSBC came joint 7th for online and mobile banking (75%), joint 10th for overdrafts (63%) and 12th for branches (60%). Northern Ireland is kinder: 4th overall on 71% and joint 1st for online and mobile banking on 85%.
On the offer itself, MoneySavingExpert forum users who qualified in late June and early July reported the £220 arriving on 18 and 19 August, six to seven weeks later, while one person who qualified on 6 July was still waiting on 6 October. A few were refused as existing customers over relationships from before 2023; one reported HSBC paying up, with compensation, after a third final response, and another took the complaint to the Financial Ombudsman Service. Screenshot your application date, switch confirmation, pay-ins and card spending as you go.
Applying, switching and closing
You need to be 18 or over and able to provide ID, proof of address and, if needed, proof of your immigration status, and HSBC runs a credit check. For the bonus, download the HSBC UK Mobile Banking app and apply there for a sole account; you can set up the CASS switch as part of the application.
CASS moves your Direct Debits, standing orders and salary to HSBC, redirects payments sent to your old account, and closes the old account on the switch date, unless it's overdrawn, in which case you have to clear it first. The process starts 7 working days before the switch date you choose, so pick one well inside the 60 days, and make sure the old account has at least 2 active Direct Debits before you start. The switch is covered by the Current Account Switch Guarantee, which refunds any interest or charges if something goes wrong.
To leave, close the account in the app (More, then Close account), online, in a branch, by phone or by post, or switch away with CASS, which closes it automatically. The balance must be zero and there's no charge for closing, but HSBC's closing guide says payments over £10,000 or international payments incur a charge, so plan how you move a large balance out. Close any Global Money Account, fixed-rate saver or currency account first, download your statements because online statements disappear once the account closes, and remember the Regular Saver requires you to keep an HSBC current account for its 12-month term. Above all, wait until the £220 has arrived.
Who should get it, and who should skip it
Get it if you have a spare current account with at least 2 Direct Debits to switch, can put £2,000 through it and £500 of everyday spending on the card within 60 days, haven't had an HSBC UK or first direct current account since the start of 2023, and either can't get first direct's offer or would rather have the extra £10 and HSBC's branches. It also suits regular switchers, because the exclusion only looks back to 2023.
Skip it if you want a joint account, already bank with HSBC in any form, would have to buy things to reach £500, need the money quickly, or spend a lot abroad on your debit card. And if you qualify for both, first direct's offer asks less of you for £10 less.
FAQ
- Can I get the £220 if I already have an HSBC credit card or savings account?
- Probably not. The terms exclude existing HSBC UK customers without defining the word, HSBC asks existing customers to apply in a branch, and branch applications don't qualify. If in doubt, ask HSBC before you start the switch.
- Can I open a joint account for the bonus?
- No. The offer needs an account opened in the HSBC UK app, which only opens sole accounts. HSBC says applications not completed in the app, including joint applications made online, don't qualify.
- How long does the £220 take to arrive?
- You have 60 days from opening to complete the switch, the £2,000 pay-in and the £500 spend, and HSBC then pays within 60 days of you meeting everything. Allow up to about four months from opening.
- Can I move the £2,000 straight back out?
- Yes. HSBC's terms say the £2,000 can be made up of several deposits and doesn't need to stay in the account. Salary, transfers and cash all count.
- What counts towards the £500 spend?
- Purchases on your HSBC debit card, including Apple Pay, Google Pay and Samsung Pay. Cash withdrawals, fees, refunds, gambling, credit card or insurance payments, card-to-card payments and transfers from your other HSBC accounts don't count.
- Do I have to close my old account?
- Yes. The offer needs a full switch through the Current Account Switch Service, which closes the old account on the switch date and moves its Direct Debits, standing orders and salary to HSBC.
- Can I get both the HSBC and first direct switch bonuses?
- Not under the current terms. first direct excludes anyone who has opened an HSBC current account on or after 1 January 2018, and HSBC excludes first direct customers and anyone who opened a first direct current account on or after 1 January 2023.
- Is the bonus taxable?
- HSBC says the reward may be reportable to HMRC and that you are responsible for any tax on it. It doesn't give tax advice, so check your own position if you're unsure.
Featured in these guides
UK bank switch problems: payments, delays and missing incentives
A CASS troubleshooting checklist: find which date matters, preserve evidence and separate payment-transfer errors from a bank's promotional reward decision.
7 min readUK bank switching bonuses: how to switch safely and get paid
How the Current Account Switch Service works, which switching offers are open now, the banking-group rules that decide who qualifies, and a checklist so the bonus actually arrives.
9 min readUK sign-up offers for beginners: budget, eligibility and evidence
A practical starting point for people in Britain: distinguish cash from vouchers, calculate costs and choose one suitable sign-up or cashback offer.
5 min read