first direct 1st Account Review: Is It Worth Switching for £210?
The first direct 1st Account reviewed: the £210 switch bonus and its four conditions, what the account is worth once the bonus is paid, the overdraft, fees abroad, service ratings, the HSBC catch and who should skip it.
Last updated 11 October 2026
Best for
People who have never held a first direct product or opened an HSBC current account since 2018, can move an existing current account with CASS, and want a fee-free everyday account they might keep after the bonus.
Worth doing if you are eligible. The £210 is the main reason to switch now, and the four tasks are ordinary ones: switch with CASS, pay in £1,000, make five card payments and log on, all within 45 days. The account is also worth keeping afterwards: no monthly fee, no first direct fees on card spending abroad, a £250 interest-free overdraft (subject to status) and a 7.00% Regular Saver that adds £136.50 in a year at the maximum £300 a month. The catches are eligibility (any past first direct product, or an HSBC current account opened since 1 January 2018, rules you out), no branches, and an Android app rated far below the iPhone one.
Pros
- £210 switch bonus for accounts opened by 2 December 2026, with a £1,000 pay-in that can go in all at once or in parts
- No monthly fee, and no first direct fees on debit card spending or cash withdrawals abroad
- £250 interest-free overdraft, subject to status
- 7.00% AER Regular Saver for 1st Account holders, on up to £300 a month for 12 months
- Joint third overall and third for online and mobile banking in the August 2026 CMA service survey
- No branches, but cash can be paid in at HSBC counters and Post Office branches
Watch-outs
- No bonus if you have ever held a first direct product or opened an HSBC current account on or after 1 January 2018
- Four tasks to finish within 45 days of the account opening
- No branch network of its own
- The Android app is rated 2.8 on Google Play, with recent complaints that it won't open alongside third-party keyboards
- The rates sheet lists no interest on 1st Account balances
- CHAPS costs £17, and many international payments to non-HSBC banks cost £5
Current related offer
First Direct offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
First Direct
Open a 1st Account and, within 45 days, switch with CASS (at least 2 Direct Debits or standing orders), pay in £1,000, make 5 card payments and log on to the app or Online Banking. Accounts opened by 2 December 2026 get £210 (£175 plus a £35 boost); after that the £175 continues until first direct withdraws it. Note your opening date: every task counts from it.
Requirement: Within 45 days of opening: full CASS switch with at least 2 Direct Debits or standing orders, £1,000 paid in, 5 debit-card payments and a log-on to the app or Online Banking
Medium15-20 minutesPayout By the 20th of the month after the one in which you meet every condition (£175, plus £35 for accounts opened by 2 December 2026)
Verified 11 October 2026
Full claim instructions are on the First Direct offer page.
Related comparisons
What first direct is
first direct is a division of HSBC UK Bank plc, authorised by the Prudential Regulation Authority and regulated by the FCA and the PRA (Financial Services Register number 765112). It has no branch network: you bank through the app, Online Banking and the phone. In the app, a chatbot answers first and passes you to 24/7 support if it can't help, and the general enquiries phone line is open 24/7; the savings and mortgage lines keep shorter hours.
You can still pay cash in. At an HSBC branch counter, or at a Post Office using your debit card, it reaches your account straight away, although the Post Office has limits on how much you can pay in.
Because first direct uses HSBC UK's banking licence, the FSCS protects eligible deposits up to £120,000 per person, or £240,000 on a joint account, across HSBC UK, HSBC Private Bank, first direct and M&S Bank combined. If you already keep a large balance with HSBC, the limit is shared, not doubled.
The 1st Account day to day
The 1st Account has no monthly fee. It comes with a Mastercard debit card that works with Apple Pay, Google Pay and Samsung Pay. If you are approved, you get instant access and a virtual card to use straight away; the plastic card takes on average 6 days to arrive. Joint accounts are available, with a card for each holder, and you can hold more than one 1st Account.
Faster Payments in the UK are free. first direct's rates sheet lists no credit interest for the 1st Account, so assume your balance earns nothing and keep savings in the Regular Saver or elsewhere.
The £210 switch bonus
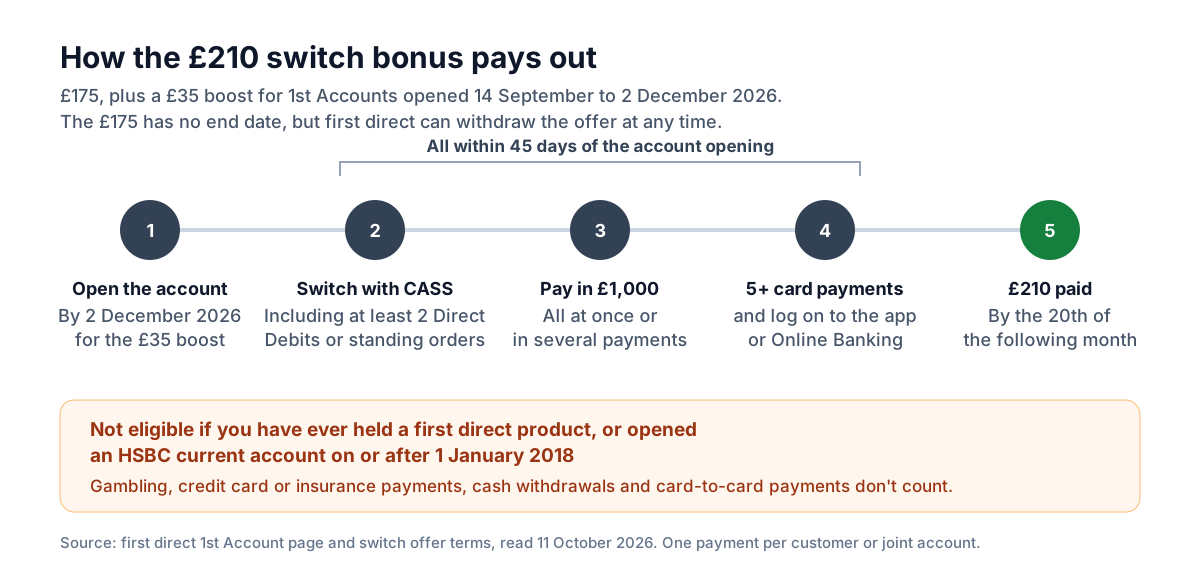
Open a 1st Account and, within 45 days of it opening: switch your current account to it with the Current Account Switch Service (CASS), including at least 2 Direct Debits or standing orders; pay in £1,000; make at least 5 debit card payments; and log on to the app or Online Banking. The live page says you get the money by the 20th of the month after the one in which you complete everything.
The £210 is £175 plus a £35 boost for accounts opened between 14 September and 2 December 2026. The base £175 has no end date in the terms, but first direct can withdraw the offer at any time.
The detail: the £1,000 can go in all at once or in several payments within the 45 days, and the terms set no rule on how long it has to stay. Card payments can be in a shop, online or through a digital wallet, with no minimum amount stated, but gambling, credit card or insurance payments, cash withdrawals and card-to-card payments don't count. On a joint account, at least one holder has to switch from a sole account in their own name or a joint account in the same names. There is one payment per customer or joint account, and the account must still be open when it is paid.
You are excluded if you have previously held any first direct product, or opened an HSBC current account on or after 1 January 2018. The offer is for UK residents and subject to status.
Two things to know. The terms PDF that first direct links to dates from 2024 and covers only the £175; it says payment comes "before" the 20th, while the live page says "by". And claims on other sites that each deposit must stay for 24 hours, or that you can recycle the same £1,000, are not in first direct's terms, so we can't confirm them. If in doubt, leave the money in until the bonus arrives.
What the first year is worth
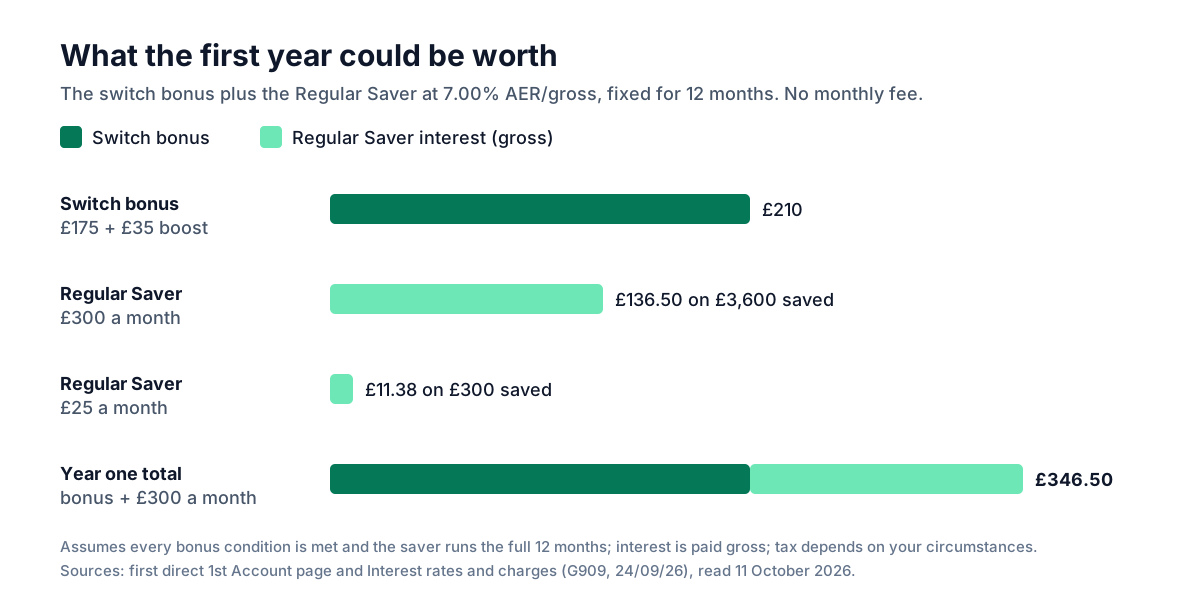
In year one the bonus is most of the value. Add the Regular Saver at the maximum £300 a month and the first year comes to £346.50 before tax: £210 from the switch and £136.50 of interest. At the minimum £25 a month, the saver earns £11.38. There is no monthly fee to set against either.
After that, the case rests on the account itself: no first direct fees on card spending abroad, a £250 interest-free overdraft buffer and a strong service record. If you need none of those, treat it as a bonus to collect, and close the account without charge once the money is paid.
The Regular Saver
Only 1st Account holders can open it. It pays 7.00% AER/gross, fixed for 12 months, on £25 to £300 a month paid in by standing order. If you pay in less than the maximum one month, you can catch up in later months. You can't make partial withdrawals, and closing it early means interest only at the variable Savings Account rate.
Interest is calculated daily and paid gross at the end of the 12 months, when the balance moves to a sole Savings Account (first direct opens one if you don't have one). Because the money goes in month by month, the average balance is about half the final total, which is why £3,600 saved earns £136.50 rather than 7% of £3,600.
The overdraft
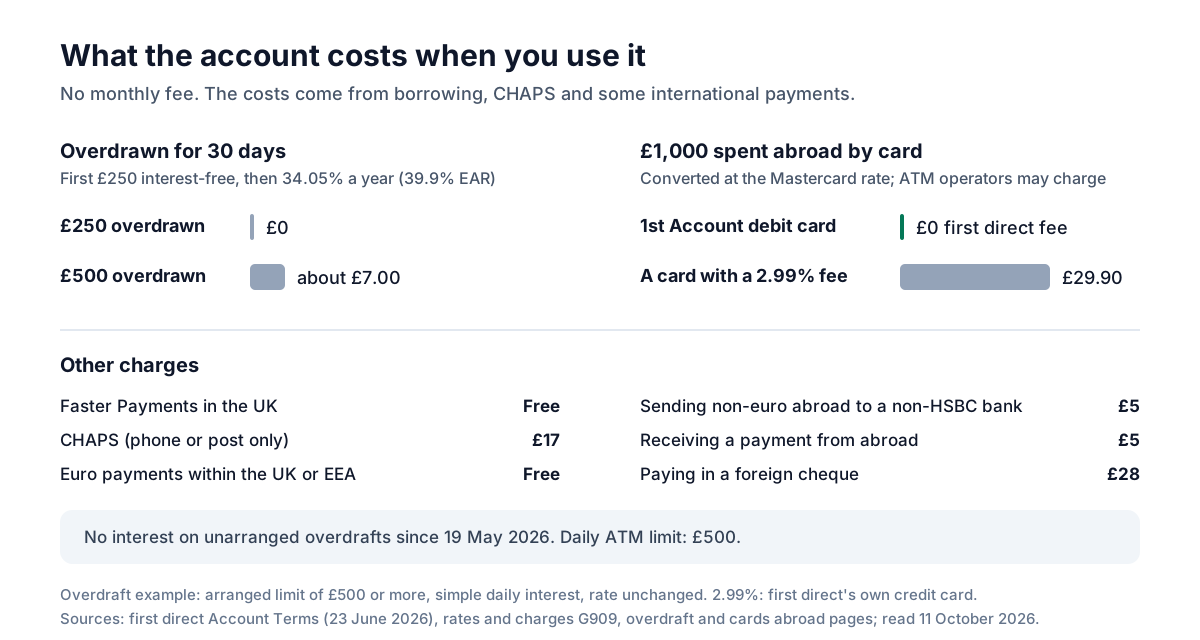
Subject to status, the first £250 of an arranged overdraft is interest-free. Above that, interest is 34.05% a year, which is 39.9% EAR variable; the representative APR is 30.5% variable, on an assumed £1,200 limit. The interest-free £250 doesn't apply if the account is linked to an Offset Mortgage.
As a worked example, £500 overdrawn for 30 days costs about £7.00 (£250 × 34.05% × 30/365), the same figure first direct gives, assuming the rate doesn't change. You get at least 14 days' notice before interest or charges are taken, and there is no interest if you pay back before 11.45pm the same day. first direct says it stopped charging interest on unarranged overdrafts from 19 May 2026, although its account terms still show the older charges; going overdrawn without an arrangement can still harm your credit rating, and payments that would take you there may be declined.
first direct shares information about how you use your account with credit reference agencies. Limits are set subject to status, and the £1,200 in the representative example is an assumption, so don't count on a particular figure.
Fees and spending abroad
first direct charges no fees for paying in a foreign currency with the debit card, whether abroad or online from the UK, and none for cash withdrawals abroad. Conversions use the Mastercard exchange rate without additional fees, but cash machine operators may add their own charge, and the daily ATM limit is £500. If a card machine offers to charge you in pounds, choose the local currency; first direct itself says you'll usually get a better rate. For comparison, £1,000 of foreign spending on a card with a 2.99% fee, such as first direct's own credit card, would cost £29.90.
The charges are on payments. CHAPS costs £17 and is only available by phone or post. Sending money to a non-HSBC account outside the UK in any currency other than euros, or in euros outside the EEA, costs £5, as does receiving a payment from abroad, in pounds or another currency. Euro payments within the UK or the EEA are free. Collecting a foreign cheque costs £28, and intermediary banks may take their own charges on international payments.
Service, and what users complain about
In the independent service quality survey published in August 2026 at the request of the Competition and Markets Authority (carried out by Ipsos from July 2025 to June 2026, covering the 17 largest providers and 17,055 people), first direct was joint third overall with 75%, third for online and mobile banking with 78%, and fifth for overdraft services with 70%. It isn't ranked for branches because it has none.
On 11 October 2026 the iPhone app was rated 4.8 from 463,986 ratings on the App Store, but the Android app only 2.8 from about 18,700 on Google Play. first direct's Trustpilot score was 4.5 from 42,735 reviews, 12% of them one-star, although Trustpilot notes that first direct hasn't invited reviews recently.
Most of the recent low-rated Android reviews (May to October 2026) are about access: users say that since an update in mid-2026 the app refuses to open if it detects a third-party keyboard or another app it treats as unapproved, and some users on custom Android versions or in Samsung's Secure Folder report being locked out. first direct's replies confirm it may restrict access if it detects unapproved third-party apps, including keyboards, and suggest switching back to the default keyboard. Other repeated themes are new applicants stuck at the selfie and photo ID check, an app that feels basic and dated next to app-only banks, too many steps for regular payments, awkward sharing of account details, and cheque scanning that struggles to focus.
first direct or HSBC?
first direct and HSBC are one banking group, and each one's switch bonus shuts out recent customers of the other. first direct won't pay anyone who opened an HSBC current account on or after 1 January 2018. HSBC's £220 offer excludes existing HSBC UK and first direct customers and anyone who has held an HSBC UK or first direct current account since 1 January 2023. In practice, pick one.
HSBC pays £10 more but asks for more within 60 days: £2,000 paid in, £500 of card spending and 2 Direct Debits. first direct asks for £1,000, five card payments with no minimum amount stated, and accepts standing orders as well as Direct Debits, within 45 days. HSBC has branches; first direct doesn't, though you can pay cash in at an HSBC counter. Money held with both shares one £120,000 FSCS limit.
Applying, switching and closing
You need to be over 18 and a UK resident, not have been declared bankrupt or entered an Individual Voluntary Arrangement in the last six years (or be in the process of either), and have a phone number and email address. You'll be asked for proof of identity and address, and in some cases proof of income. Accounts are subject to status, and first direct says it runs a credit search with TransUnion, Equifax and Experian as part of the application; it doesn't say whether that is a hard or soft search.
Apply in the first direct app. Once the account is open and the identity checks are done, tap 'switch to us' in the app and choose a switch date at least 7 working days away, not on a weekend or bank holiday. CASS moves your Direct Debits, standing orders, salary and balance, and your old bank closes the old account. Card payments set up with your old card details (continuous payment authorities) and credits from overseas don't move, so update those yourself. You can cancel the switch up to 7 working days before the switch date.
The account page gives you 14 days after you receive your welcome pack to close the account if you're not happy; the terms put the cooling-off period at 14 days from the day after first direct confirms the account is open. After that you can still close it at any time, online, by phone or in writing, without charge. Download what you need from Online Banking first and, if you want the bonus, keep the account open until it is paid.
Who should get it, and who should skip it
Consider it if you have never had a first direct product or opened an HSBC current account since 2018, if you can move an existing account with CASS and pay in £1,000 within 45 days, and especially if you would use what the account does well: fee-free card spending abroad, a small interest-free overdraft buffer and the 7.00% Regular Saver.
Skip it if you have opened an HSBC current account since 1 January 2018 or would rather have HSBC's £220, if you need a branch for anything more than paying in cash, if you bank on Android and the app's reviews put you off, or if you want interest on your current account balance.
FAQ
- How do I get the £210?
- Open a 1st Account by 2 December 2026 and, within 45 days of it opening, switch with CASS including at least 2 Direct Debits or standing orders, pay in £1,000, make 5 or more debit card payments and log on to the app or Online Banking. Accounts opened later get £175 while that offer lasts.
- When is the bonus paid?
- By the 20th of the month after the one in which you complete every condition, according to the live account page. The account must still be open on that date.
- Can I get it if I have banked with HSBC?
- Not if you opened an HSBC current account on or after 1 January 2018, or have ever held a first direct product. HSBC's own switch offer also excludes first direct customers, so you will usually get one bonus or the other.
- Does the £1,000 have to stay in the account?
- The terms let you pay it in all at once or in several payments within 45 days and set no rule on how long it stays. Claims elsewhere about 24-hour holds or recycling the same money aren't in first direct's terms, so leaving it in until the bonus arrives is the safe option.
- Is it free to use abroad?
- first direct charges nothing for debit card payments in a foreign currency or for cash withdrawals abroad, and uses the Mastercard exchange rate. Cash machine operators may charge, and the daily ATM limit is £500.
- Is my money protected?
- Yes, by the FSCS up to £120,000 per person (£240,000 on a joint account), but that limit is shared across HSBC UK, HSBC Private Bank, first direct and M&S Bank.
- Does applying affect my credit score?
- first direct says it runs a credit search with the three credit reference agencies as part of the application, but doesn't say whether it is a hard or soft search. It also shares information about how you use your account with them.
- Can I close the account after the bonus?
- Yes, at any time, online, by phone or in writing, without charge. Wait until the bonus has been paid, because the account must still be open on the payment date.
Featured in these guides
UK bank switching bonuses: how to switch safely and get paid
How the Current Account Switch Service works, which switching offers are open now, the banking-group rules that decide who qualifies, and a checklist so the bonus actually arrives.
9 min readUK sign-up offers for beginners: budget, eligibility and evidence
A practical starting point for people in Britain: distinguish cash from vouchers, calculate costs and choose one suitable sign-up or cashback offer.
5 min read